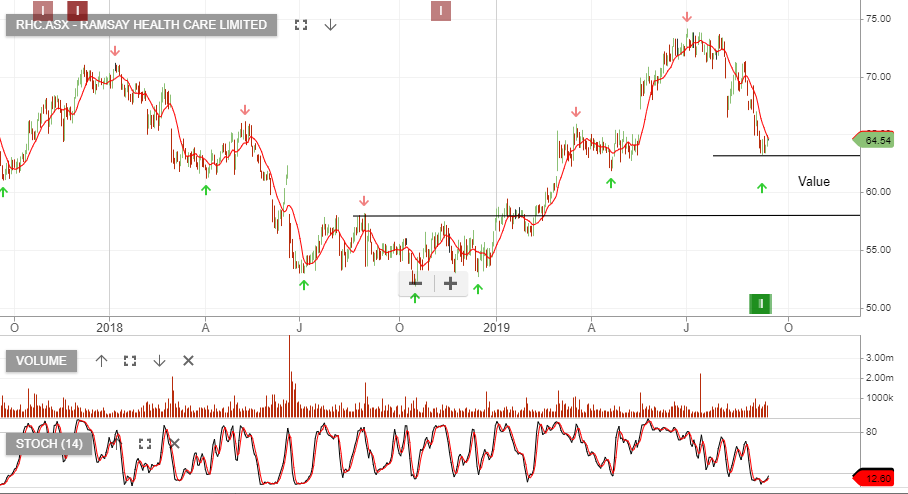
Ramsay Healthcare – Buy Signal

Ramsay Health Care is under Algo Engine buy conditions and has now been added into the ASX 100 model portfolio.

We see price support developing near $62, following Ramsay Health Care advising that Paul Ramsay Holdings has completed the underwritten block trade sale of 22m shares in the Company to institutional investors at $61.80 per share.

Buy RHC at $62.00
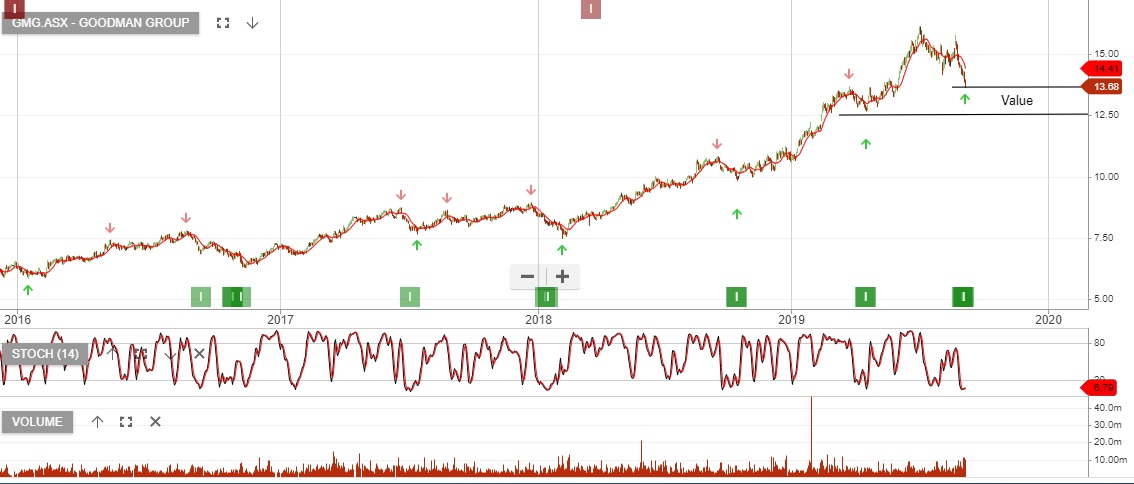
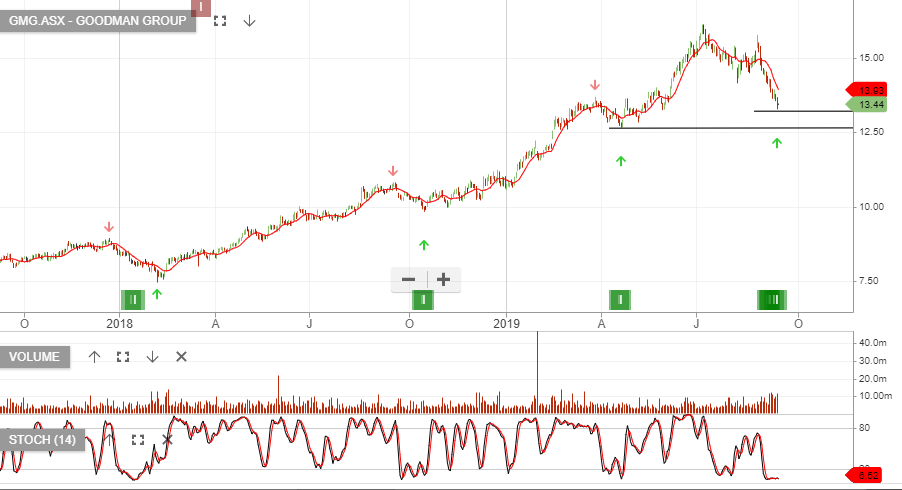
Goodman Group – Buy Signal “High Conviction”

Goodman is under Algo Engine buy conditions and is among the best-performing stocks within our ASX 100 model portfolio.

The company announced FY19 profit of $942m, up 11% on EPS of $0.51. The Group is forecasting FY20 operating profit of $1,040m, up 10% on $0.56 EPS.

We continue to like the REIT sector as a defensive allocation. Our preference remains GPT & GMG.

Buy GMG $13.50 


Webjet – Opportunity Approaches

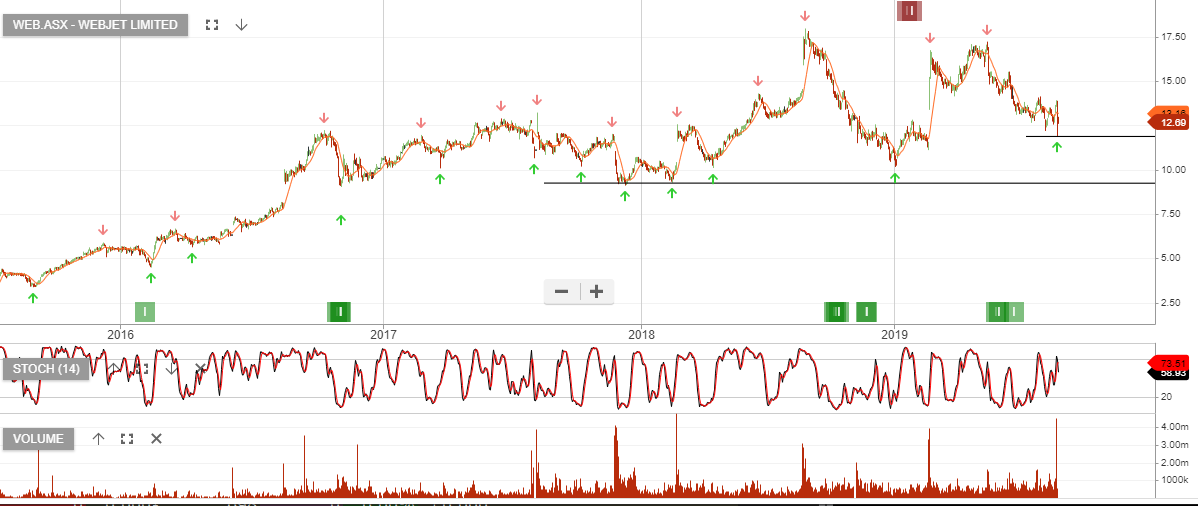
Webjet is under Algo Engine buy conditions.

FY19 earnings grew at 43% and were ahead of market consensus.  EBITDA was $125mn. FY20 guidance is now between $150mn and $200mn, representing 30%+ growth for next year.

The stock trades on a 1.9% dividend yield. Webjet goes ex-div $0.135 on 18th Sept and we expect our buy target of sub $12.00 to occur.

We see buying supporting building within the $11.50 to $12.00 range.

 –


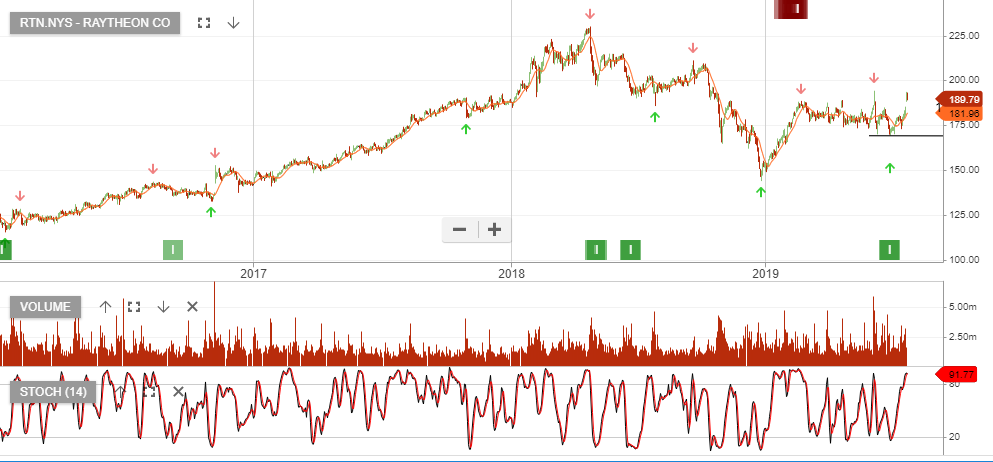
Raytheon – High Conviction Buy

Raytheon, (listed on the New York Stock Exchange) is now under Algo Engine buy conditions and was added into our US S&P100 model portfolio, prior to last week’s earnings result.

Raytheon is a major U.S. defense contractor and industrial corporation with core manufacturing concentrations in weapons, military and commercial electronics. In 2020 the company will merge with United Technologies and we anticipate the merger will help unlock value for shareholders and underpin the growth story for many years to come.

The stock trades 19x earnings and a 2 % dividend yield. A combination of the upcoming merger and the large scale of future share buybacks has Raytheon on our “high conviction” buy list.

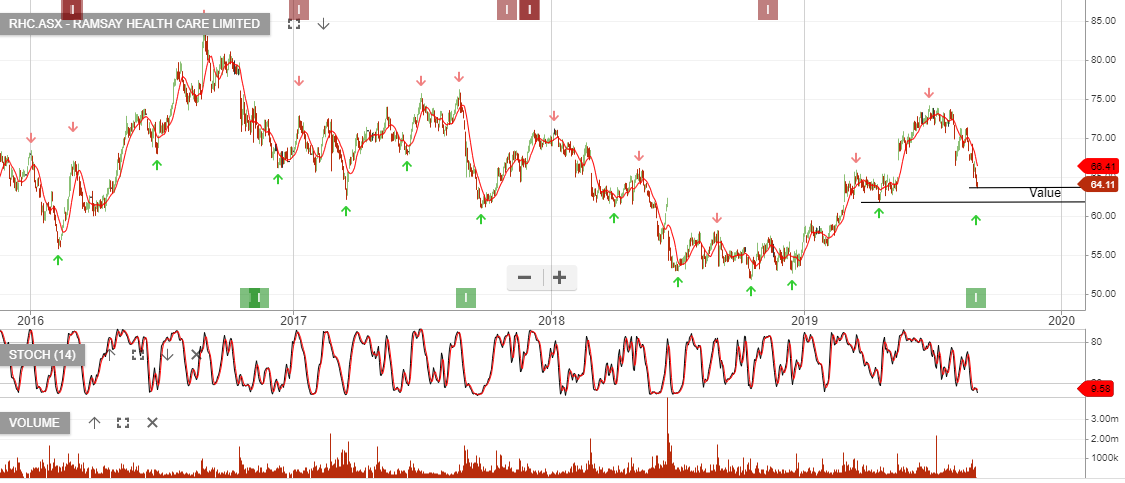
Ramsay Healthcare – Valuation Review

Ramsay Health Care is under Algo Engine buy conditions and is a current holding in our ASX 100 model portfolio.

RHC trades on 21x forward earnings, dividend yield of 2.4% and underlying EPS growth into FY20 of 2 – 4 %.  Forecast FY20 revenue $13bn, EBIT $1.2bn, EPS $3.00 & DPS $1.55.

In a low rate environment, we see the new trading range for Ramsay within the $65 – $70 band.

We see buying support building at the $64 price level.