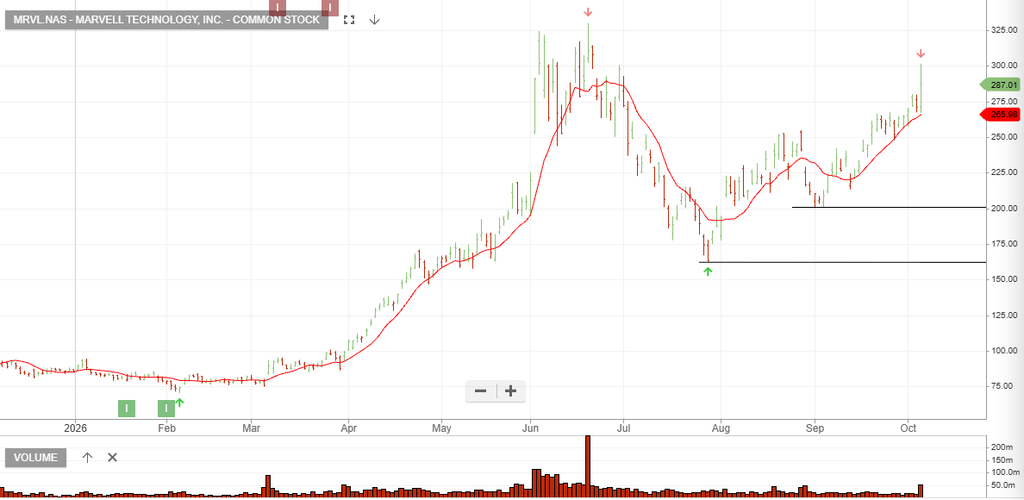
Marvell
Marvell Technology, Inc. – Common
Next Earnings Date: Thursday, August 27, 2026 (After US Market Close / 1:45 PM PT)
- Reporting Period: Q2 Fiscal Year 2027
Expected Revenue & Growth
- Consensus Revenue Estimate: ~$2.70B – $2.71B
- Company Guidance Range: $2.565B – $2.835B (Midpoint: ~$2.70B)
- Prior Year Comparison (Q2 FY2026): $2.01B
- Expected YoY Revenue Growth: ~34% to 35% YoY, powered by robust AI data center demand (electro-optics, custom silicon, and switching).
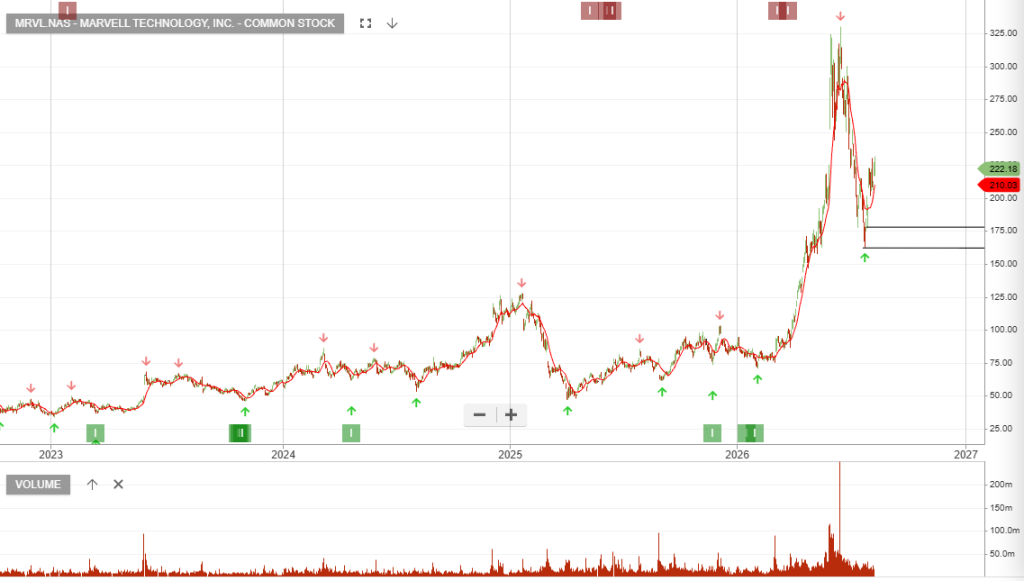
Marvell
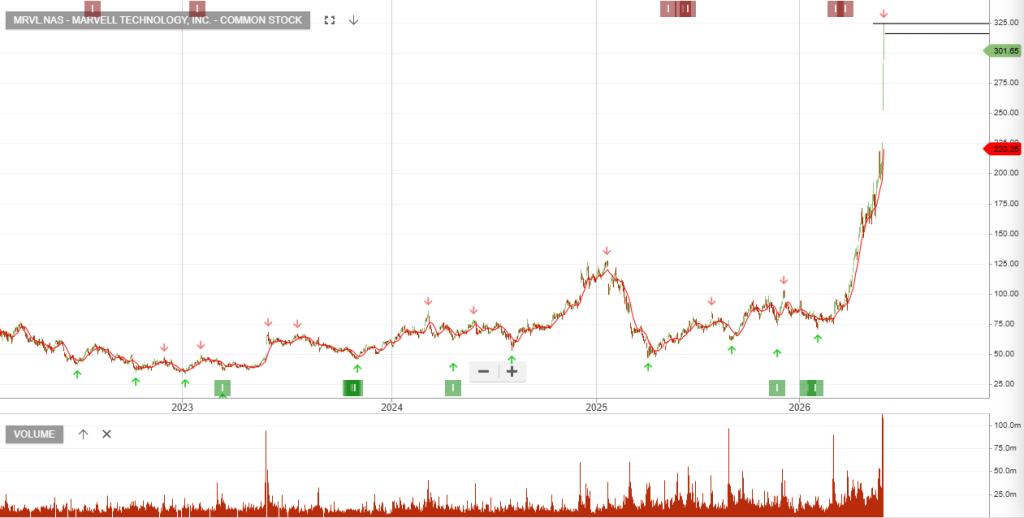
Marvell Technology, Inc. – Common is rated a buy with the stop loss at $177.57
Upcoming Earnings Outlook: Expected Release Date: August 27, 2026 (After Market Close)
- Fiscal Period: Q2 Fiscal Year 2027 (Quarter ending late July 2026)
- Consensus Estimates: Non-GAAP EPS: $0.87 – $0.93 per share (vs. $0.67 in Q2 FY2026, representing ~30%–38% YoY growth)
- Consensus Revenue: ~$2.60B – $2.71B (vs. $2.01B in Q2 FY2026, representing ~30%–35% YoY growth)
Key Drivers & Long-Term Growth Outlook: Marvell’s custom ASIC program (designing tailored AI chips for cloud hyperscalers like AWS, Google, and Microsoft) and optical connectivity solutions (800G / 1.6T DSPs) remain the primary catalyst.
- Accelerating Quarterly Trajectory: Management guided sequential revenue acceleration throughout FY2027, aiming for quarterly revenue to reach ~$3.0 billion in Q3 and Q4.
Full-Year FY2027 & FY2028 Targets:
- FY2027 Revenue: Expected to reach ~$11.5 billion (+40% YoY growth), driven by >50% growth in the Data Center segment and >70% growth in optical interconnects.
- FY2028 Target: Revenue guided toward ~$16.5 billion as cloud hyperscaler AI capital expenditure expands further.
Key Things to Watch on Earnings Day
- Custom AI ASIC Shipments: Progress on hyperscaler customer design wins ramping into volume production.
- Gross & Operating Margins: Non-GAAP gross margins (target zone ~59–60%) and expense control as R&D investment increases.
- Hyperscaler AI Capex Trends: Any commentary on customer demand pacing for 800G/1.6T electro-optics and PCIe/CXL switches.
- Supply Chain Capacity: Lead times and substrate/co-packaged optics assembly capacity.
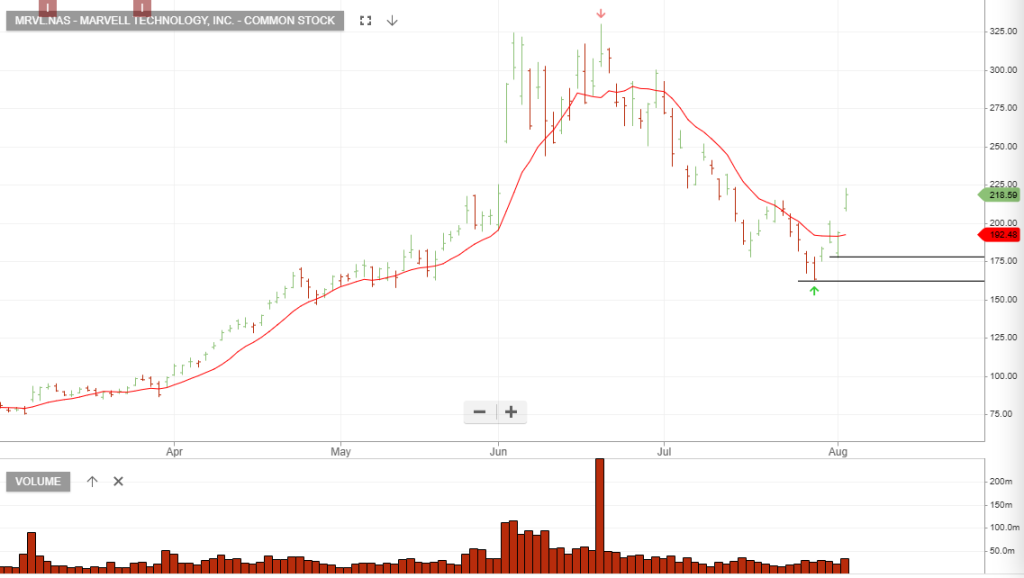
Marvell
Marvell Technology, Inc. – Common
Upcoming Earnings Outlook: Expected Release Date: August 27, 2026 (After Market Close)
- Fiscal Period: Q2 Fiscal Year 2027 (Quarter ending late July 2026)
- Consensus Estimates: Non-GAAP EPS: $0.87 – $0.93 per share (vs. $0.67 in Q2 FY2026, representing ~30%–38% YoY growth)
- Consensus Revenue: ~$2.60B – $2.71B (vs. $2.01B in Q2 FY2026, representing ~30%–35% YoY growth)
Key Drivers & Long-Term Growth Outlook: Marvell’s custom ASIC program (designing tailored AI chips for cloud hyperscalers like AWS, Google, and Microsoft) and optical connectivity solutions (800G / 1.6T DSPs) remain the primary catalyst.
- Accelerating Quarterly Trajectory: Management guided sequential revenue acceleration throughout FY2027, aiming for quarterly revenue to reach ~$3.0 billion in Q3 and Q4.
Full-Year FY2027 & FY2028 Targets:
- FY2027 Revenue: Expected to reach ~$11.5 billion (+40% YoY growth), driven by >50% growth in the Data Center segment and >70% growth in optical interconnects.
- FY2028 Target: Revenue guided toward ~$16.5 billion as cloud hyperscaler AI capital expenditure expands further.
Key Things to Watch on Earnings Day
- Custom AI ASIC Shipments: Progress on hyperscaler customer design wins ramping into volume production.
- Gross & Operating Margins: Non-GAAP gross margins (target zone ~59–60%) and expense control as R&D investment increases.
- Hyperscaler AI Capex Trends: Any commentary on customer demand pacing for 800G/1.6T electro-optics and PCIe/CXL switches.
- Supply Chain Capacity: Lead times and substrate/co-packaged optics assembly capacity.
Marvell Technology
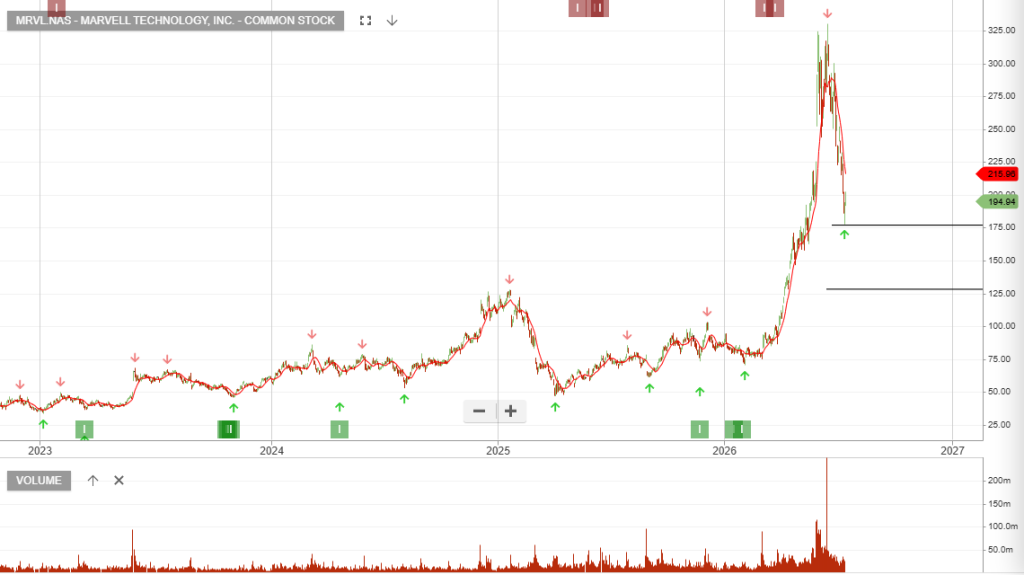
Marvell Technology
Marvell Technology, Inc. – Common: Noted – Jensen Huang’s high-profile backing of the chipmaker at Computex.
Expected Revenue & Growth: Driven by accelerating AI data center and custom silicon demand, Marvell raised its growth guidance significantly during its last earnings call:
- Q2 FY2027 Revenue Guidance: Guided to $2.7 billion (±5%).
Year-over-Year (YoY) Growth: Represents ~35% YoY growth (beating previous consensus of $2.6 billion).
Sequential Growth: Represents ~12% sequential growth from Q1 FY2027.
- Full-Year FY2027 Revenue Outlook: Raised to ~$11.5 billion (up from prior guidance of ~$11.0 billion).
YoY Growth: Approximately 40% growth year-over-year.
- Full-Year FY2028 Revenue Outlook: Raised to ~$16.5 billion.
YoY Growth: Approximately 45% growth compared to
Marvell Technology
Marvell Technology, Inc. – Common
Revenue growth projections have increased to 33% in FY27 and 37% in FY28, with EPS growth outpacing top-line gains.
At 30x forward P/E and 16x FY28 EPS, valuation remains attractive.

Marvell Technology, Inc. gains a transformative growth catalyst from Nvidia’s $2B investment today, solidifying its AI connectivity market position.
Marvell’s strategic pivot from XPU to optical networking and silicon photonics, supported by key acquisitions, expands its TAM to ~$94B.

Level 17 Chifley Tower
2 Chifley Square
Sydney, NSW 2000
1300 614 002
Investor Signals Pty Ltd
ABN 44 143 555 453