RTX

Third quarter 2026

  • Sales of $25.0 billion, up 11 percent versus prior year, and up 12 percent organically*
  • GAAP EPS of $1.89, including $0.26 of acquisition accounting adjustments and $0.11 of restructuring and other net significant and/or non-recurring items
  • Adjusted EPS* of $2.26, up $0.56, or 33 percent, versus prior year, including $0.25 from IEEPA cost recovery
  • Operating cash flow of $2.9 billion, including approximately $0.3 billion from IEEPA recovery; free cash flow* of $2.1 billion
  • Company backlog of $340 billion, including $176 billion of commercial and $164 billion of defense
  • Awarded Tomahawk and AMRAAM multi-year undefinitized production contracts in the third quarter

Updates outlook for full year 2026

  • Adjusted sales* of $97.0 – $97.5 billion, up from $95.0 – $96.0 billion
  • Organic sales growth* of 10 to 11 percent, up from 8 to 9 percent
  • Adjusted EPS* of $7.65 – $7.75, up from $7.10 – $7.25
  • Free cash flow* of $9.0 – $9.2 billion, up from $8.50 – $8.75 billion
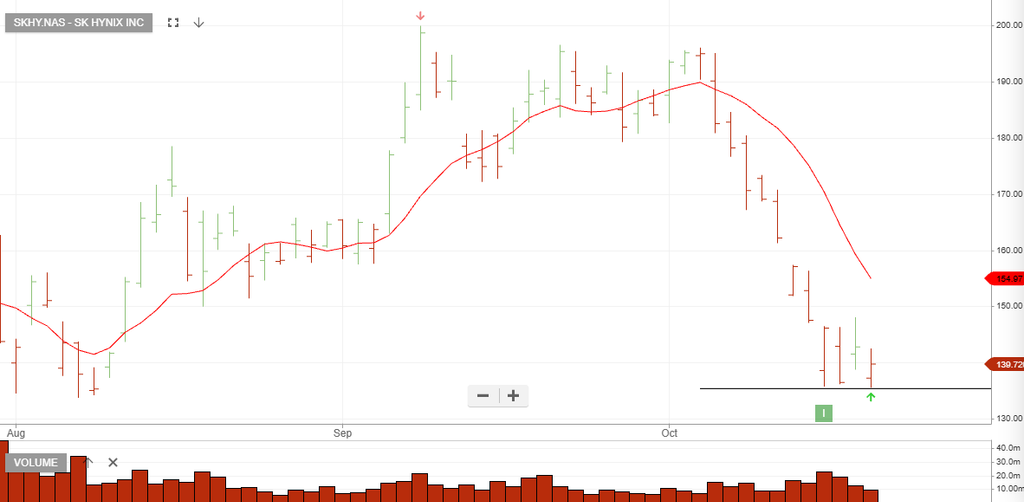
SK Hynix

Q3 is expected to show 37% sequential and 336% annual revenue growth, with analysts projecting $6.25 adjusted EPS on $74.6B revenue.

Outlook:

Q3 should deliver around $6.25 EPS, on around $75B in revenue, annual growth of 336%, up from around $17.1B. .

1. Upcoming Earnings Date

  • Next Earnings Release: October 28, 2026 (9:00 AM KST) / October 27, 2026 (US ET).
  • Period: FY2026 Third Quarter (Q3).

2. Expected Revenue & Growth

  • Consensus Q3 Revenue Forecast:
  • ~₩99.7 Trillion – ₩100.6 Trillion KRW (equivalent to approximately $74.6 Billion USD).
  • Expected Revenue Growth:
  • Year-over-Year (YoY): ~+300% to +330% (up from ₩24.45 Trillion KRW in Q3 2025).
  • Quarter-over-Quarter (QoQ): ~+26% to +27% sequential expansion over Q2 2026 (₩79.32T KRW).

3. Expected Profit / Earnings Growth

  • Consensus Q3 EPS Estimate:
  • ~$6.12 – $6.25 USD per ADR (analyst consensus ranges).
  • Expected Profit Growth:
  • Year-over-Year (YoY): ~+370% to +390% YoY (compared to $1.25 EPS reported in Q3 2025).
  • Profitability continues to be propelled by strong demand and pricing power across high-bandwidth memory (HBM3E / HBM4) and enterprise server DRAM/NAND.