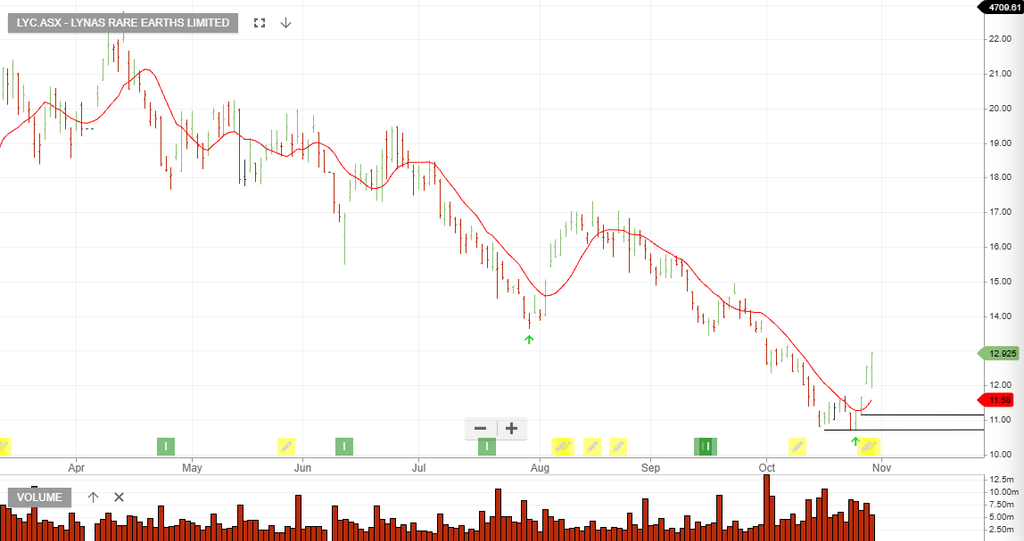
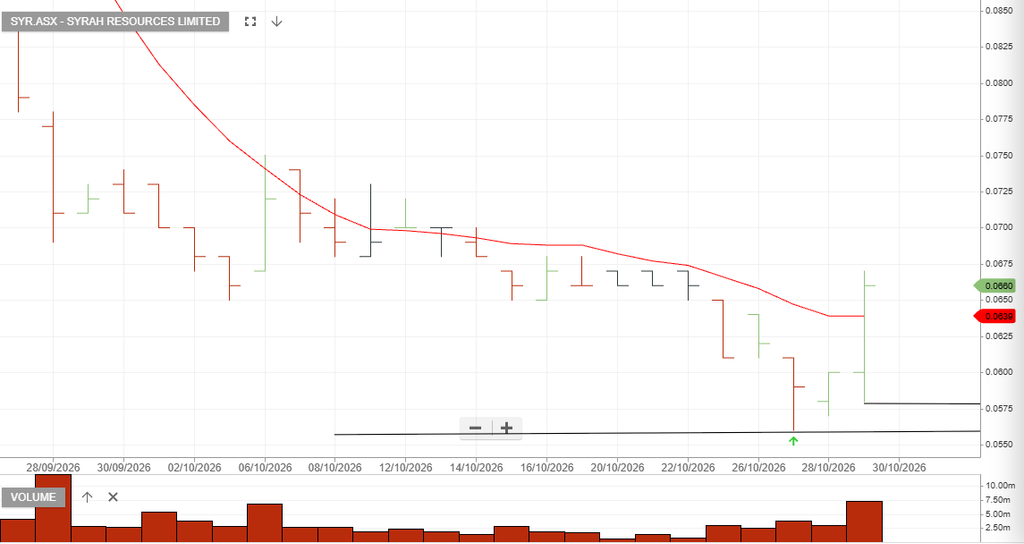
Syrah Resources
Syrah Resources is a speculative buy.
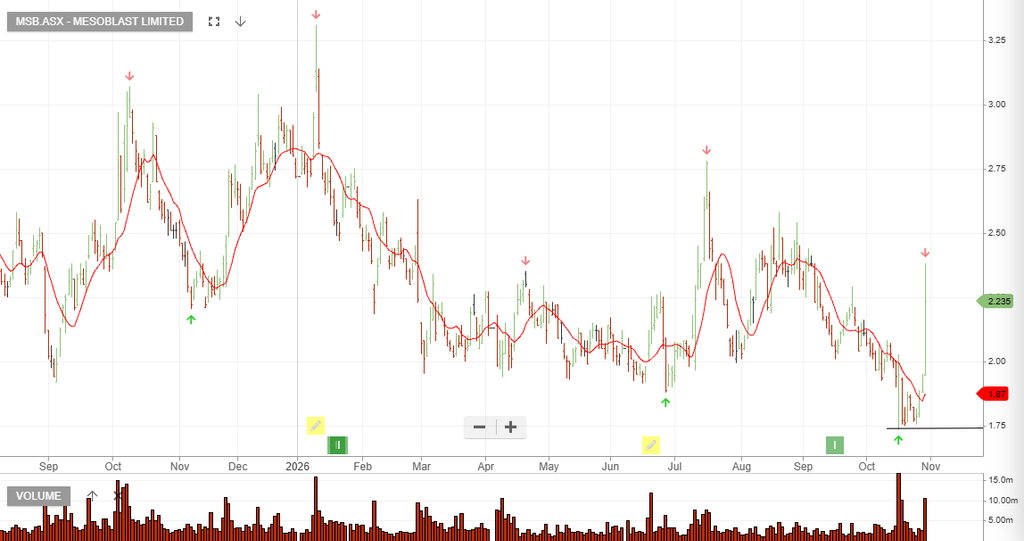
Mesoblast
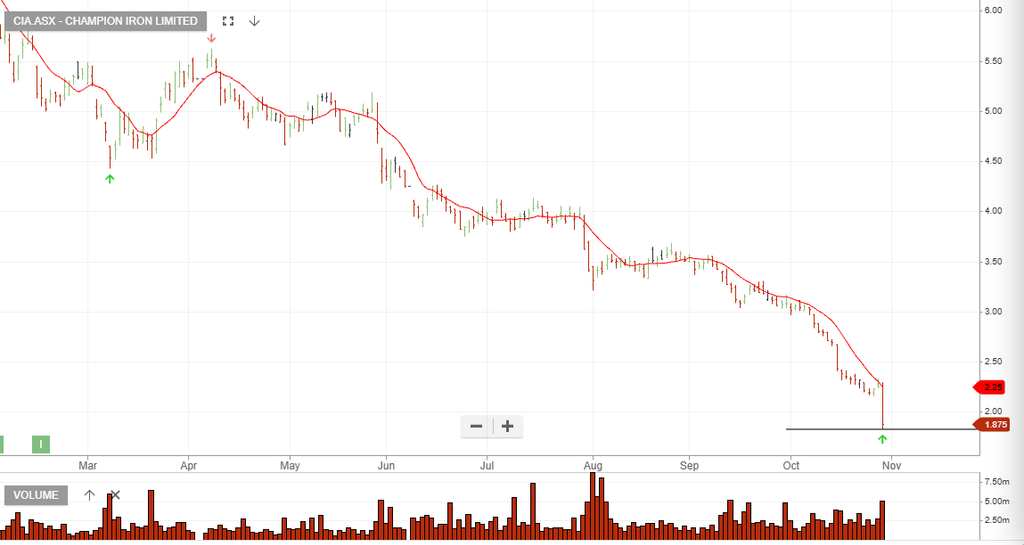
Champion Iron
Champion Iron add to watchlist.
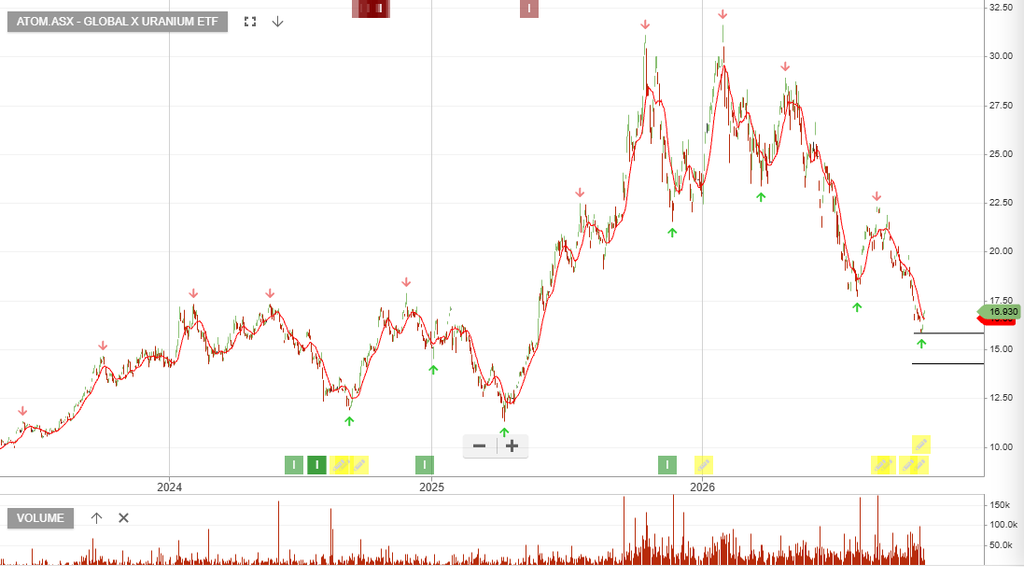
Uranium sector
The uranium sector continues to offer attractive long-term investment opportunities, supported by growing global demand for nuclear energy, particularly as AI and data centre expansion increases electricity requirements. Funding certainty has emerged as a key differentiator, with fully funded producers and developers outperforming companies still seeking capital.
Bannerman Energy stands out following its strategic CNNC partnership and successful equity raising, leaving its Etango project fully funded through construction without requiring debt under the base case.
Boss Energy delivered encouraging quarterly production despite weather disruptions, while Paladin Energy is expected to recover from a weaker first quarter as production improves.
Deep Yellow continues progressing its Tumas project but has deferred its final investment decision amid challenging funding conditions. Overall, the recent AI-led sector selloff may present an attractive opportunity to increase uranium exposure, particularly in companies with strong balance sheets, secured funding and credible production growth prospects.
Global X Uranium is rated a buy
Liontown
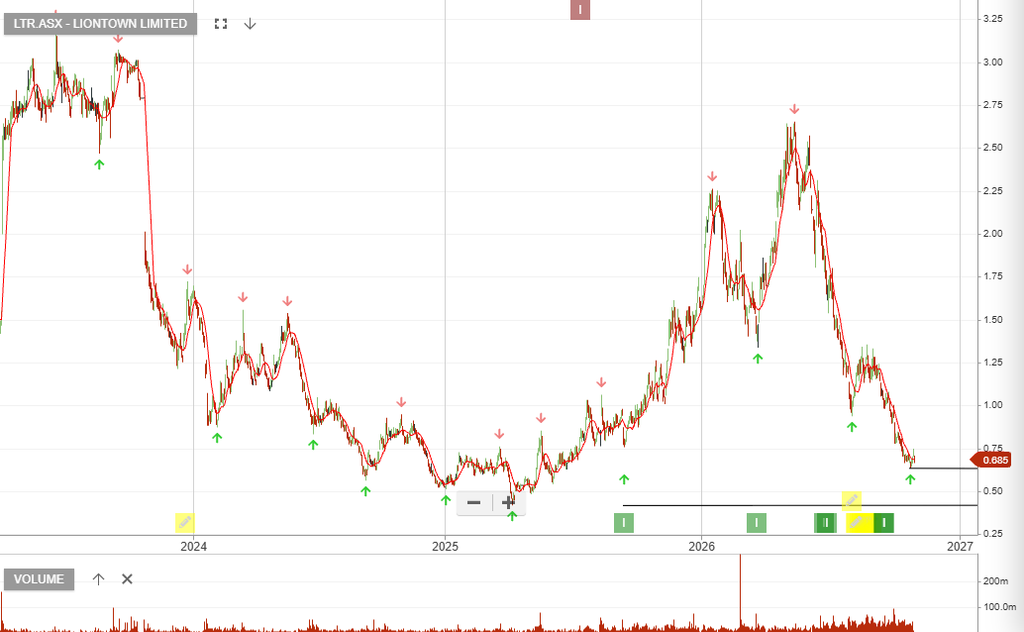
The company’s latest quarterly results reflect a challenging transition to underground mining, with production expected to improve significantly in the second half of FY2027.
Operating cash flow was A$47 million, or approximately A$69 million excluding a one-off customer settlement, while cash reserves remained strong at A$502 million despite increased capital expenditure and debt repayments. Importantly, the company appears well-funded to complete its A$389 million expansion program, with FY2027 capital expenditure forecast at A$175–195 million.
Although the quarter likely represents the low point in production, achieving full-year guidance will depend on increasing underground ore throughput towards 2.8Mtpa and improving recovery rates towards 70%. Successful execution could provide a meaningful catalyst for production growth, improved profitability and a potential share price re-rating.
Lynas
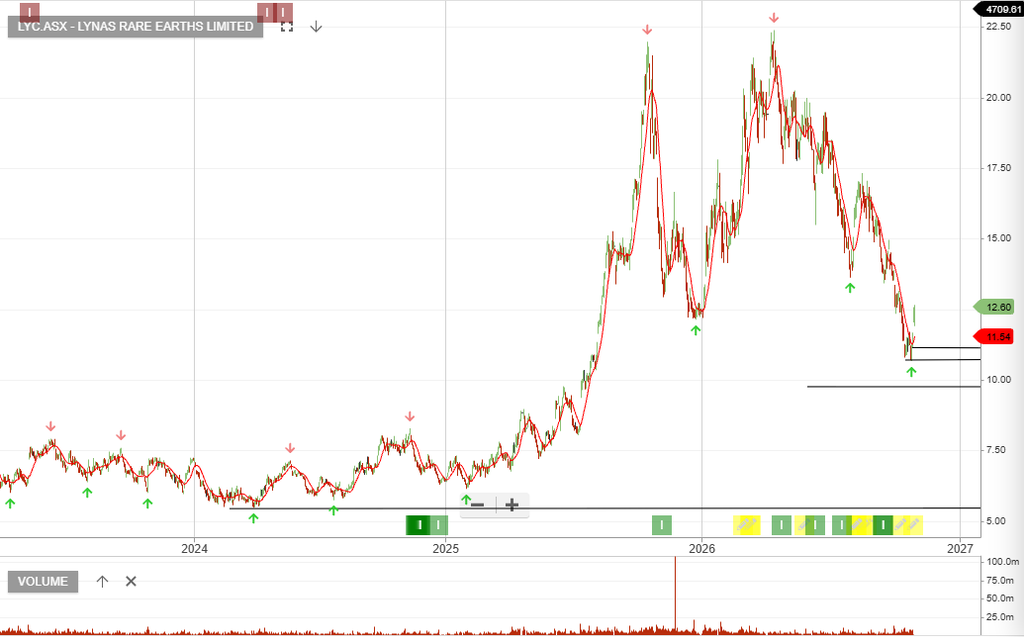
Lynas Rare Earths released an exceptional Q1 FY27 quarterly report this morning. Sales revenue jumped 55% year-on-year to $310.1m (the highest quarterly revenue since Q4 FY22), with record average selling prices of $102.1/kg (+88% YoY) supported by bundled shipments and floor-price supply agreements covering over 50% of output. Total REO production hit 4,254 tonnes (NdPr 2,082 tonnes), with cash reserves expanding to $1.212bn.
Meta
Resources
World Bank tipped commodity prices to rise 23% in 2026, with energy up 32% and metals up 25% to a record as aluminium, copper and tin set new highs.
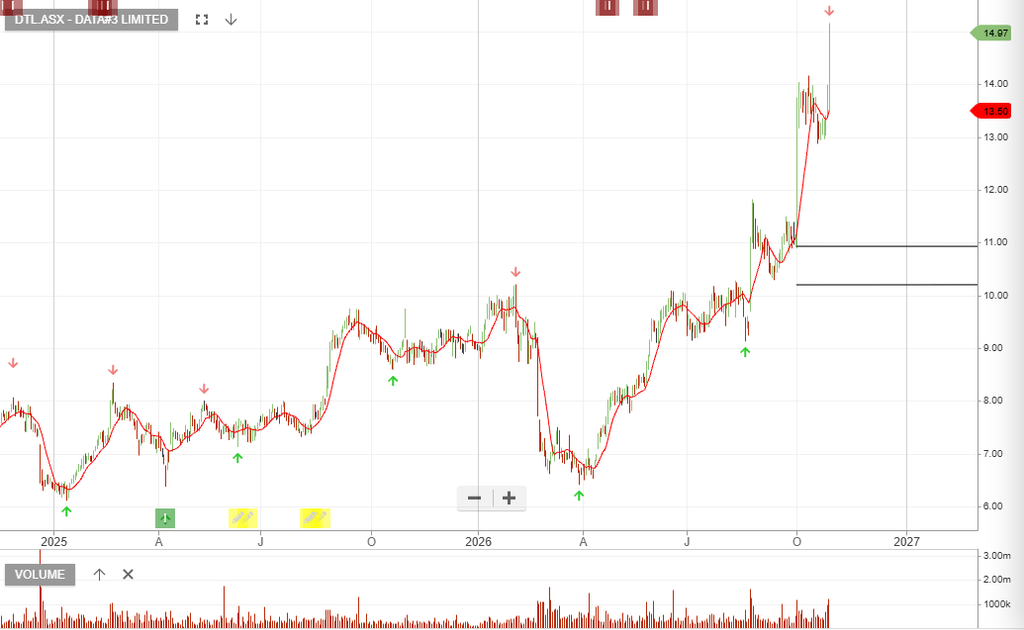
Data#3
Delivered its second 1H27 profit guidance upgrade in a month, lifting 1H27 PBT expectations to $52–57m (a 55–70% YoY increase), driven by hardware replacement cycles, AI enablement, firming customer delivery dates, and higher interest income.

Level 17 Chifley Tower
2 Chifley Square
Sydney, NSW 2000
1300 614 002
Investor Signals Pty Ltd
ABN 44 143 555 453