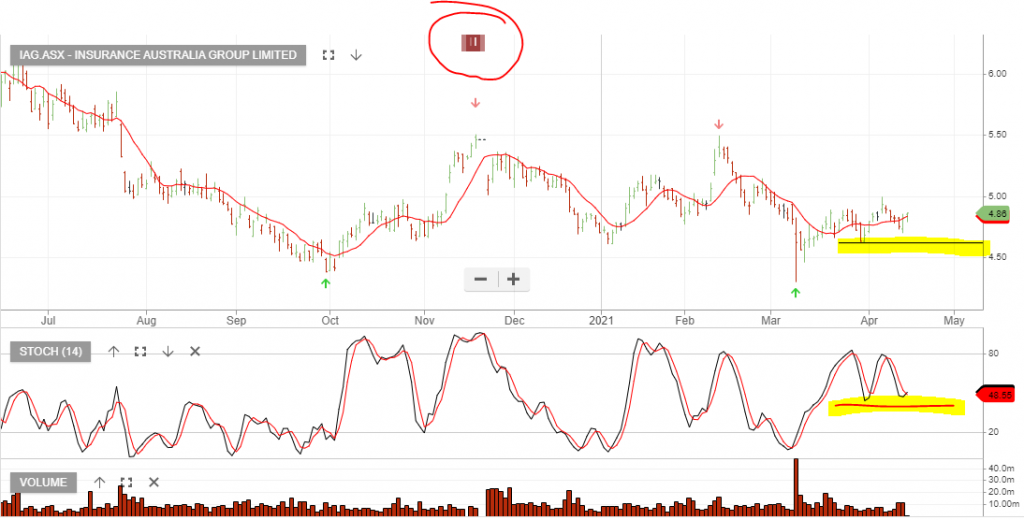
We add IAG to our “high risk” recovery basket, which also includes CIM & A2M.
We expect IAG to see improved earnings into FY22 & FY23. It’s likely we’re nearing the inflection point, where investors begin pricing in the anticipated recovery.
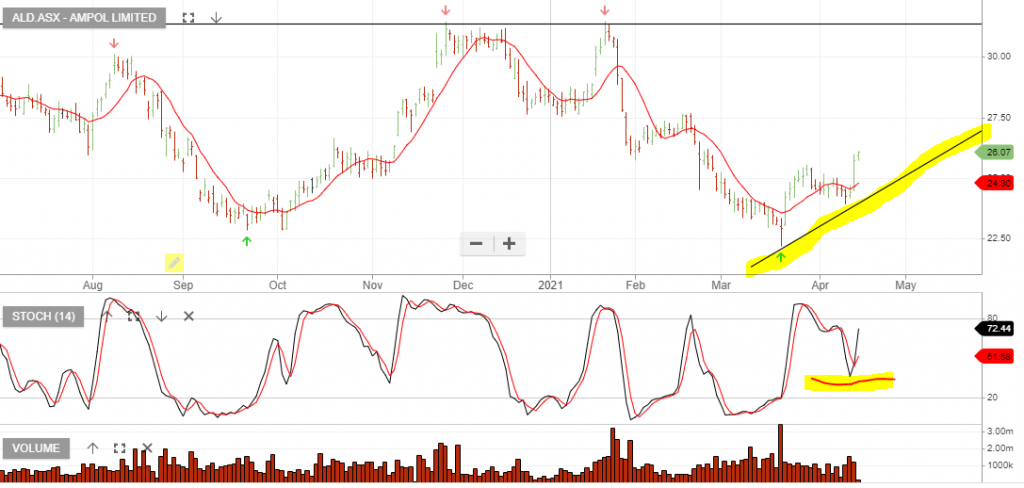
Ampol has reported its financials for the 12 months ending 31 December 2020, with full year earnings of $401 million. Earnings were down from $607 million in the year prior.
1Q21 EBIT was A$150mn, but included an A$18mn FX gain.
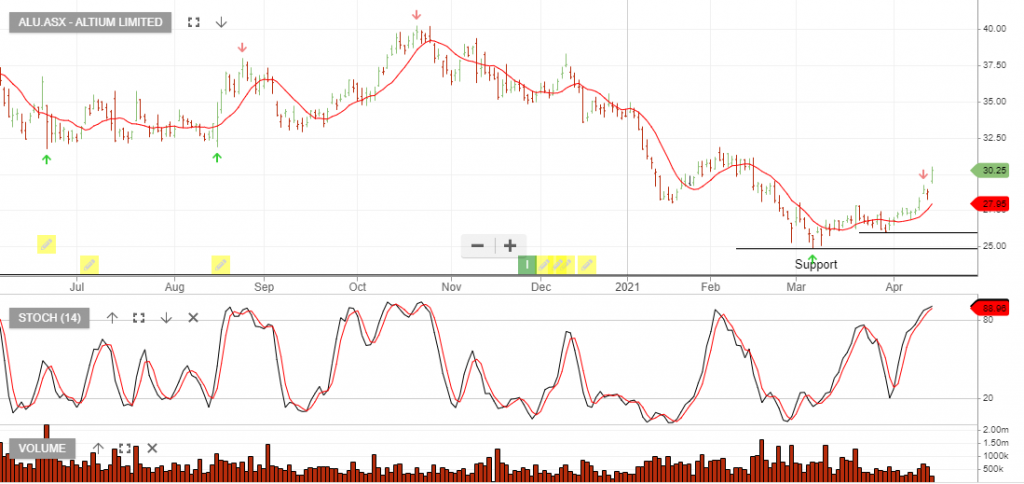
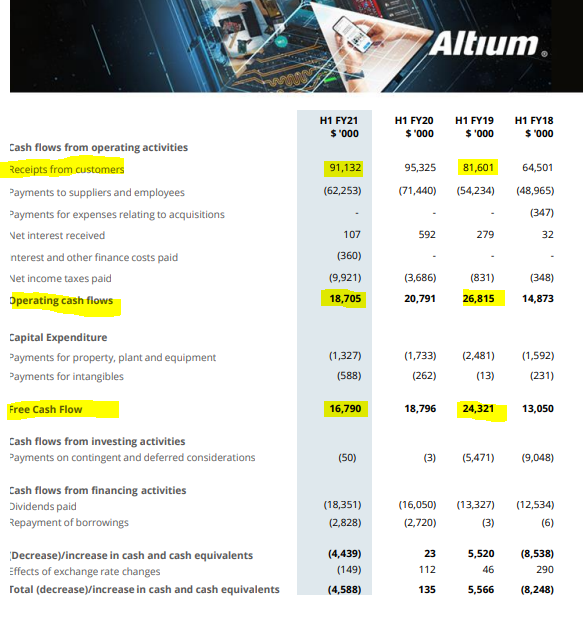
ALU:ASX is under Algo Engine buy conditions and has now rallied 20% from the recent low. Our interest in the business has increased and the stock is now under review.
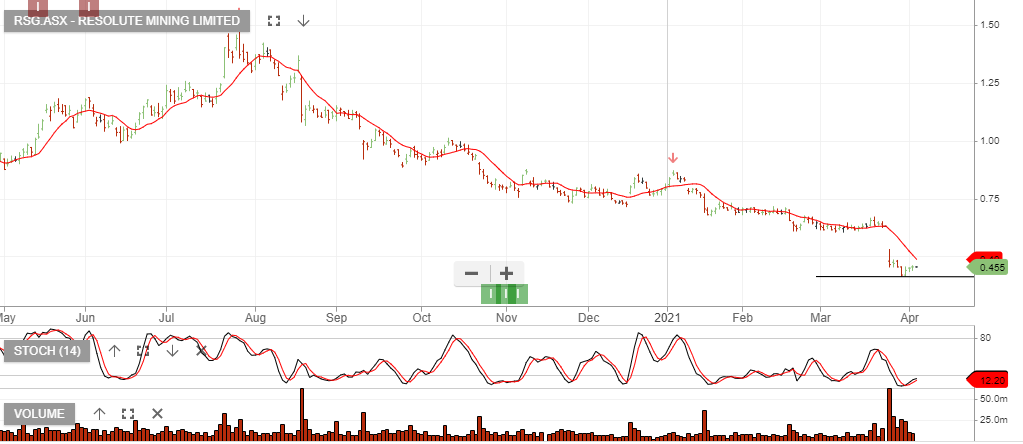
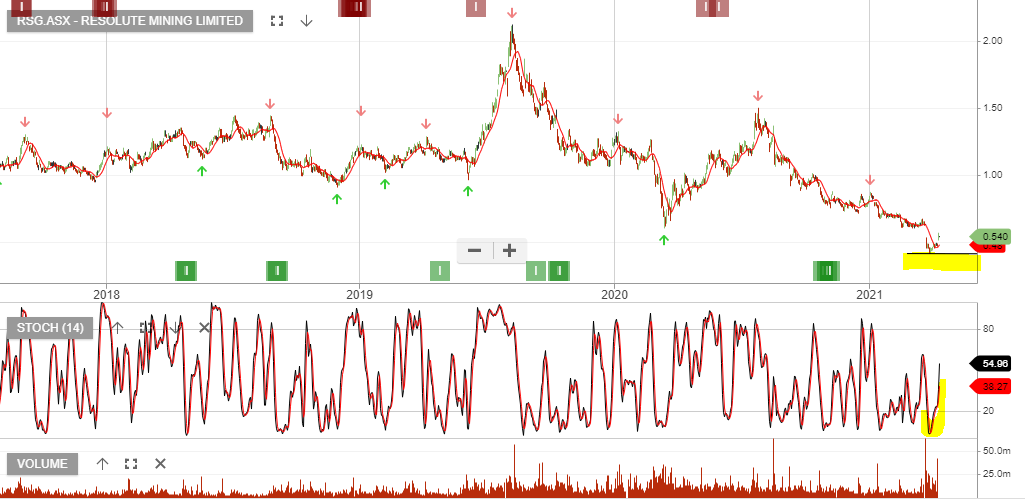
RSG:ASX is under Algo Engine buy conditions and is a high-risk recovery opportunity.
RSG enters our radar, supported by a positive back drop for gold prices and the recent announcement that the Mali mine is now projected to produce between 250,000 to 300,000 ounces of gold.
15/4/21
Since writing the above post RSG has rallied 30%. The company has announced that Bibiani’s mining license has been restored.
Deleveraging of RSG’s balance sheet remains a priority and will be reliant on operational cash flows to achieve this.
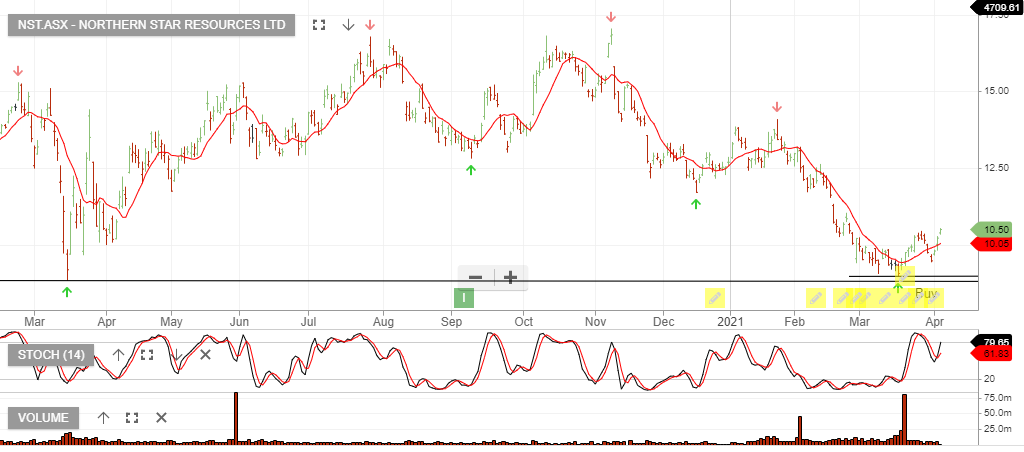
RSG is a high risk gold play, whereas NST and GOR offer less balance sheet risk.