The lesson from the GFC when it comes to REITS is to own the best-in-class and ensure gearing levels are moderate. 20 to 35% gearing is okay, 45 -50% gearing is the range that caused problems 10 years ago.
We like WFD combined with a tight covered call option which is delivering 10 – 12% cash flow on an annualised basis.
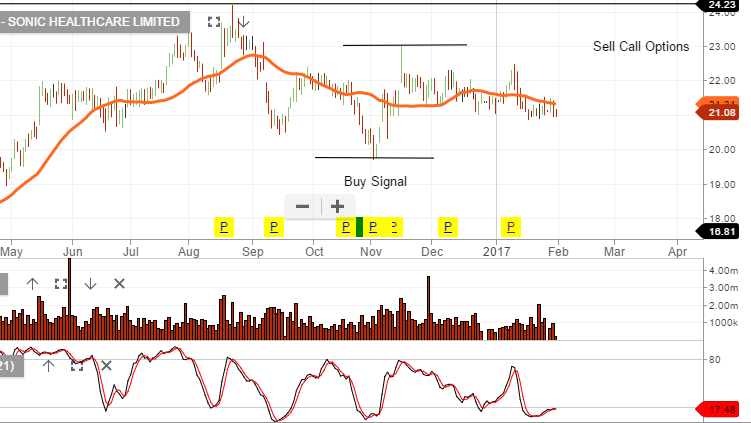
Sonic should grow earnings by 8% in FY17 and pay a 4% dividend yield. We’re buying this name and selling tight covered call options to enhance the income whilst allowing for moderate capital growth.
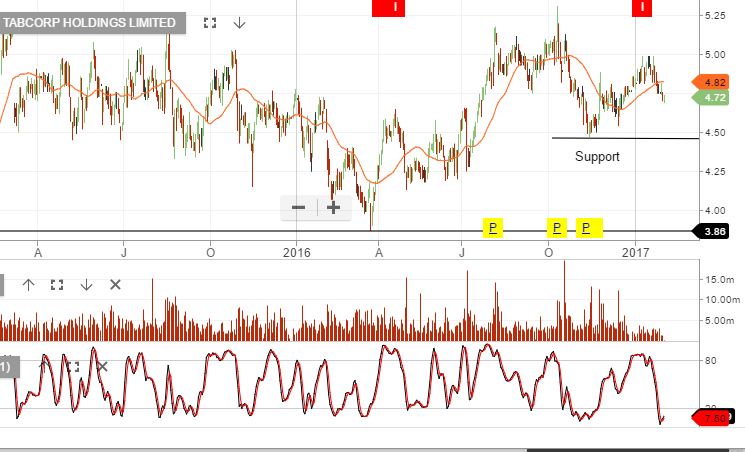
Tabcorp is a relatively defensive income opportunity for portfolios, with earnings supported by potential synergy savings after the Tatts integration.
The company continues to progress the merger proposal with Tatts and the ACCC is scheduled to release its statement of issues on the 23rd of February.
By applying a covered call option, we’re able to allow 5 – 10% capital growth from the current price, whilst still generating 10%+ in annualised cash flow from the dividend and call option income.
We expect modest earnings growth into FY18, which will place the stock on a forward yield of 5%. TAH goes ex-div on the 7th of Feb paying out $0.125
Our buy range for Tabcorp is between $4.20 & $4.50.
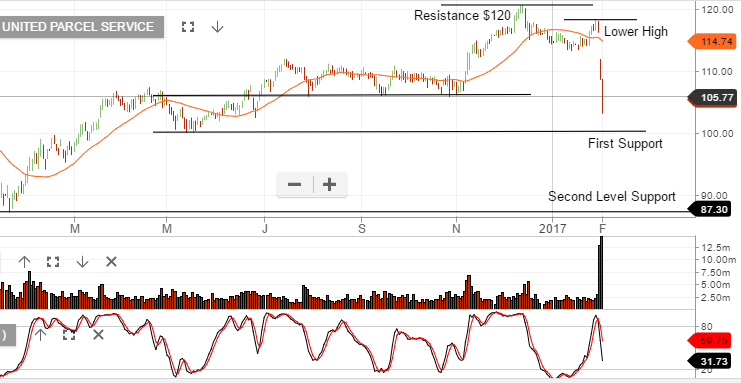
We’ve been watching the rollover pattern in GE and the recent break of price support in Goldman Sachs as potential leading indicators. We now add UPS and FedEx as two additional stocks of interest.
FedEx Corporation is expected to report earnings in March. The report will be for the fiscal quarter ending Feb 2017. The consensus EPS forecast for the quarter is $2.62 whereas, EPS for the same quarter last year was $2.51.
United Parcel Services, (UPS), reported quarterly earnings and revenue that missed Wall Street’s expectations. Fourth-quarter earnings of $1.63 per share on revenue $16.93 billion and weak 2017 guidance, ($5.80 to $6.10 per share), has resulted in heavy sell-side pressure in the stock.
A point of note: In 2016, UPS re-purchased 25.5 million shares for about $2.7 billion.
The graphs below show a concerning trend of downside risk.
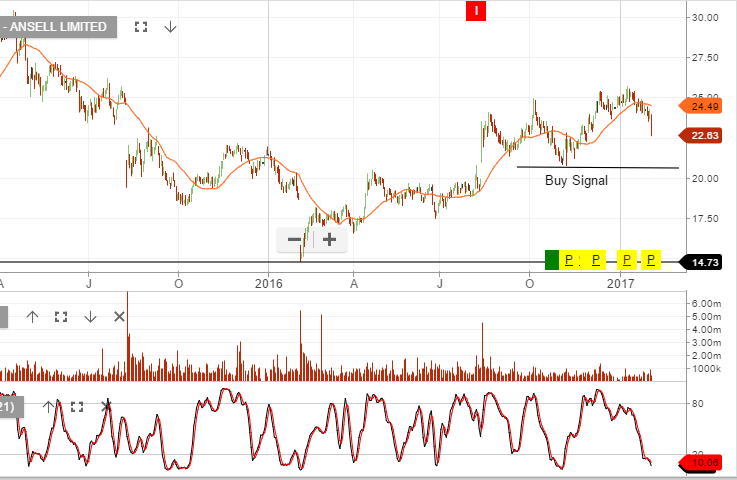
Ansell has purchased Nitritex, a UK-based manufacturer of premium clean-room and healthcare Life Sciences consumables. The deal is relatively small at US$60m and will be near-term earnings accretive.
The transaction adds to income generated outside the US and extends to the Ansell’s expertise across the Life Sciences segment.
We’re buyers of Ansell on the current price pullback. Value exists in the $22.50 – $23.50 range.
FY17 revenue $1.65b, EBITDA of $285m, net profit $170m, EPS $1.10 and DPS $0.46 places the stock on 2.5% forward yield.
We expect underlying business growth into FY18 and FY19 of 6% – 9%.
European economic growth for 2016 rose to 1.7%. Inflation is running at 1.8%, which is nearing the ECB’s target of 2% and the jobless rate fell to 9.6%; the lowest figure since May 2009.
This is the first time since 2008 that we’ve seen EU growth prospects tracking near the rate of the US. By any comparison, the economic recovery in G7 countries is still at very low levels and fragile global conditions remain.
Equity market valuations are stretched, and subdued revenue growth will likely lead to analysts’ EPS targets being reduced by 50% for 2017 to reflect actual current growth rates.
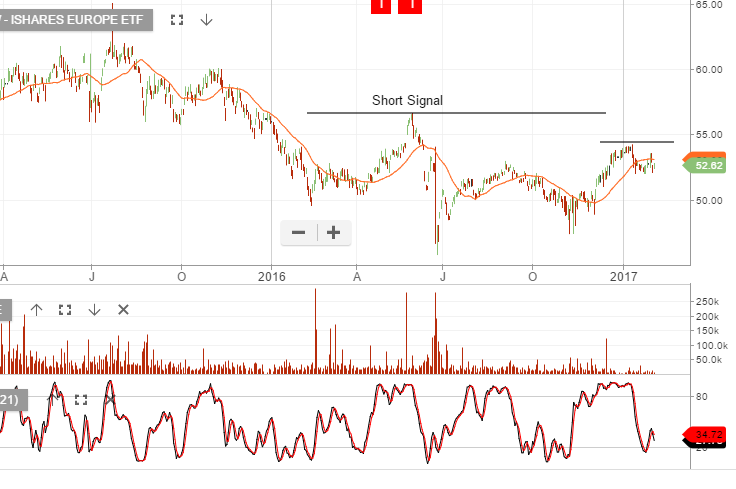
Our Algo Engine triggered a short signal in the iShares Europe ETF back in May at $55.75 and the index collapse by 18% within a few months following. Six months on and the index has recovered back to $52 and whilst we don’t have a new short signal present, we’re still cautious that another near term top is now in place.
SHL has strengthened its German footprint with the purchase of two laboratories from Medical Laboratory Bremen for A$90 million.
The deal is EPS accretive in the first year with margin expansion & synergy gains achievable in the near term. We expect Sonic to deliver 7 – 9% EPS growth in FY17 and FY18.
FY17 revenue $5.2b, on EBIT of $920m, Net Profit $$480m, EPS of $1.20 & DPS $0.78, places the stock on a forward yield of 3.6%.
We like Sonic as a core portfolio position, however the low yield and moderate EPS growth encourages the use of a covered call to enhance the cash flow and boost the overall investment return.
Chart – Sonic Healthcare
Sophisticated Investor?
We have special opportunities available for Sophisticated Investors. If you're interested, and qualify, please provide your details below.
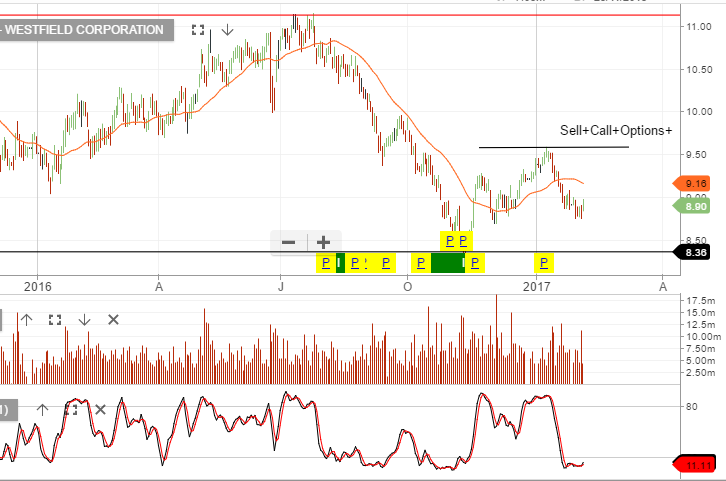
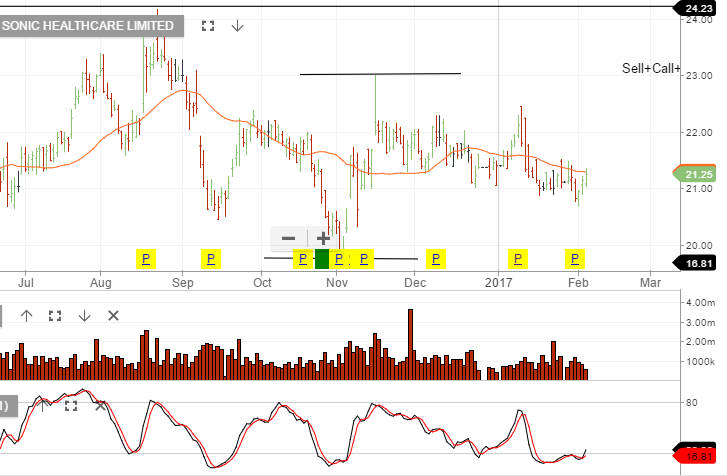
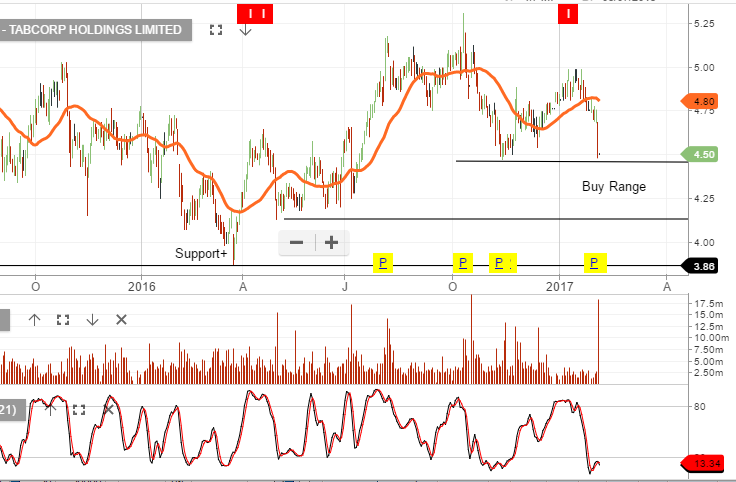
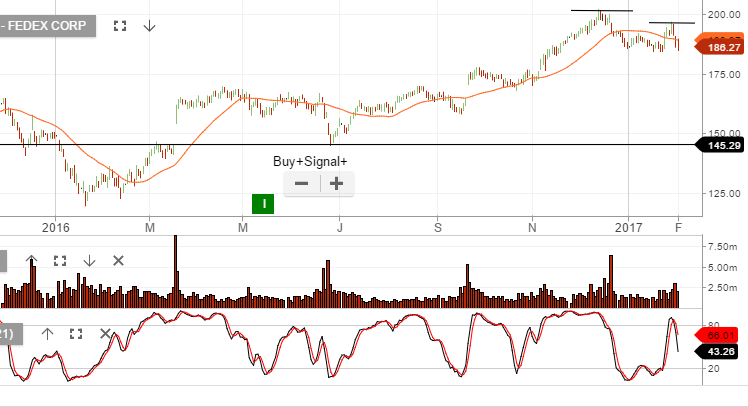 Chart – FedEx