REA Group – Algo Signal Update

REA Group has announced the sale of its European assets to Oakley Capital Private Equity for $190m. Profit on the sale is expected to be around $170m. REA Group should see earnings pickup into 2017 & 2018 with FY18 revenue likely to grow by 10% to $850m and EBIT by 15%+ to $420m.

FY17 DPS $0.90 and FY18 DPS $1.10, places the stock on a forward yield of 2.1%.

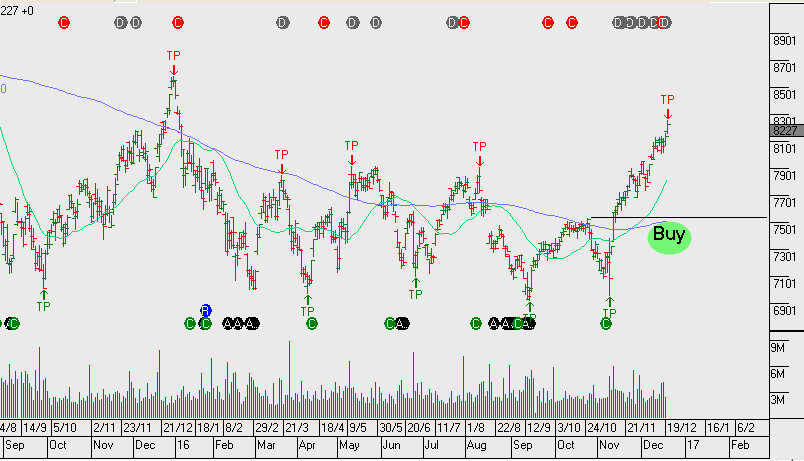
REA payout 50% of earnings and the dividend is fully franked. The recent algo buy signal at $46 provided a solid entry point. We recommend applying a stop-loss on a break below the November low of $45.50
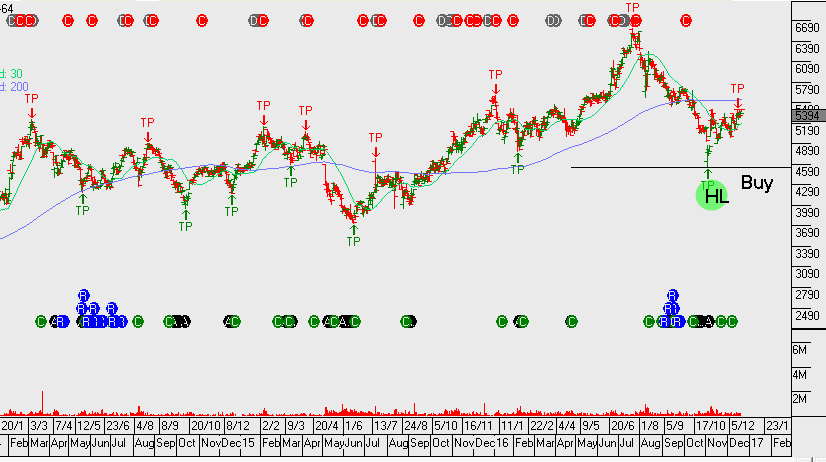
Chart - REA
Chart – REA


Commonwealth Bank – Visa Inc Sale

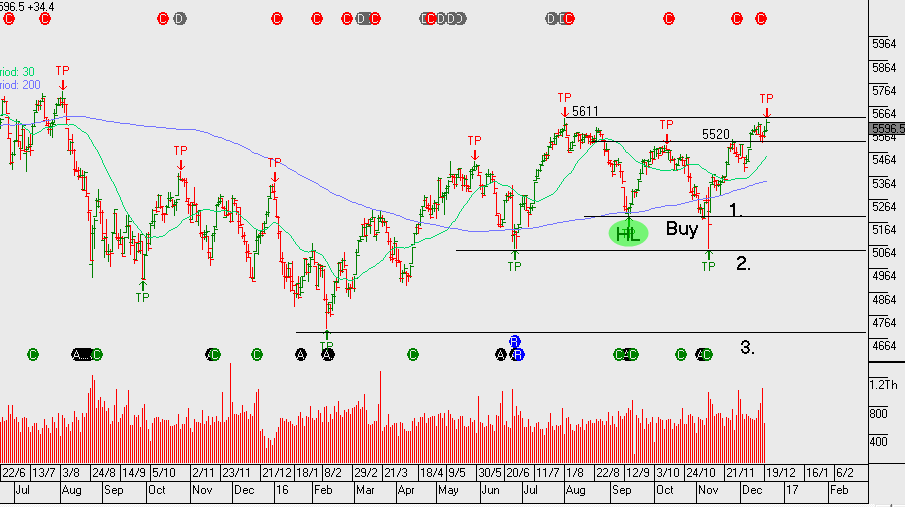
Shares of the Commonwealth Bank (CBA) posted a new high for the year at $82.65 as the bank announced it has sold its remaining stake in the US financial services company, Visa Inc.

The CBA sold its stake in Visa for A$439 million, realizing a post-tax profit of A$278 million. Against this profit, CBA has also announced a one-off accelerated amortization on certain capitalized software assets, totalling A$275 million.

While the accelerated amortization is more than offset by the profit on the sale of the bank’s Visa holdings, we see this move as reducing the potential for earnings uplift going into 2017. As such, heading into the February dividend, we see price resistance at or near the $83.00 level.


Chart - CBA
Chart – CBA


Crown Resorts – Update

Crown Resorts has announced several changes to their strategic business plan to simplify the business and enhance their balance sheet.

The firm has decided to cancel its Alon project in Las Vegas, sell off a major stake in its Macau casino business and cancel plans to spin off its international business.

The company will sell off almost half of its holdings in Melco Crown Entertainment for $1.6 billion, using the proceeds to cut debt, pay a special dividend of $500 million and enable a share buyback of around $300 million. Crown’s share of Melco’s annual net profit dropped by 60% in 2016 to $43 million following a corruption crackdown by Chinese authorities.

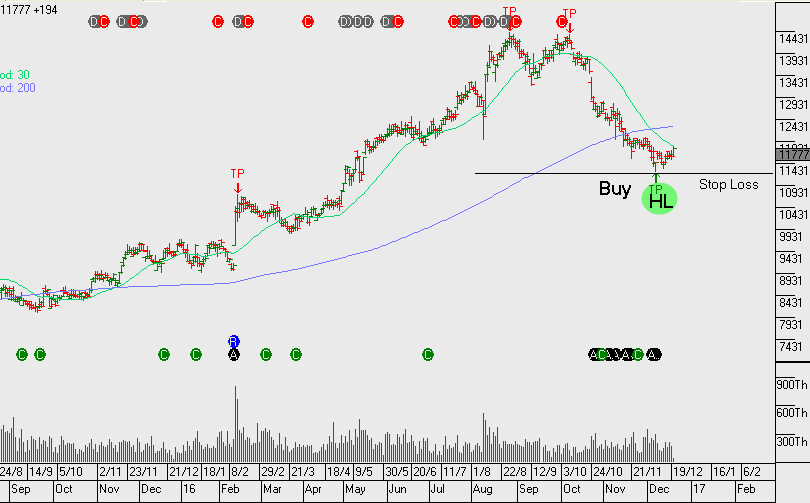
We still like the long side of CWN, although our upside target has been lowered from $14.00 to $12.50 following earnings revisions due to CWN’s reduced stake in Melco. CWN currently trades on 10x FY 17 estimated EBITDA and is on pace for a 5% yield for FY 2017.  

Chart - CWN
Chart – CWN

Caltex Trade Recommendation

Caltex delivered upbeat profit guidance following strong performances in Lytton and Marketing & Supply divisions. Fy17 revenue $16b, EBIT $900m on EPS of $2.30 and DPS of $1.20. This represent year on year underlying growth of around 10%.

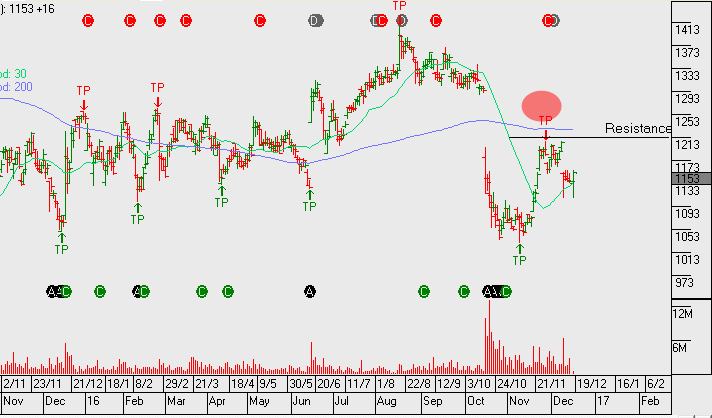
The chart below shows the market’s favourable reaction to the updated guidance with CTX rallying $1.40 from yesterday’s session lows. CTX trades on Fy17 PE of 13x and 4% dividend yield.

Here is our strategy recommendation on Caltex…

Buy CTX at market, sell May $32.50 call for $1.00 credit. March dividend will be $0.50+

Total return if exercised 13%+ in 5.5 months.

Chart - CTX
Chart – CTX

FED’s 25 basis point increase

The US Stock market slipped lower on the back of the Federal Open Market Committee’s (FOMC) policy announcement today. The market wasn’t surprised by the FED’s 25 basis point increase in the Overnight Fed Funds target, but the “Dot Plot” forward guidance shows policymakers are looking for 3 rate hikes of 25 basis points in 2017.

This view is more aggressive than the 50 basis point move the FOMC discussed back in September, which pushed equities lower and lifted the yield on the US 10-year treasury notes to a three year high of 2.57%. It’s worth noting that the 10-year yield traded at 1.35% in July; which means the yield on the US benchmark treasury note has essentially doubled in less than 5 months.

In her post-announcement press conference, FED chief, Janet Yellen, described the move as a “very modest adjustment”, which suggests this year’s forward guidance may mean another move on rates as early as May 2017.

We don’t see this a trend-changer in the major US stock indexes. However, we do see scope for a near-term correction back to the 19,450 level in the DOW Jones 30 and a move back to 2190 in the SP 500.  

Chart - Dow Jones
Chart – Dow Jones

Dow Jones 30 Review

This is a 5 minute video looking at the buy and sell signals within the Dow Jones top 30 stocks.

Investor Signals now offers US stocks and we can work in partnership with you to build and manage a portfolio that captures both long and short trading signals.

email me leon@investorsignals.com if you’d like to discuss what we can do to help with your US portfolio exposure.

Wesfarmers – Limited Growth

Over the last four years, Wesfarmers’ share price has traded in an $8.00 range between $38.00 and $46.00. Although the diversified company has consistently paid out fully franked dividends and has been yielding around 5% over the past few years, the lack of share price appreciation has been a concern for longer-term shareholders.

While the Bunnings division of the company has been gaining market share with the demise of Masters, it seems the market rates Wesfarmers earnings lower reflecting a view that the Coles division faces increased competition from the discount chain, Aldi.

Wesfamers has also entered the UK hardware sector with the acquisition of Homebase January of this year, which has yet to show a similar level of success as the Bunnings division.

We don’t expect the limited upside of the share price to improve anytime soon and will continue to employ the covered call strategy on rallies up to the $43.00 area; collecting the franking credits, a dividend of over $2.00 per share and the option premium. Our strategy is helping to boost cash flow to 13%+ per annum

Chart - WES
Chart – WES