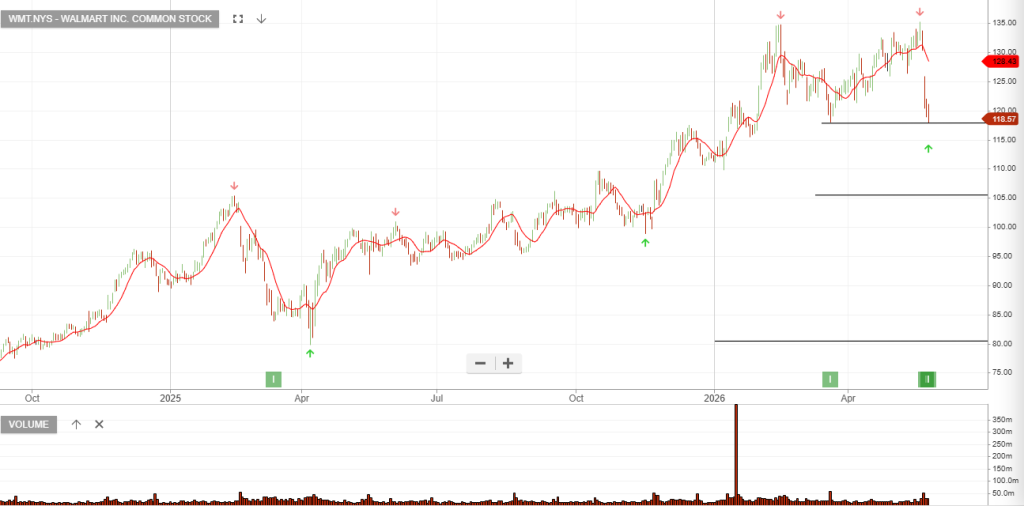
Hewlett Packard
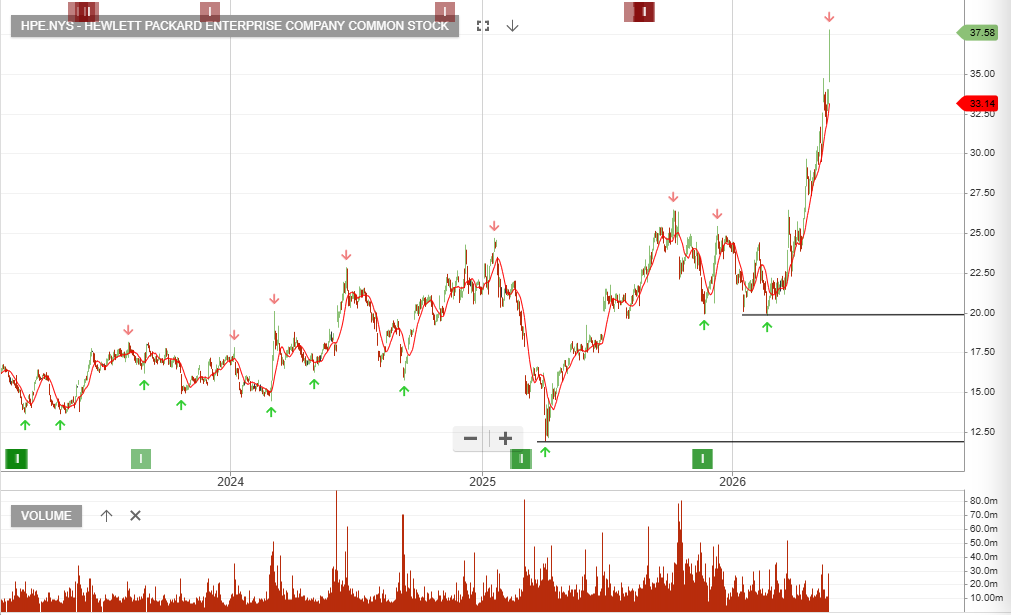
Hewlett Packard Enterprise Company Common posted a 40% year-over-year revenue jump to $10.68 billion, driven by massive demand for AI servers, prompting management to pull forward its long-term financial targets by two full years.

Hewlett Packard Enterprise Company Common posted a 40% year-over-year revenue jump to $10.68 billion, driven by massive demand for AI servers, prompting management to pull forward its long-term financial targets by two full years.
Nvidia CEO Jensen Huang, speaking onstage at Computex in Taipei, called the chipmaker the “next trillion-dollar company,” highlighting Marvell’s critical role in high-speed data center connectivity.
Next Earnings Date: Expected Date: August 20, 2026 (to August 27, 2026)
Following stellar bookings and AI demand, Marvell’s management has significantly upgraded its near-term and long-term revenue projections:
Upcoming Quarter (Q2 FY2027) Guidance: Expected Revenue: $2.70 billion (with a range of +/- 5%).
Growth Rate: Represents ~35% Year-over-Year (YoY) growth
Full-Year FY2027 Guidance: Expected Growth: Projected to grow ~40% YoY to nearly $11.5 billion (strongly upgraded from the previous 30% growth guidance).
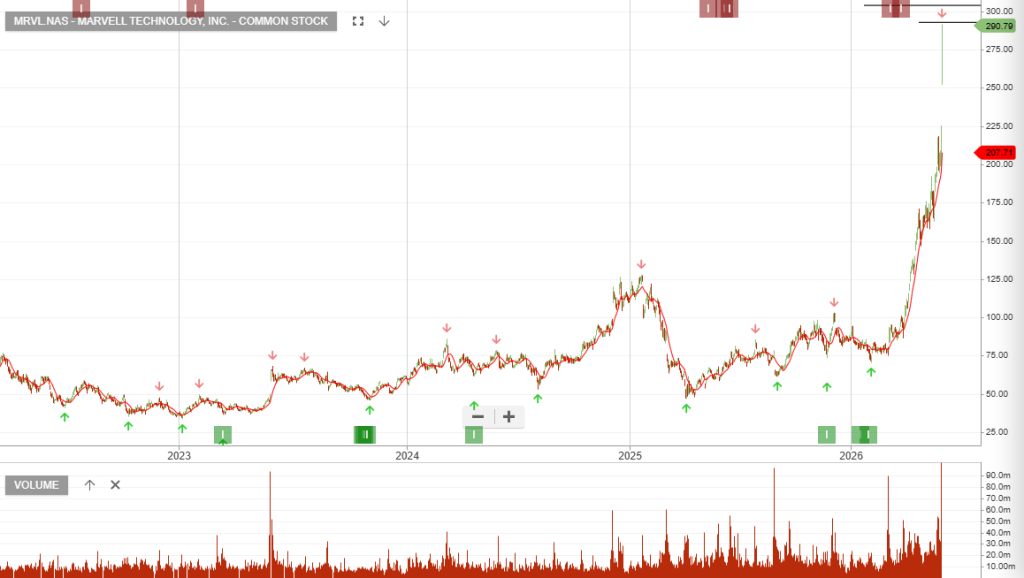
FY2028 Guidance: Expected Revenue: Upgraded to $16.5 billion (up from its prior guidance of $15.0 billion).
Expected Profit (EPS) Growth: Profit margins and earnings per share are scaling upward alongside high-margin datacenter optical and custom ASIC programs: Upcoming Quarter (Q2 FY2027) Guidance: Growth Rate: Represents an estimated ~35.8% YoY growth compared to the prior-year period.
Key Growth Drivers
Monday, June 1: Hewlett Packard and Credo Technology.
Tuesday, June 2: Palo Alto Networks and Ulta Beauty.
Wednesday, June 3: Broadcom, CrowdStrike, and Medtronic.
Thursday, June 4: Ciena Corp, lululemon athletica, and Docusign.
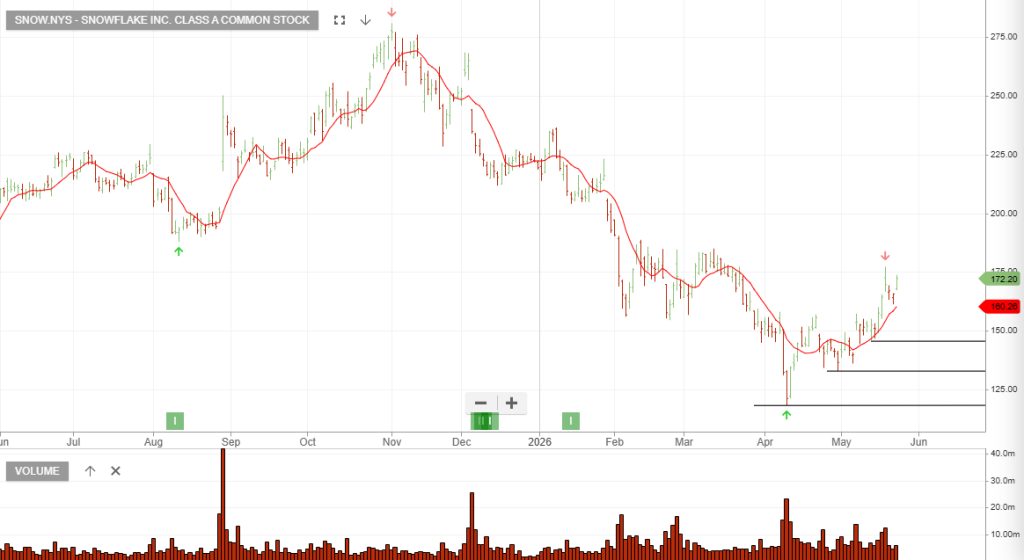
Snowflake Inc. Class A Commonis under Algo Engine buy conditions.
Shares of the data cloud provider exploded after a resounding Q1 earnings beat. Revenue rose 33% year-over-year to $1.39 billion (beating the $1.32 billion consensus), while adjusted EPS came in at $0.39 (vs. $0.32 expected). Sentiment was turbocharged by a massive, newly announced $6 billion five-year cloud infrastructure deal with Amazon Web Services (AWS) to scale generative AI and agentic applications. Management also raised its full-year product revenue guidance to $5.84 billion.
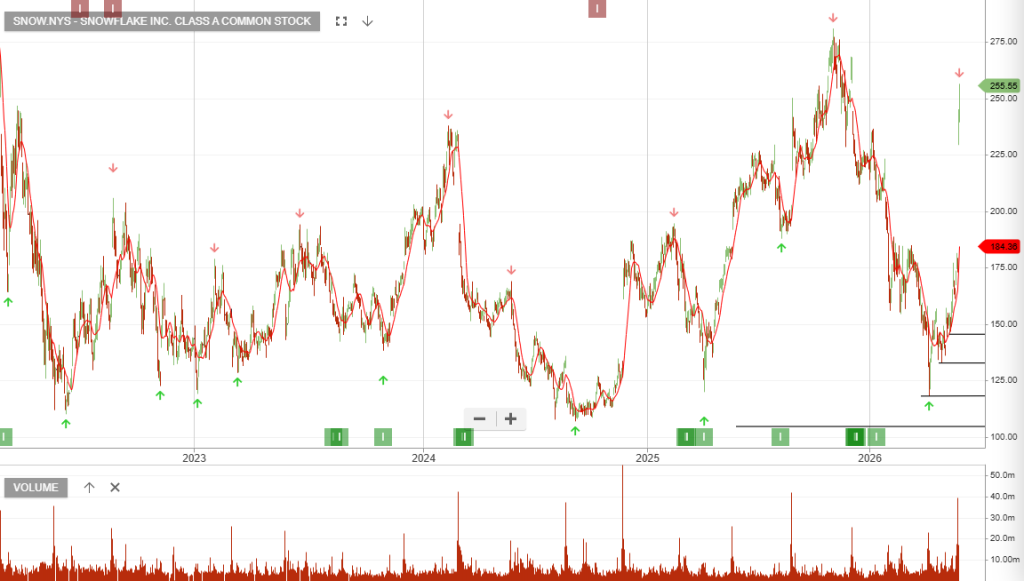
Buy
Despite delivering a strong “beat” on both top and bottom lines for the quarter, the stock tumbled in extended trading. This sell-off was primarily driven by mixed Q4 revenue guidance and near-term cautious commentary on hardware costs and sales team transitions.
Q3 FY2026 Financial Highlights (The “Beat”)
Snowflake Inc. Class A Common will report its Q1 Fiscal 2027 earnings this week on Wednesday, May 27, 2026, after market close.
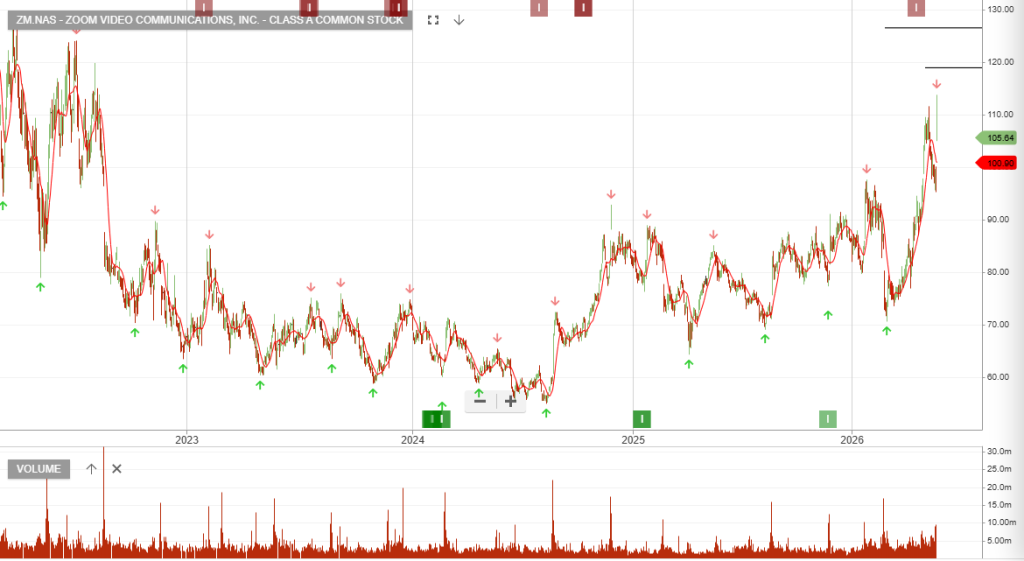
Zoom Video Communications, Inc. – Class A Common shares are higher following a highly impressive quarterly earnings report that significantly outpaced Wall Street projections.
Q1 Fiscal Year 2027 financial results (for the quarter ended April 30, 2026) on May 21, 2026.
The company delivered a double-beat on both top and bottom lines and raised its full-year guidance
Key Financial Highlights (Q1 FY27)
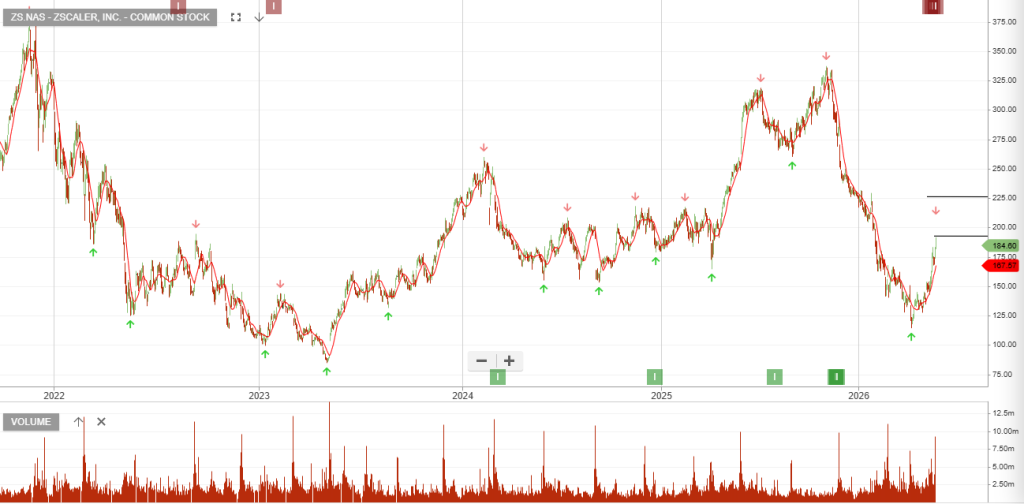
Hewlett Packard Enterprise Company Common is under Algo Engine buy conditions.
Upcoming Earnings Announcement: Q2 Fiscal 2026
* Expected Non-GAAP EPS: ~$0.51 to $0.55 (Consensus is around $0.54, representing a substantial year-over-year increase)
* Expected Revenue: ~$9.75B – $9.78B
HP shares have been buoyed by strong financial results from Lenovo Group, HP soared over 15.0%, and Dell surged to a fresh historic record high as investors preemptively positioned ahead of earnings next week.
Latest Reported Earnings: Q1 Fiscal 2026 (Reported March 9, 2026)
HPE delivered a highly profitable first quarter, notably beating profitability and cash flow expectations, driven by strong networking demand and early synergy capture from the Juniper Networks integration:
Key Segment & Business Highlights
Raised Fiscal Year 2026 Outlook
On the back of the Q1 results, HPE management raised its outlook for the full fiscal year:

Level 17 Chifley Tower
2 Chifley Square
Sydney, NSW 2000
1300 614 002
Investor Signals Pty Ltd
ABN 44 143 555 453