Pfizer Inc.
Pfizer, Inc. Common is under Algo Engine buy conditions.
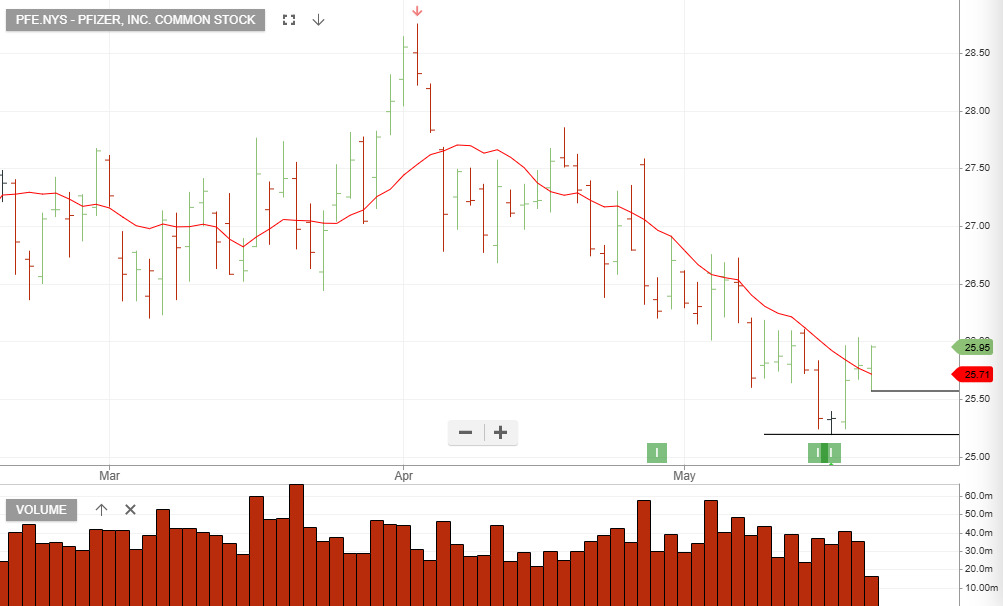
Pfizer, Inc. Common is under Algo Engine buy conditions.
Mining – Best positioned: RIO, FMG, WHC and NHC.
Rio Tinto (RIO) should benefit from improved mining productivity and fewer weather-related disruptions during El Niño conditions, supporting stronger export volumes and margins. Over the next 1–3 years, additional growth from copper and lithium projects also provides leverage to electrification and AI infrastructure demand.
Fortescue (FMG) is highly leveraged to operational efficiency in the Pilbara, where dry conditions improve haulage, port throughput, and mine uptime. Its low-cost iron ore position and longer-term green energy optionality support a constructive medium-term earnings outlook.
Whitehaven Coal (WHC) is positioned to benefit from stronger coal export reliability and sustained global energy demand, particularly in Asia. The acquisition of BHP’s coal assets materially expands production scale and free cash flow generation over the next several years.
New Hope (NHC) combines low-cost coal production with strong leverage to improved operating conditions during dry weather periods. Macquarie highlights NHC as one of its preferred El Niño beneficiaries with supportive earnings momentum and consensus upgrades.
Mineral Resources (MIN) has one of the strongest growth outlooks because it benefits from both mining services activity and commodity production. Dry conditions improve contractor utilisation and operational efficiency, while its lithium exposure adds upside if battery material markets recover
Largest Memory Suppliers
The memory industry is highly concentrated. Samsung, SK Hynix, and Micron collectively control roughly 70%+ of the global DRAM and NAND market.
Micron Technology (USA)
Micron has aggressively expanded US manufacturing and is one of the main Western alternatives to Korean memory suppliers.
Largest Suppliers of Advanced Semiconductor Nodes
These companies manufacture the most advanced logic chips (3nm, 2nm, AI accelerators, CPUs).
TSMC (Taiwan) — Clear Global Leader
TSMC dominates advanced-node manufacturing.
Intel Foundry (USA)
Intel is attempting a major comeback under its IDM 2.0 strategy.
Key goals:
Intel is pushing:
Intel still trails TSMC commercially but is strategically important because Western governments want alternatives to Asian supply concentration.
The AI stack effectively cannot scale without:
That trio is the backbone of modern AI compute infrastructure.
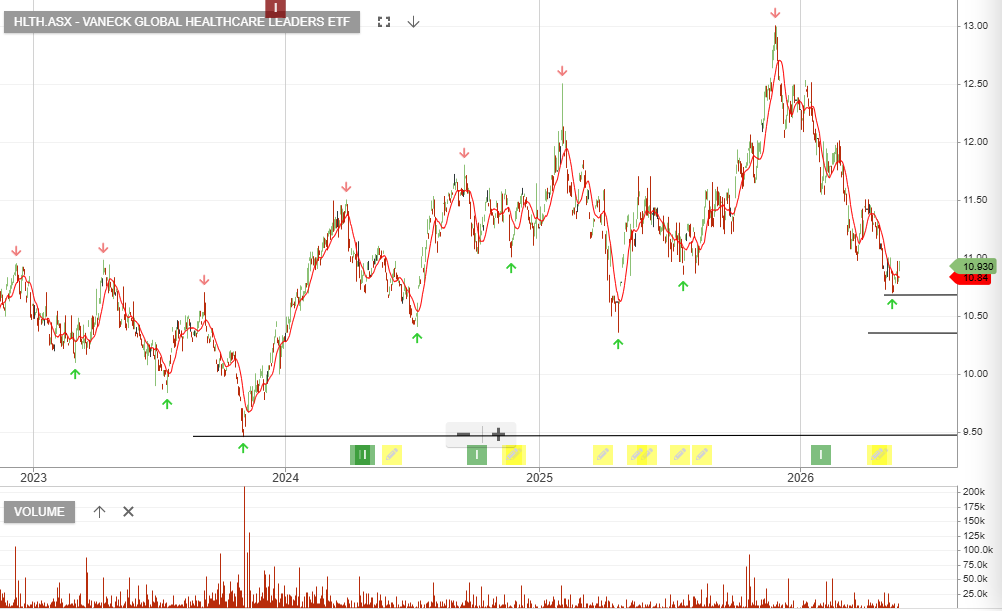
VanEck Global Healthcare Leaders is under Algo Engine buy conditions.
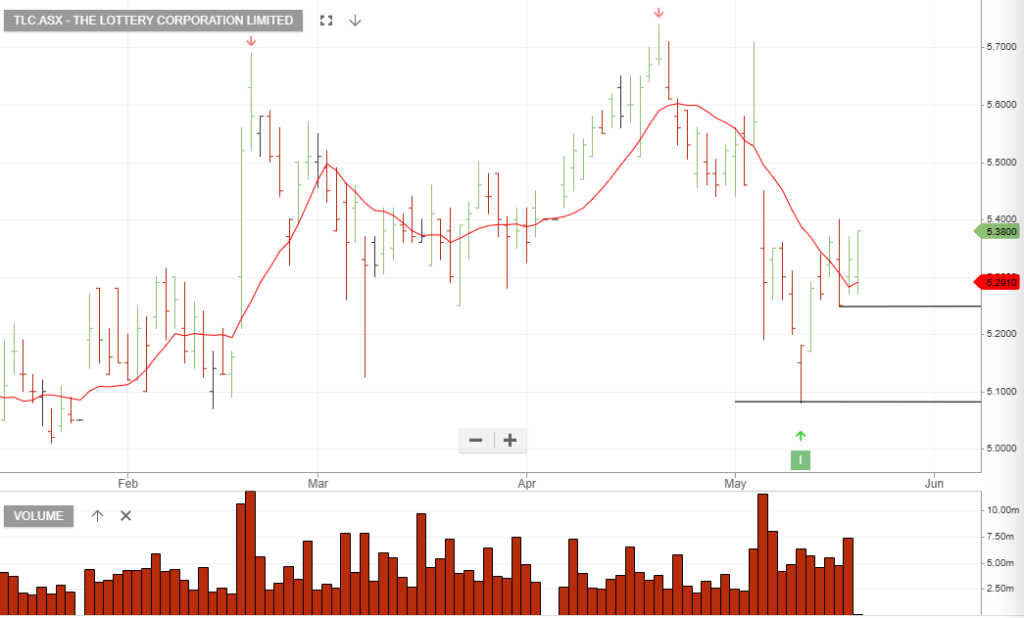
The Lottery Corporation is rated a buy, with the stop-loss at $5.25.
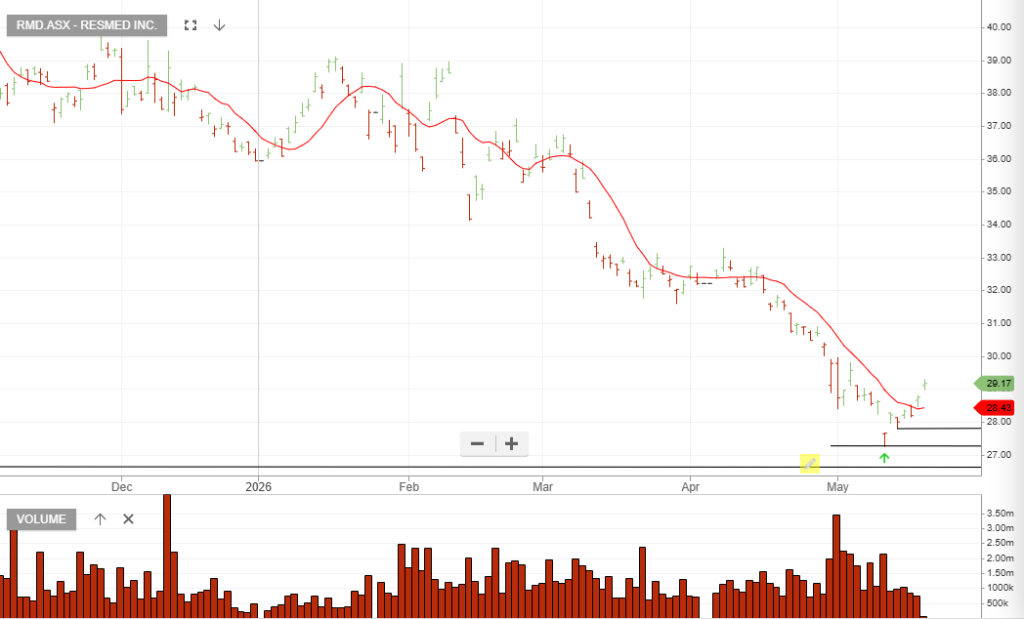
ResMed is rated a buy, with the stop-loss at $27.81
ARC:PIL This is an aggressive 3x-leveraged ETF offering top-5 exposure to a diverse mix of defensive value, hyper-growth mid-caps, and clinical-stage biotechnology plays.
Add to watchlist.
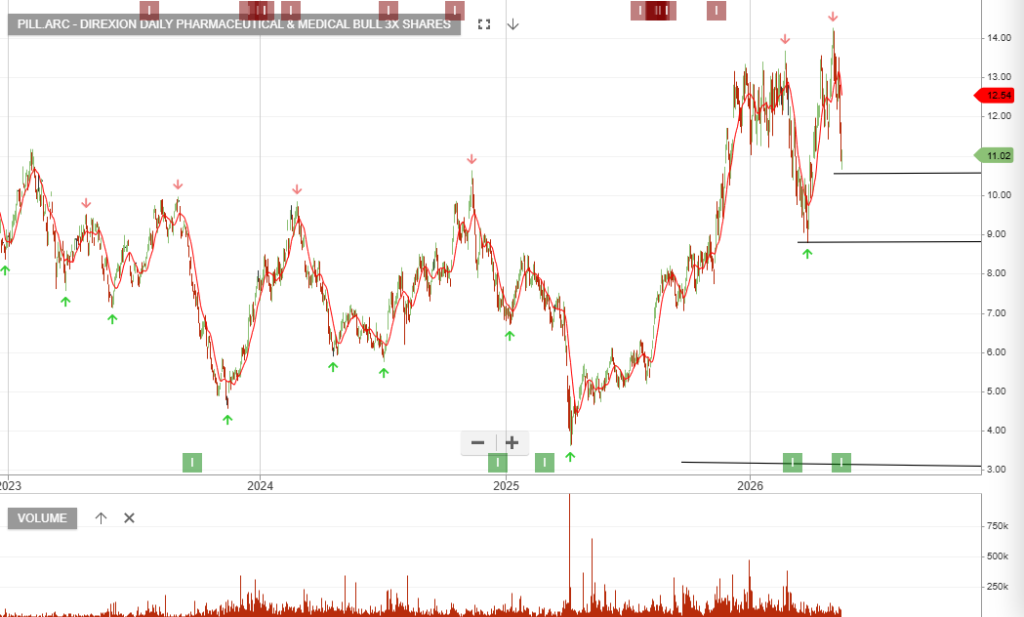
Danaher Corporation Common is under Algo Engine buy conditions.
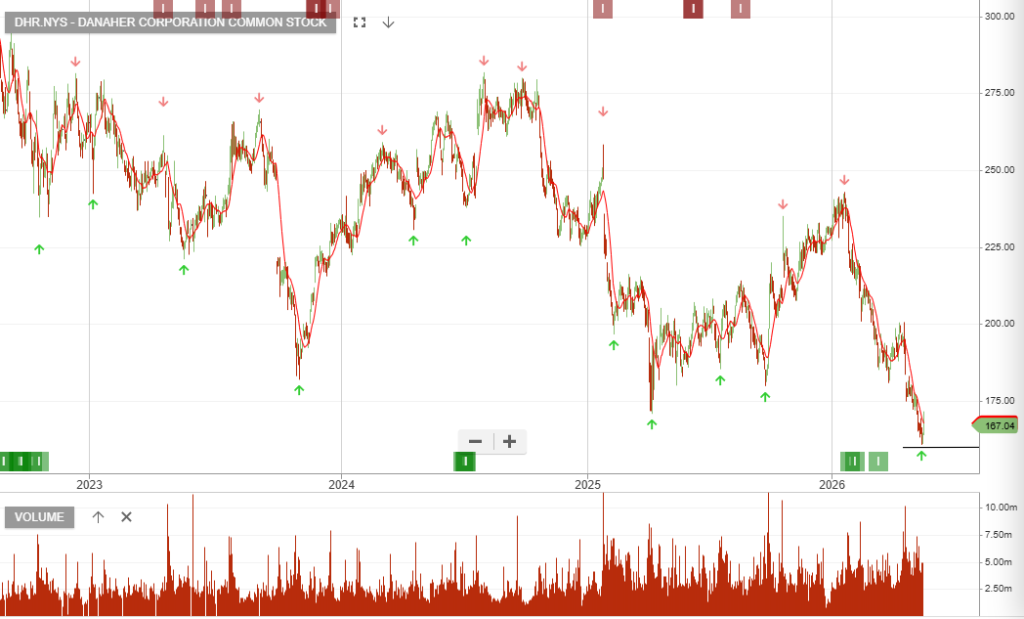
Share Price Correction & Valuation Opportunity
1–3 Year Earnings Growth Outlook
Upward EPS Momentum & Strategic M&A: Following strong Q1 execution, management raised its full-year 2026 adjusted EPS guidance to $8.35–$8.55. Looking out 2 to 3 years, earnings will be further amplified by the integration of Masimo Corporation (a $9.9B acquisition expected to close in H2 2026), where Danaher plans to rapidly scale margins using its signature Danaher Business System (DBS).
Bioprocessing Cycle Rebound: Danaher is in the early stages of a multi-year bioprocessing equipment reinvestment cycle. In Q1 2026, equipment orders surged over 30% year-over-year; as these orders convert to revenue over the next 12 to 36 months, they will drive highly profitable, recurring consumables sales.
Consensus 3-Year Outlook
Steady Compounder: Wall Street consensus model forecasts project a long-term normalized annual revenue growth rate of ~5.5% over the next 1 to 3 years as the life sciences sector fully transitions out of its post-pandemic digestion phase
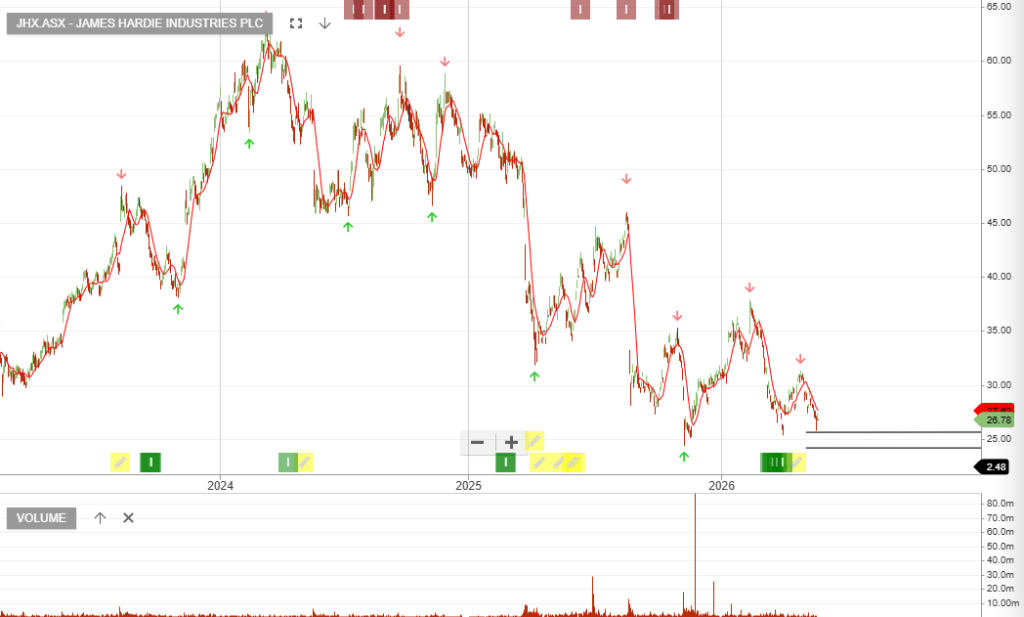
James Hardie Industries is under Algo Engine buy conditions.
Full-Year FY26 Results – The building materials giant reported its FY26 full-year results this morning, beating underlying earnings guidance despite facing a challenging global macro environment.
Dividends: No dividend was declared or paid for the year.
Full-Year Net Sales: US$4.84 billion, up 25% (boosted by the AZEK acquisition). Siding & Trim organic sales decreased 2%. Statutory Net Profit: US$104.0 million, down 75% year-on-year, weighed down by restructuring charges, asbestos compensation claims, and AZEK integration costs. Adjusted EBITDA: US$1.27 billion, up 17%, exceeding the company’s prior guidance.
Outlook: For FY27, management targets pro forma Adjusted EBITDA growth of 4% to 8% (US$1.45–$1.50 billion) and free cash flow of at least US$500 million.
Sorry, but this content is restricted to our members.
Please login with your account or register for a free trial. If your trial has expired, then you may renew it here.
If you are having an issue with your account, then please get in touch with us.

Level 17 Chifley Tower
2 Chifley Square
Sydney, NSW 2000
1300 614 002
Investor Signals Pty Ltd
ABN 44 143 555 453