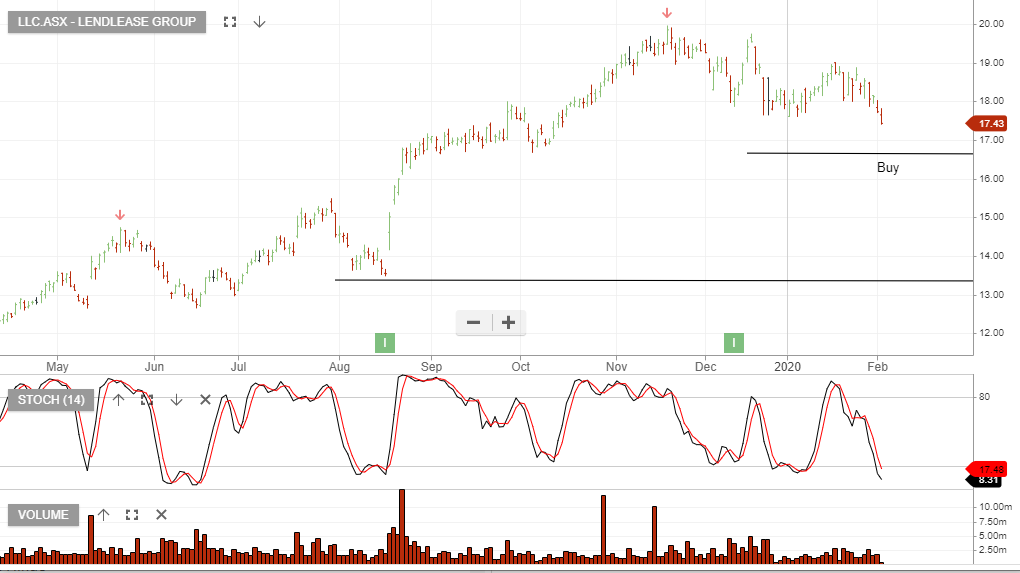
Newcrest – Finding Support
Newcrest Mining is under Algo Engine buy conditions and is a current holding in ASX 100 model portfolio.
We see upside potential to $32.00.
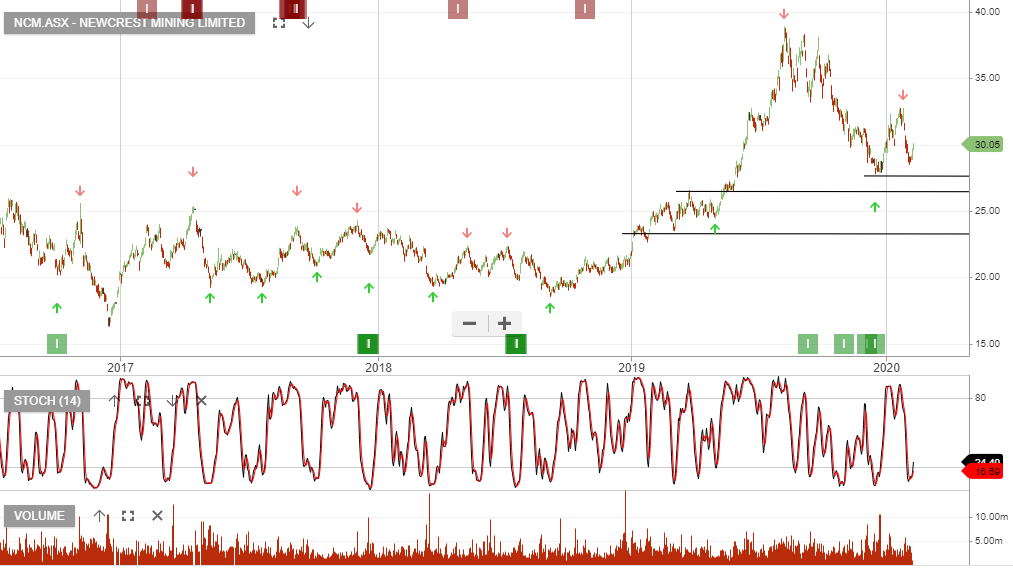
Newcrest Mining is under Algo Engine buy conditions and is a current holding in ASX 100 model portfolio.
We see upside potential to $32.00.
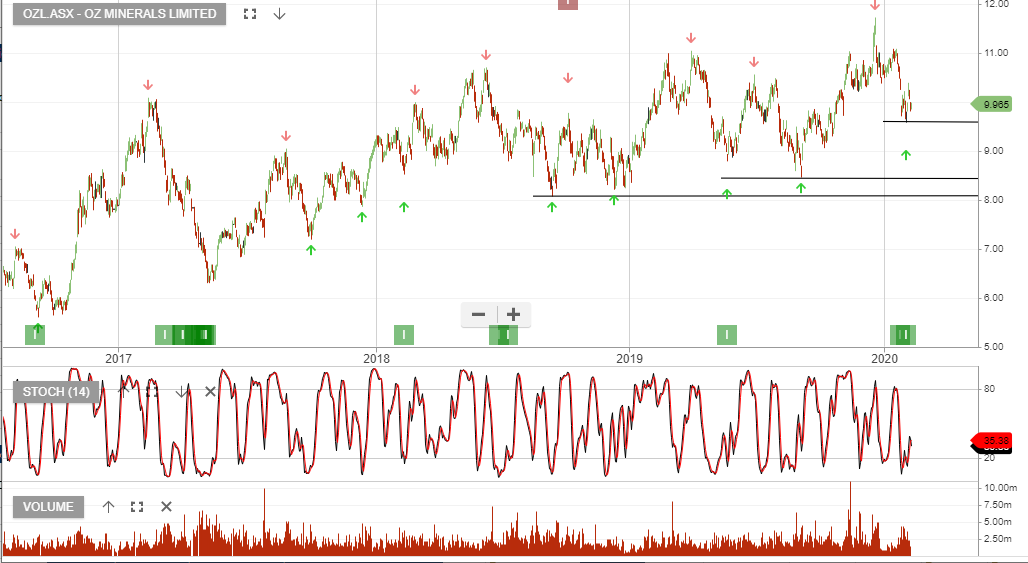
OZ Minerals is under Algo Engine buy conditions and is a current holding in ASX 100 model portfolio.
We see value at $9.90
Aurizon Holdings reported 1H20 earnings which were mostly in-line with market forecasts.
1H20 EBIT of $456 million with underlying EPS of $0.136cps. The company continues to payout 100% of earnings in dividends.
Full-year 2020 EBIT guidance remains unchanged at $880m – $930m and the share buy-back program has increased to $400m in FY20.
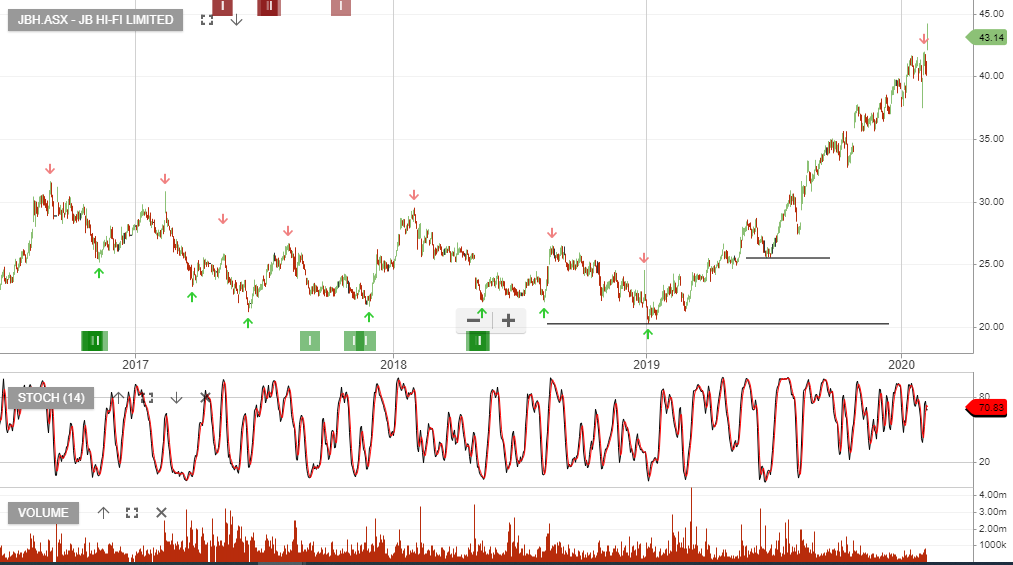
JB Hi-Fi delivered 1H20 NPAT of $174m, which represents 9% growth vs the same time last year.
JB Hi-Fi issued FY20 NPAT guidance of $265 to $270 million, which implies 1.0% to 6% growth, slightly below market consensus.
Alacer Gold provides an interesting growth opportunity. The company holds a significant portfolio of highly prospective exploration land holdings across Turkey (totaling approximately 125,000 hectares), some of which are progressively advancing to prospective projects.
The release of the CY19 financials show NPAT beat on a one-off tax adjustment, whilst revenue was in line. EBIT of US$171m was also broadly in line with market expectations.
The company has recent exploration success at Çakmaktepe & Ardich sites. We see scope for a material pickup in earnings from FY21.
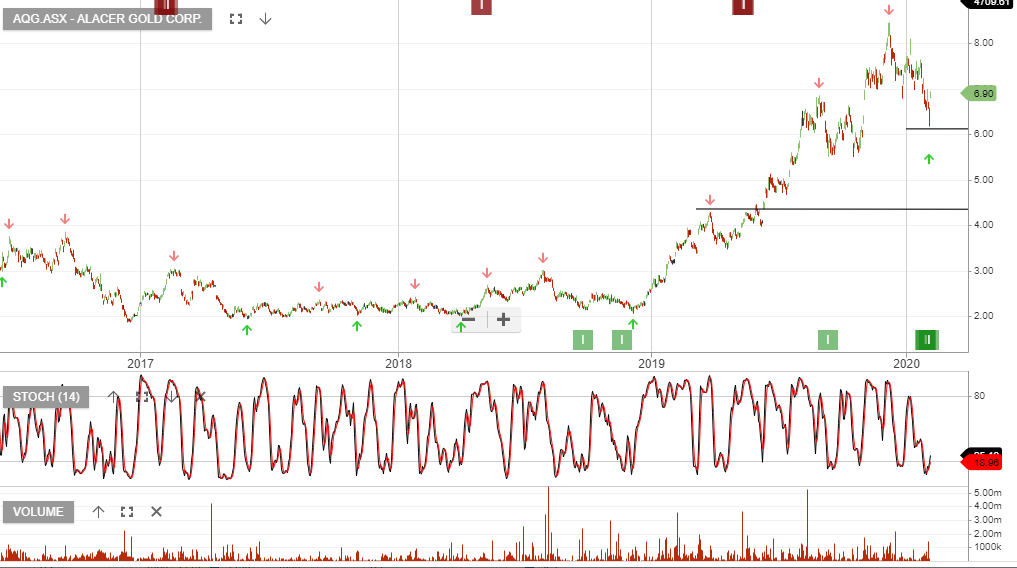
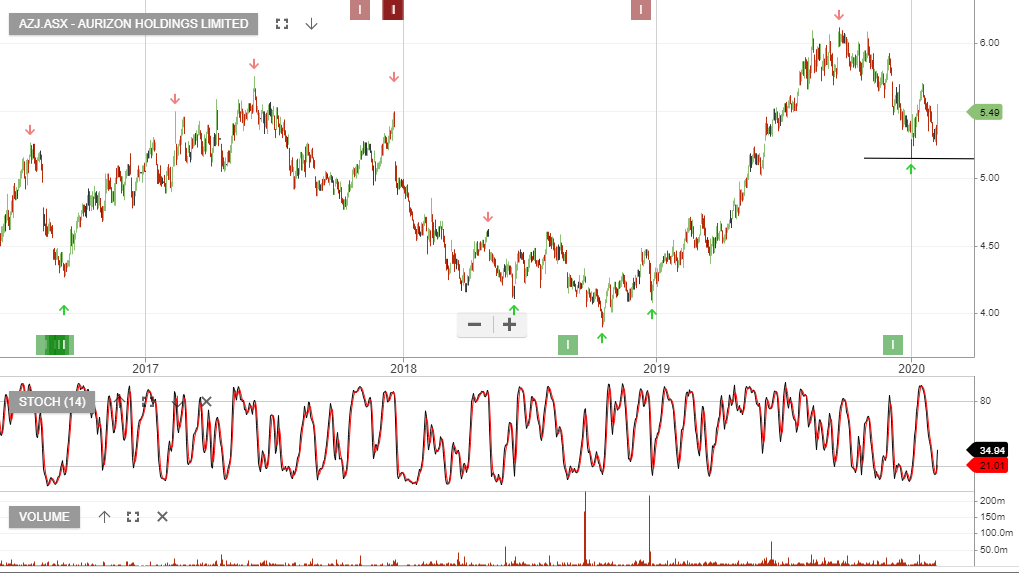
Aurizon Holdings is under Algo Engine buy conditions.
The share price is supported by a combination of the ongoing share buyback program and 100% dividend payout, which places the stock on a forward yield of 4.9%.
AZJ goes ex-div $0.115 on the 25th Feb. Adding a $5.75 June call option boosts the annualized cash flow to 10%.
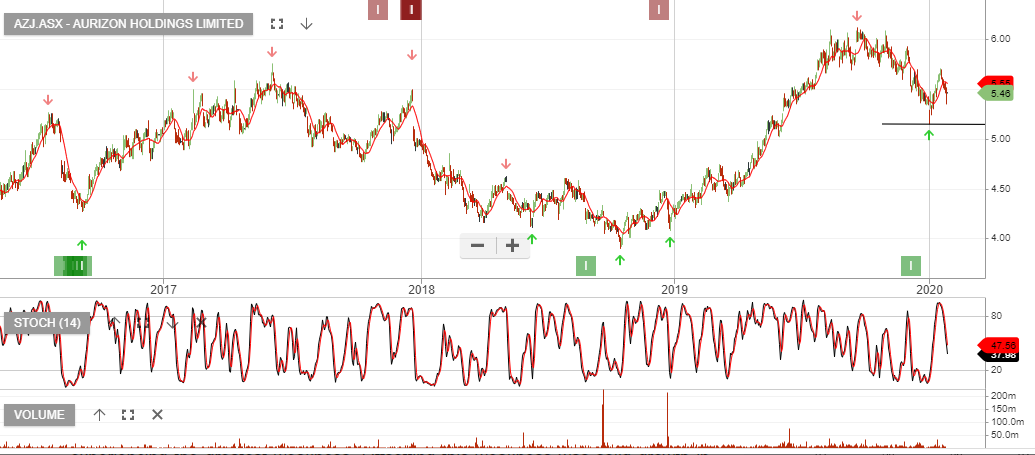
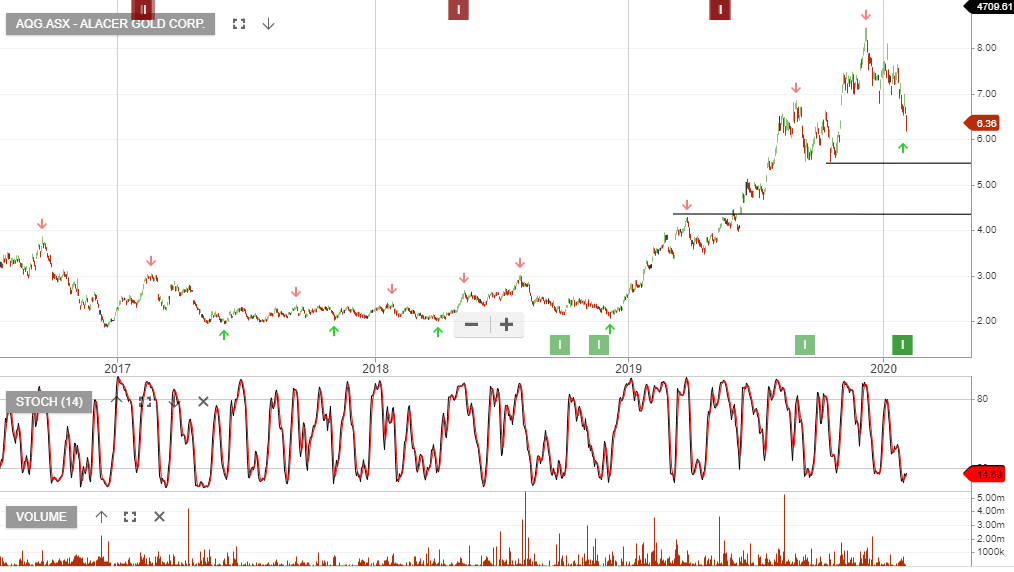
Alacer Gold is under Algo Engine buy conditions and we see value at $5.50. If gold remains under pressure in the next few trading sessions we may see AQG at our entry target.
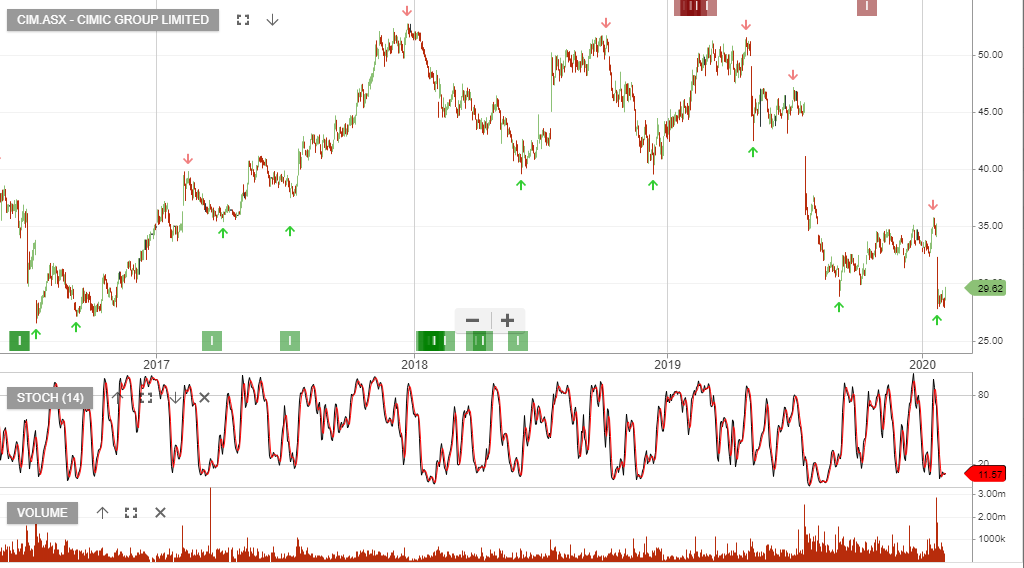
We continue to see long-term value in CIMIC, supported by structural tailwinds within the infrastructure sector. The company recently announced they’re writing off 1.8bn and exiting their Middle East business to focus on Aust, NZ, and Asia.
Yesterday’s profit release was in line with guidance at $800m of underlying NPAT. FY20 is forecast to see between 1 – 6% growth and a new guidance range of $810-850m has been provided.
Dividends are expected to resume in FY20 and investors should be positive on the strong Q4 cash flow. CIM is trading on 11x forward earnings and a forward dividend yield of almost 6%.
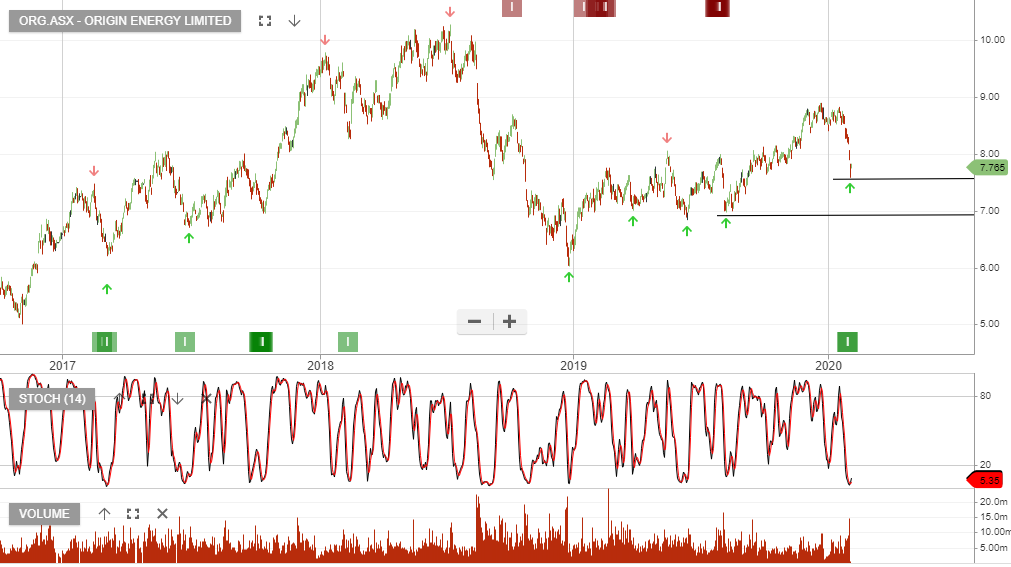
Chinese energy importers are considering force majeure declarations as the short-term demand for energy is impacted by recent events.
A combination of weaker demand and lower prices sets up an opportunity for investors. Our preference is ORG & BHP and investors should average into any exposure by controlling the position size.
It’s still possible that a second wave of Coronavirus impact may materialize and markets may once again be under pressure.

Level 17 Chifley Tower
2 Chifley Square
Sydney, NSW 2000
1300 614 002
Investor Signals Pty Ltd
ABN 44 143 555 453