Scentre Group – Algo Update

Scentre is under Algo Engine buy conditions and is a current holding in our ASX 100 model portfolio.

SCG is likely to generate low levels of earnings growth, however, the weak backdrop for global bond yields and the share buyback program that Scentre Group is running, are catalysts to support our “buy” rating.


BHP – Buy

BHP Group is under Algo Engine buy conditions and is a current holding in our ASX 100 model portfolio.

BHP outlined earlier this week its outlook for the Petroleum business, which includes an increase in capital spending and plans to double production by 2025.

FY21 revenue remains flat, EBIT the same as FY20 at $19bn, which supports DPS of $1.55 per share placing the stock on a forward yield of 5%.

The market is negative on the outlook for Iron Ore prices, with extra supply hitting the market in 2021, however, if spot prices stay where they are analysts will have to upgrade the earnings outlook. 10 to 20% upgrade in earnings will support BHP trading back over $40 per share.
 

Coles – Valuation Review

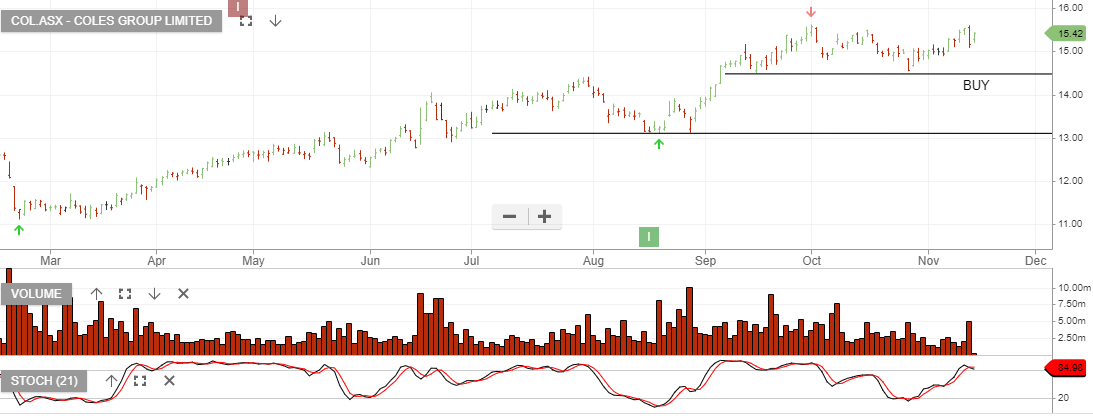
Coles Group is under Algo Engine buy conditions and is a current holding in the ASX 100 model portfolio.

1Q sales results are tracking in line with guidance and we continue to see a relatively flat revenue and profit growth outlook for the Coles business.

FY20 revenue $39bn, EBIT $1.2bn and reported profit forecast is around $830mn. This places the stock on a forward yield of 3.2%, which looks like full value.

Adding an out-of-the-money covered call will help boost the cash flow returns to almost 10% per annum. For more detail on the strategy, please call our office on 1300 614 002.


Coca-Cola – Buy

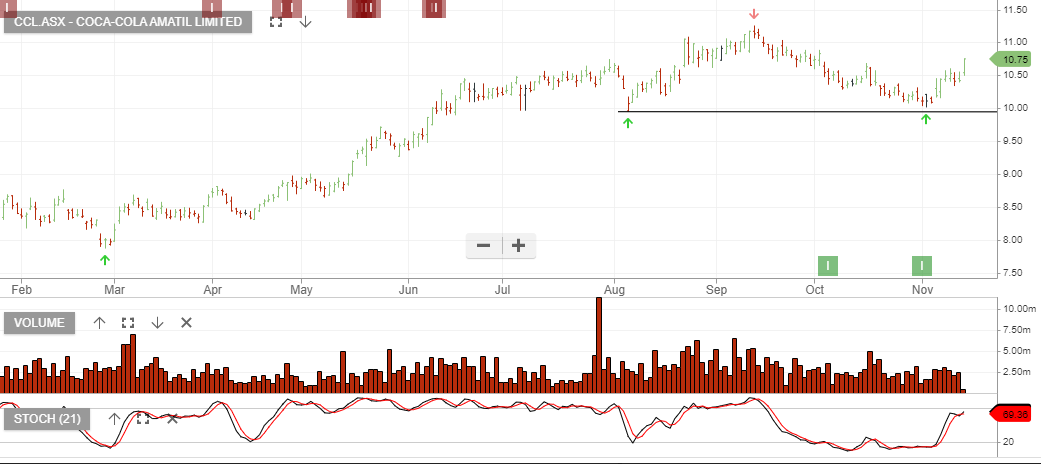
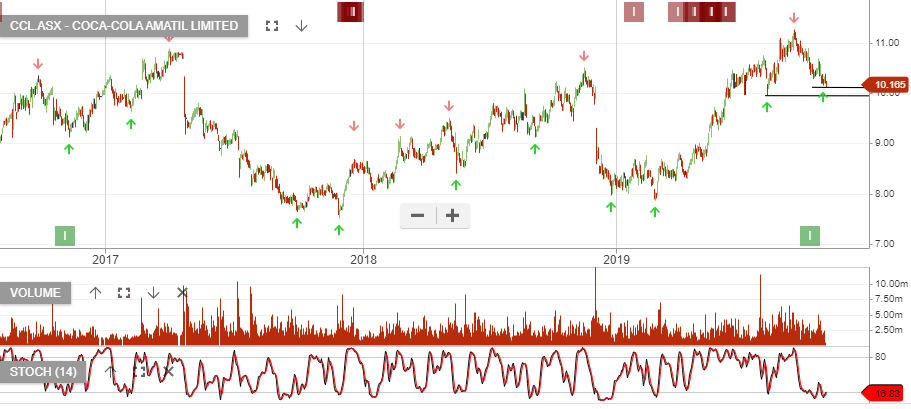
Coca-Cola Amatil is under Algo Engine buy conditions and is a current holding in our ASX 100 model portfolio.

We see price support developing near the $10 level, supported by 4 – 5% EPS growth and a 4.8% dividend yield.

Look for a move back towards $10.75 and then sell call options to enhance the income return. For more information on the derivative strategy, please call our office on 1300 614 002.


Rates Are Up & REITs Are down…

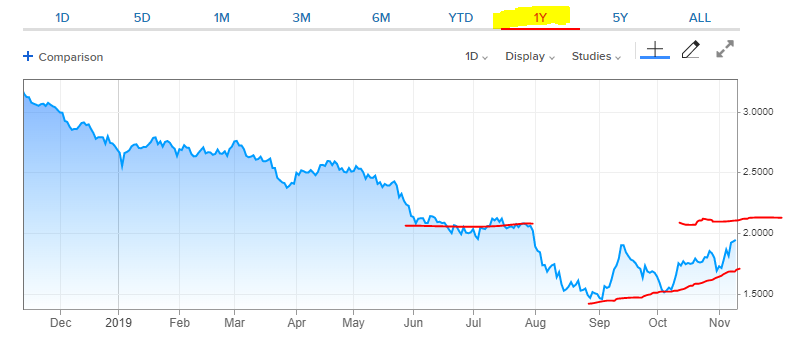
US Treasury yields have surged to the highest levels since late July, with the 10-year yield jumping to 1.945%.

The higher rates in the US bonds have seen domestic REITs move lower by an average of 5%, despite a generally better-than-expected earnings season.

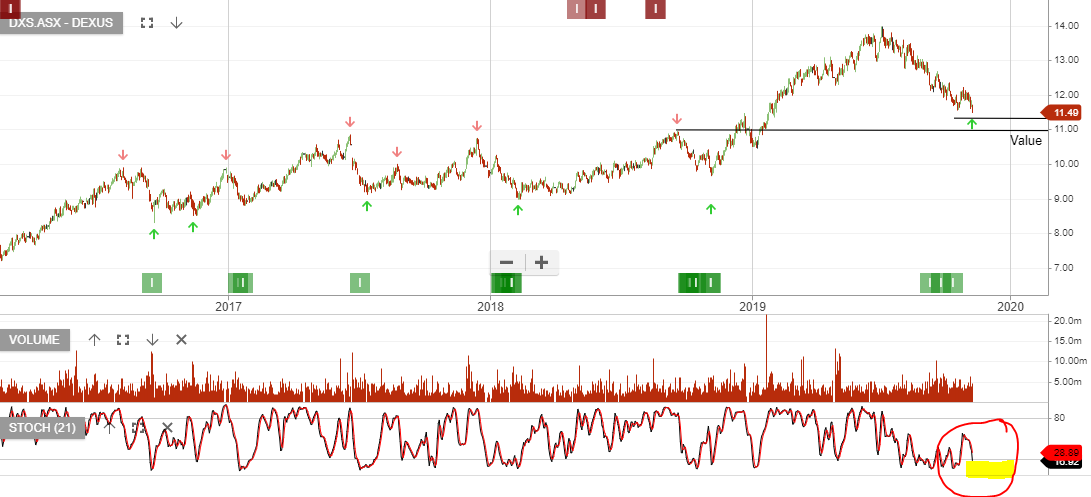
An opportunity will soon approach within a number of the yield sensitive names and investors should be watching out for oversold levels to present within REITs, infrastructure, utilities and gold names.

An example of a name we’re watching for a buying point is Dexus Group. We’ll update you on the blog as we see the buying point playout.


QBE – Algo Buy Conditions

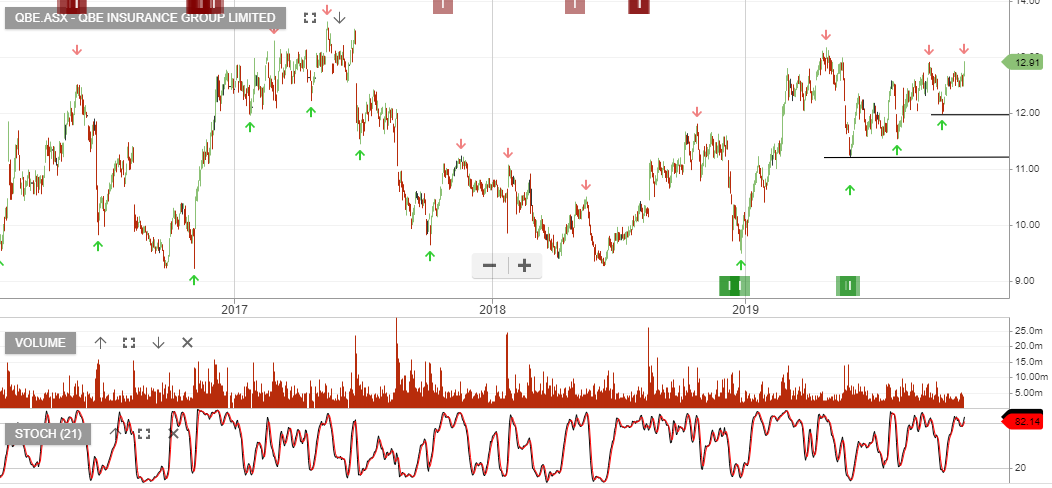
QBE Insurance Group is under Algo Engine buy conditions and is a current holding in our ASX 100 model portfolio.

Recent earnings update shows QBE delivering ahead of consensus. Growth should remain strong and upgrades to 2020 earnings are now likely. The balance sheet remains robust, with A$1bn buyback over three years being executed.

Higher yields in US treasuries are helping to lift investor sentiment towards QBE and financial stocks in general.

Buy QBE and look for a move into the $13.50 price range.

Northern Star – Buy Signal

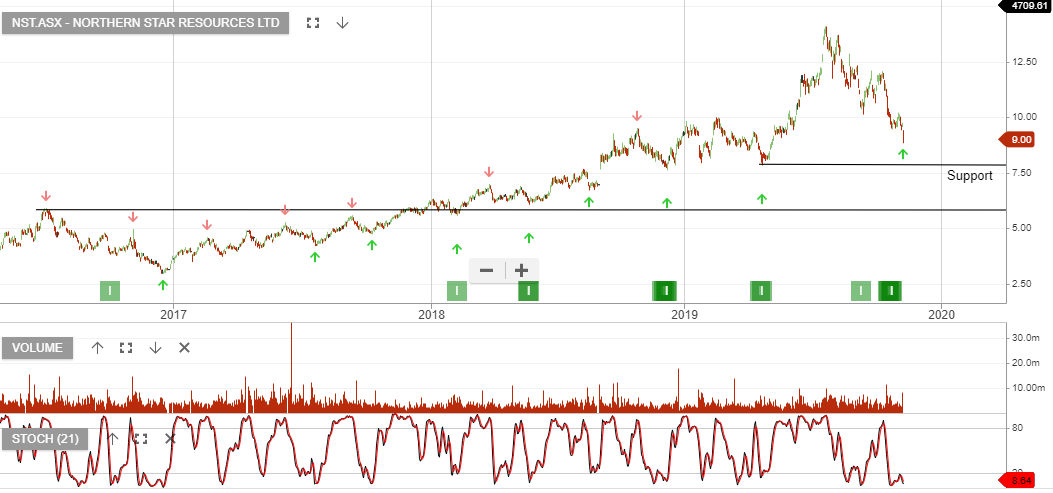
Northern Star Resources is under Algo Engine buy conditions and is a current holding in our US S&P100 model portfolio.

Gold remains under pressure as US yields push higher during the current “risk on” phase in the market. We are also experiencing selling in the “yield sensitive” securities such as consumer staples, utilities, infrastructure and REITs.

We now forecast price support developing in NST near $8.00.