Telstra Still Leads The Telco Pack

Shares of TLS have been in a basing pattern above the $3.00 level and there are solid fundamental reasons for accumulating shares in this current range.

Since the share price has slipped over 17% over the last 12 months, the current yield is now close to 10%, including the franking credits.

Mobile is the company’s biggest earner and its most important revenue stream. TLS added 235,00 net new retail customers in  H1 compared to 200,000 a year ago and only 18,000 in the June half of 2017.

A recent analyst research letter forecasts the continued dominance in the Telco space, as well as diversification into other data streams will lift the share price into the $4.60 area over the medium-term.

As such, we continue to favor the long side of TLS for value investors looking for growth and a solid dividend.
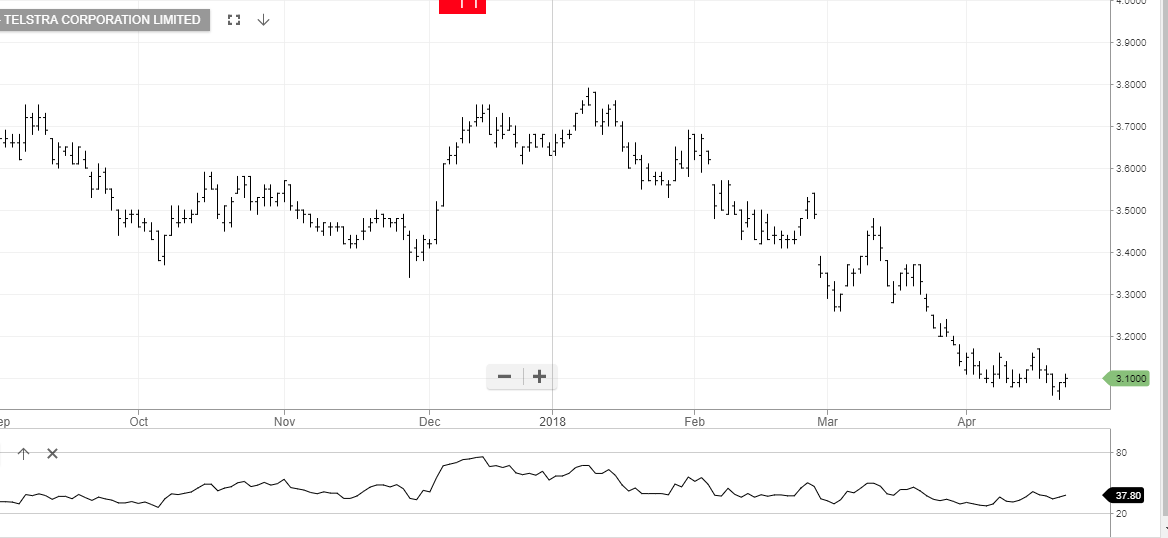
Telstra


Shares Of SGR Continue To Firm

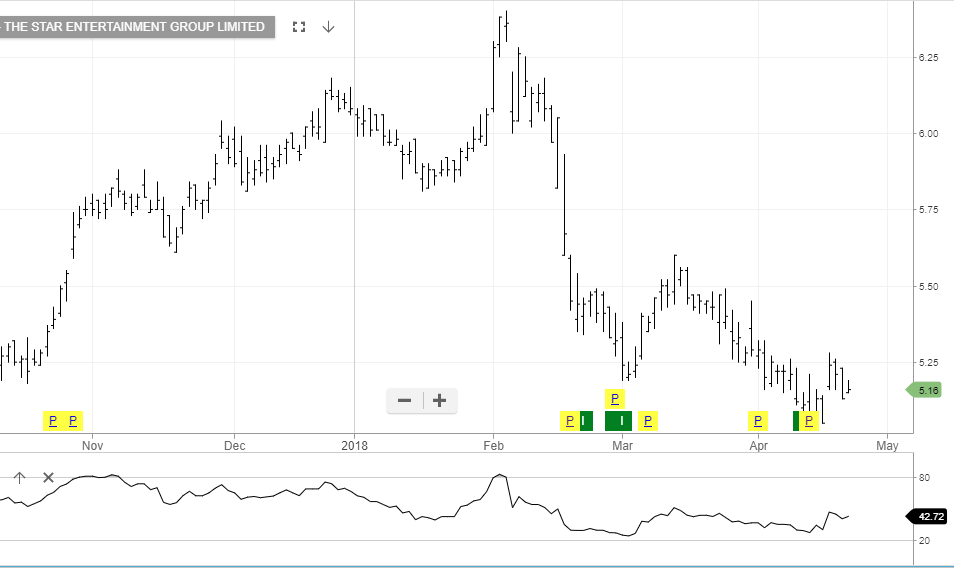
Shares of SGR continue to show an upward bias after finding solid buying support near the $5.00 area last week.

A research piece from a local analyst noted that the strategic agreement with two HK-based joint venture partners, signed in March,  would boost the share price back into the $6.10 to $6.25 range over the medium-term.

Our ALGO engine triggered a buy signal in SGR on April 12th at $5.11.

The technical picture improved last week with several internal momentum indicators now pointing higher.

Star Entertainment Group


Sydney Airports – generating 10%+ cash flow

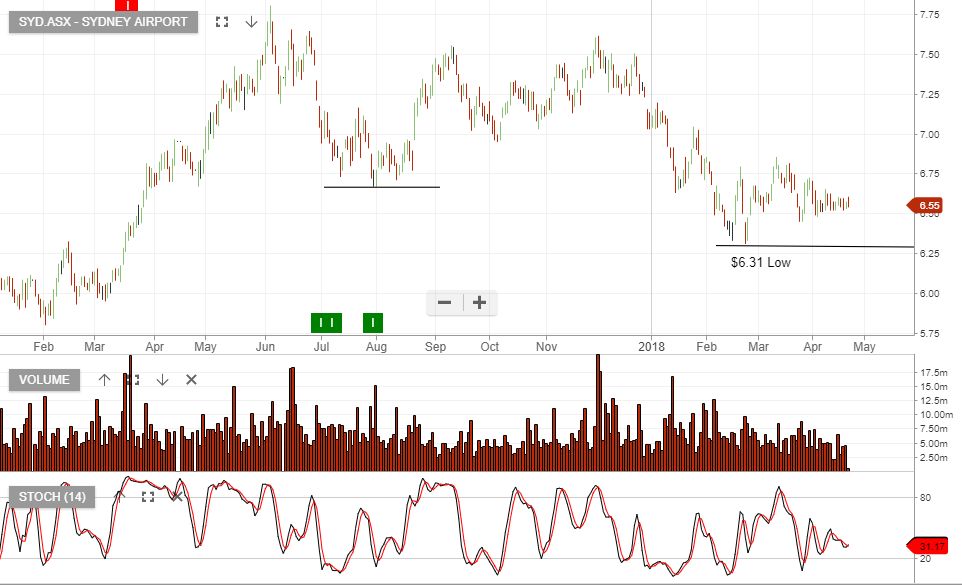
Sydney Airports reported March quarter traffic growth of 6%, with International up 11% and domestic up 3.5%.

Total passenger volume was up 4% on the same time last year.

We’re comfortable buying SYD and selling a $7.00 call option to enhance the yield.

A combination of the dividend and the option premium is generating 10%+ cash flow on an annualised basis.

SYD goes ex-div on the 29th June for 16.5 cents per share.


S&P/ASX 200 Index finished the week up 0.7%

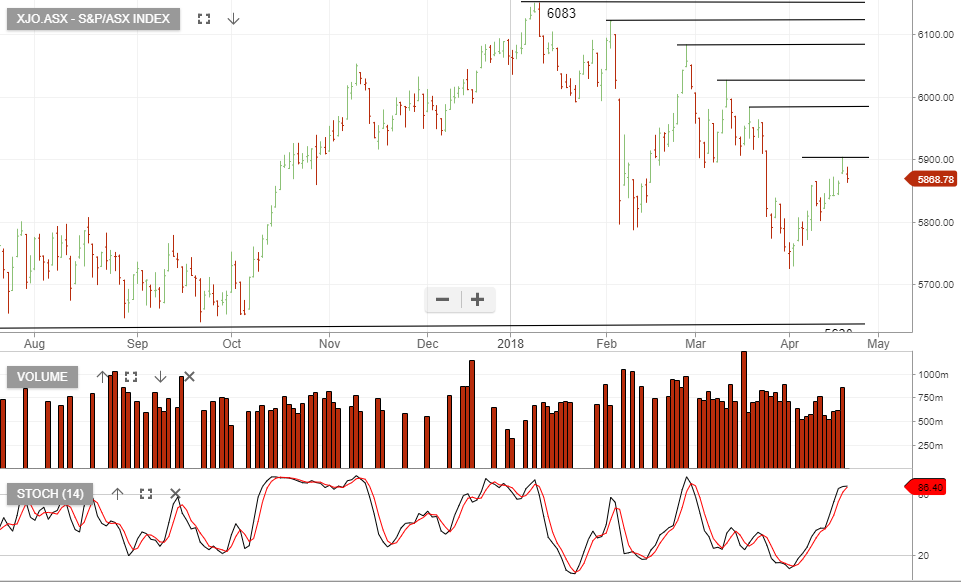
The S&P/ASX 200 Index finished the week up 0.7%. The best performer was the Materials sector, up 3.4% and the worst performer was the Financials sector, down 1.0%. 

The XJO Index has formed a “lower high” formation at 5900. The cascading lower highs in 2018 continue, which is generally a bearish price pattern.

XJO Index
Dow Jones Index


Quarterly Reports In Focus This Week

There are two Quarterly production reports and an AGM this week which could offer trading opportunities for investors.

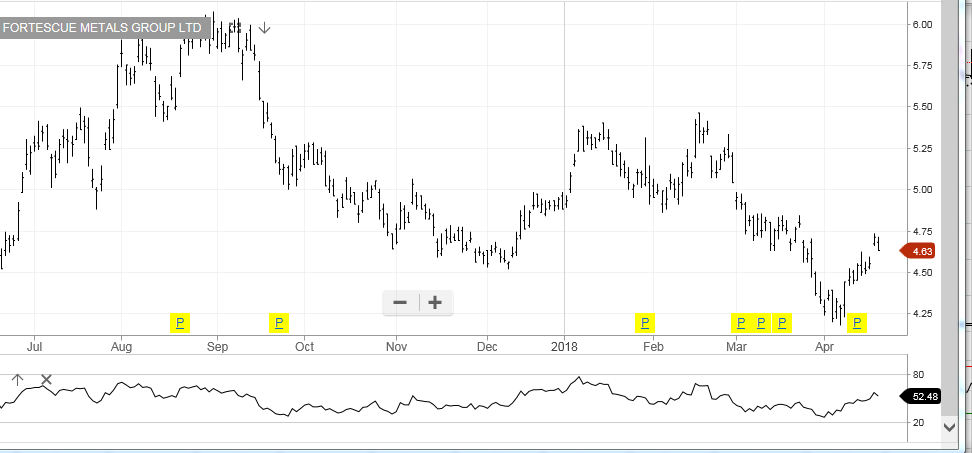
 OZL will hold its AGM on Tuesday,  and FMG and NCM will release their production reports on Tuesday and Thursday, respectfully.

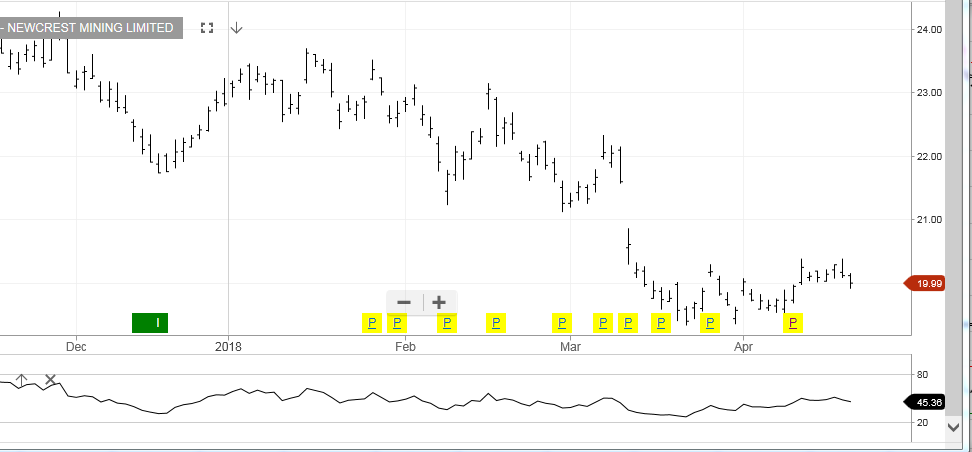
Our ALGO engine is showing a buy signal for all three of these mining names and they are also part of our ASX Top 100 Model Portfolio.

The recent stability in Copper and Iron Ore has supported the shares prices of OZL and FMG, while the “range trading” in Gold has kept NCM active within the $19.60 to $20.30 price band.

For more information about investment opportunities in these names, call our office at 1-300-614-002.

Newcrest Mining

Fortescue Metals Group
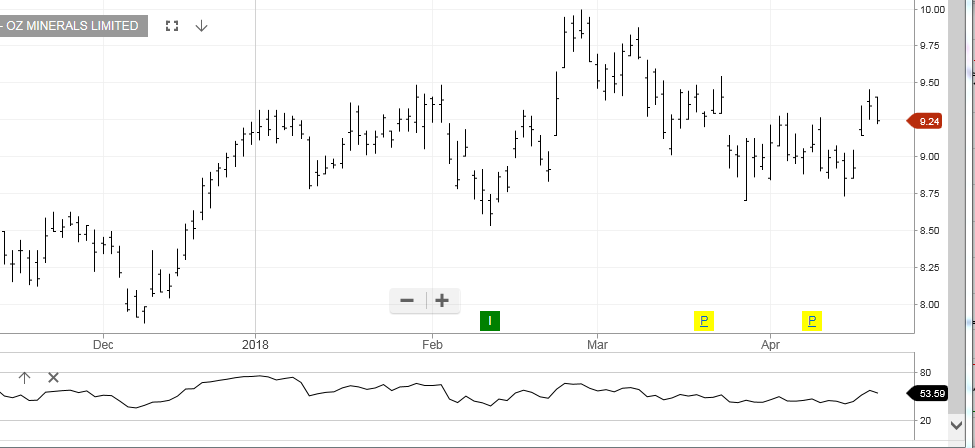
Oz Minerals
ALGO Update: A “Buy/Write” Strategy For MPL

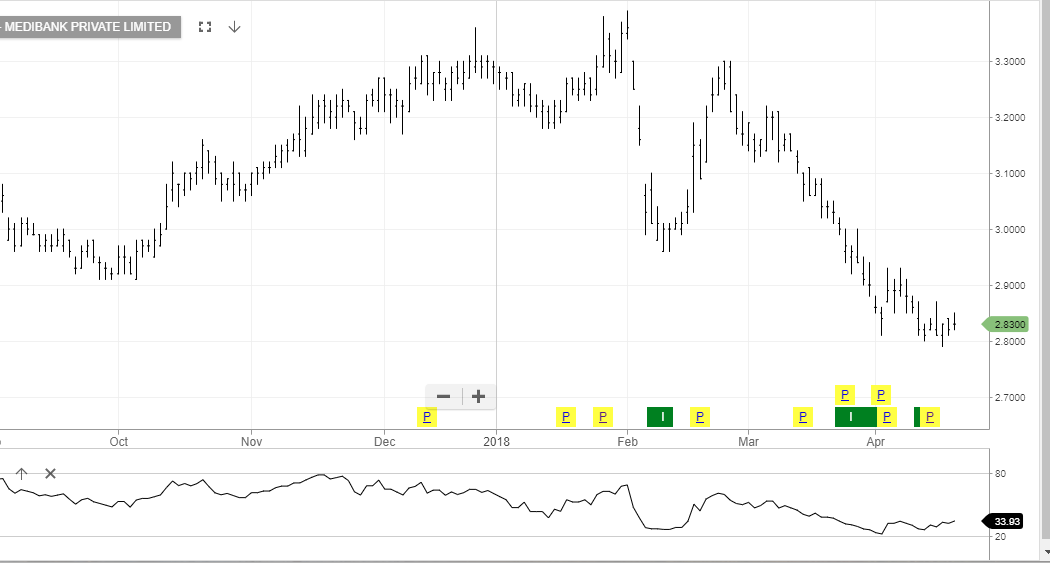
Since trading as high as $3.25 a month ago, the share price of MPL has dropped over 13% to hit an 8-month low of $2.79 this week.

There have been several market reports citing increased political pressure for lower premiums and lower profits for domestic health care providers.

MPL reported a first-half net profit of $245.6 million in February, up 5.9% from the previous corresponding period with an interim fully-franked dividend of 5.5 cents per share, 4.8% higher than the previous corresponding period.

Our ALGO engine triggered a buy signal on MPL at $2.81 on April 13th.

We suggest buying MPL at current levels as a “buy/write” strategy.  More specifically, looking to sell $3.00 Call options into December for 10 to 12 cents.

This will allow for some capital appreciation and investors will collect the 6.75 cent dividend on September 6th.

Medi-Bank Private


Aristocrat reports its 1H18 result on 24 May

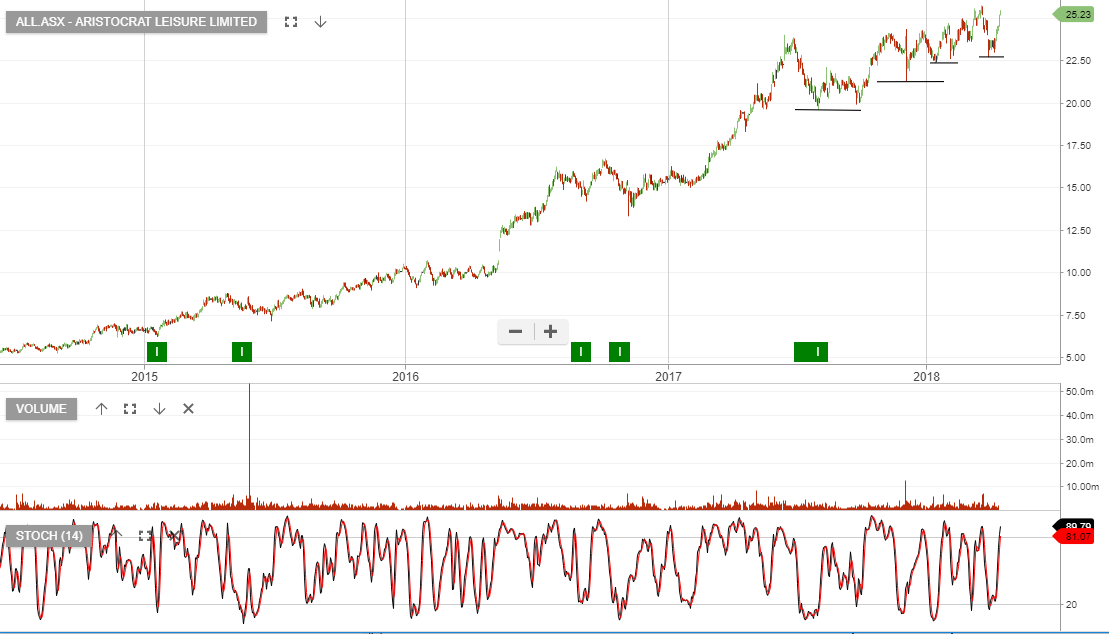
Aristocrat reports 1H18 earnings on the 24th of May and we’re forecasting net profit after tax to be up 20%+ to $330 million.

Earnings growth is underpinned by strength in the North America and Digital businesses. If we assume year-over-year 20% EPS growth, ALL trades on FY20 dividend yield of 3%.

We consider ALL expensive, however, momentum continues to favour the long-side with investors advised to run a stop-loss below recent higher low formations.

Aristocrat