Telstra Shares Firm On Venture Arm News

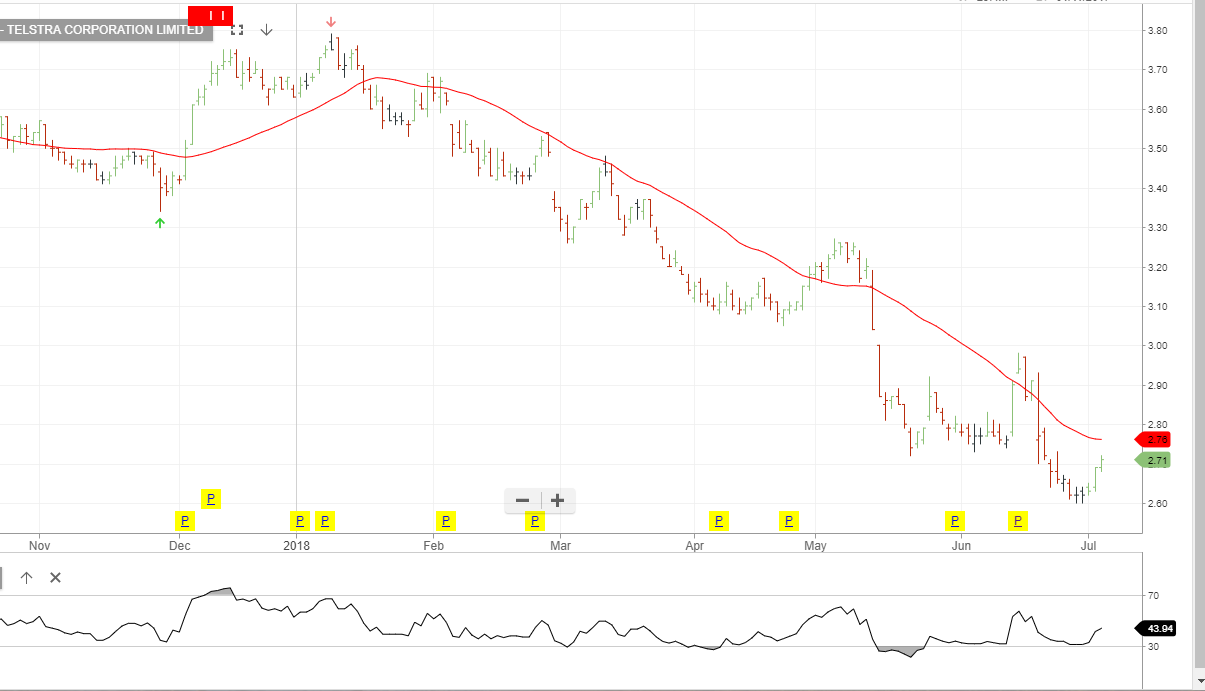
Shares of Telstra have started the new financial year off with a firmer tone rising  3% over the last three days.

Some of the positive sentiment has been driven by the news that TLS has sold 20% of its ventures arm to US private equity firm HarbourVest for $75 million.

The move is part of a broader plan for TLS to become a more technology-focused company and is consistent with the “Telstra2022” strategy announced last week.

HarbourVest has more than $50 billion in assets and the venture fund with TLS is expected to be valued at about $675 million.

After the $500 million loss from the Ooyala fiasco last year, the market may need some convincing that further investment in emerging 5G and next generation businesses will truly add to shareholder value.

It’s reasonable to expect that joining forces with the more experienced HarbourVest validates TLS’s commitment to the venture revenue stream and will see better results.

We believe that at current levels,  TLS represents good value for investors with a medium to longer-term investment time horizon, with an initial target of around $3.90.

At $2.71, TLS is trading at a 9.7 PE and is on a 7.6% yield.
Telstra
Telstra Firms In Front Of Next Week’s Investor Day
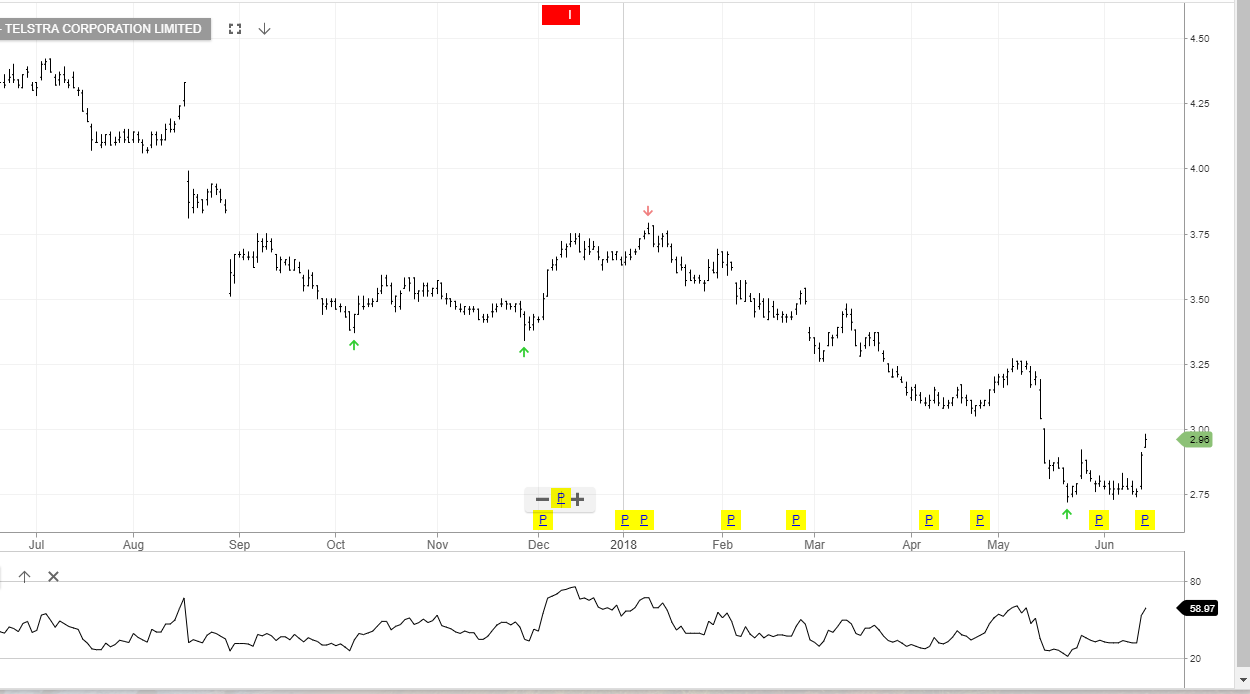
Since posting an intra-day low of $2.74 on Wednesday, shares of Telstra have risen over 8% and are pushing against $3.00 in early trade today.

We cite two fundamental catalysts for the renewed buying interest in the telco giant.

First, the acquisition of Time Warner by ATT in the US has supported the idea of  global telecommunication firms increasing revenue by diversifying into media and entertainment.

Second, TLS will be hosting its highly anticipated investor day next Wednesday, June 20th.

We expect this event to be a pivotal day for TLS as it’s expected to discuss its growth initiatives, future earnings and the status of its dividend.
We consider TLS good value at current prices and look for an upside target near $3.90 over the medium-term. 
Telstra


Buy And Hold Telstra

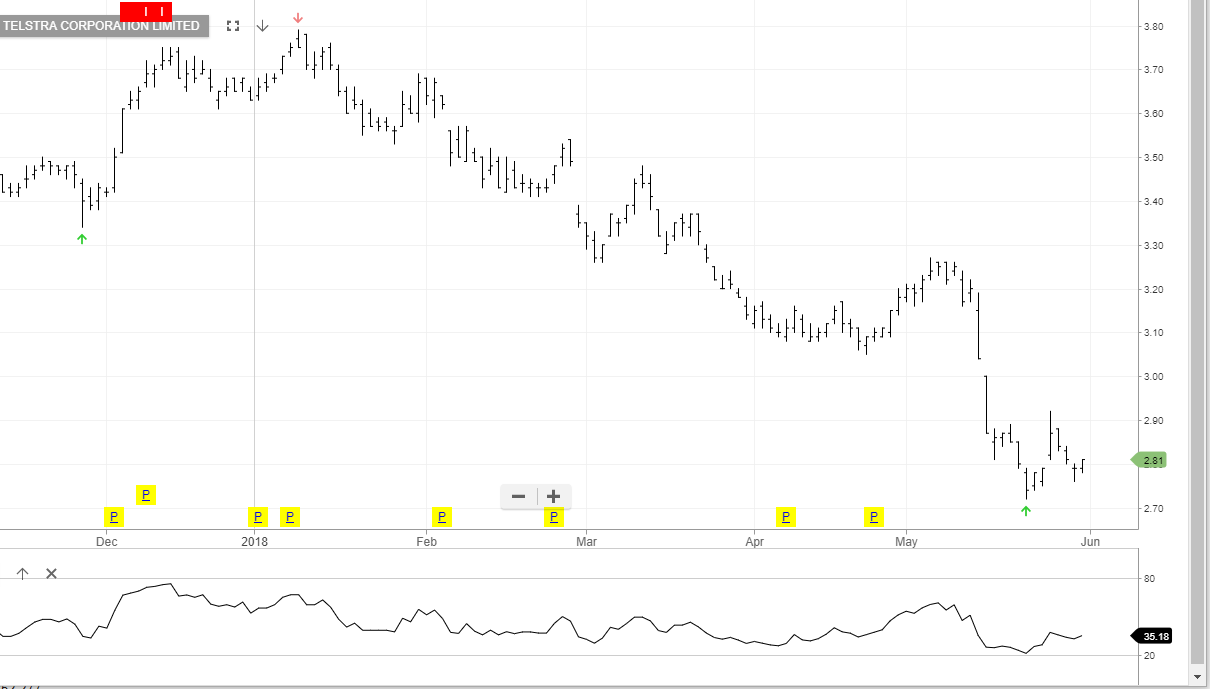
Since breaking down through the $3.00 mark on May 15th, shares of TLS have range traded between $2.70 and $2.90.

Much of the negative commentary about the Telco giant has revolved around its ability  to hold on to its 47% market share,  increase its profit margins via 5-G technology and maintain its dividend.

We feel that these questions will be answered in the affirmative during their business update call on June 20th.

At current prices, TLS has a dividend yield of 7.9% and a P/E ratio of 9.30, which we feel is good value for investors.

Telstra


Telstra Still Leads The Telco Pack

Shares of TLS have been in a basing pattern above the $3.00 level and there are solid fundamental reasons for accumulating shares in this current range.

Since the share price has slipped over 17% over the last 12 months, the current yield is now close to 10%, including the franking credits.

Mobile is the company’s biggest earner and its most important revenue stream. TLS added 235,00 net new retail customers in  H1 compared to 200,000 a year ago and only 18,000 in the June half of 2017.

A recent analyst research letter forecasts the continued dominance in the Telco space, as well as diversification into other data streams will lift the share price into the $4.60 area over the medium-term.

As such, we continue to favor the long side of TLS for value investors looking for growth and a solid dividend.

Telstra


Telstra Is Back In The Buyzone

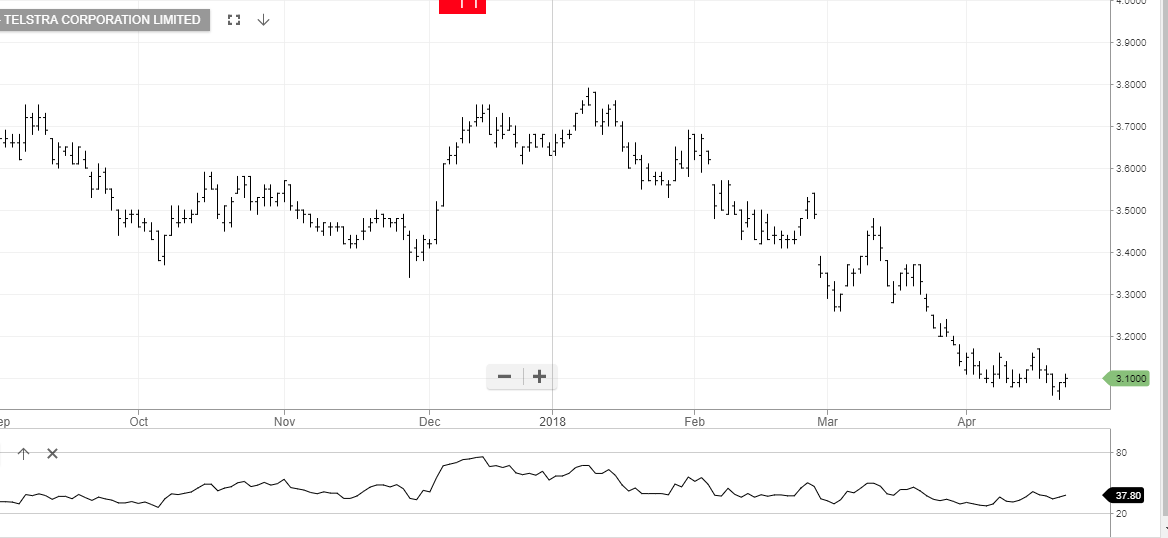
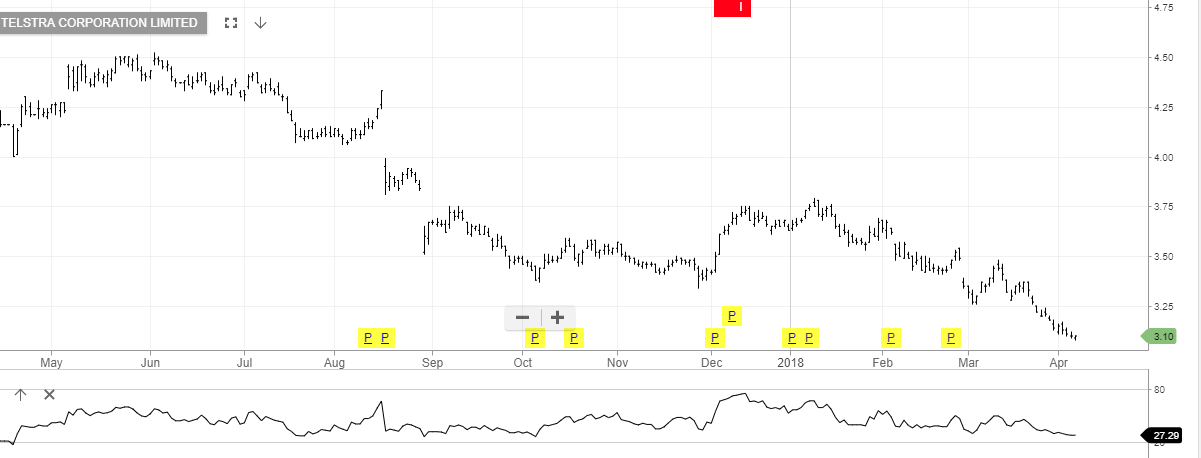
Shares of Telstra have been under pressure for the last 12 months and posted an 8-year low of $3.08 in early trade today.

Investors’ concerns over the telco giant’s profitability and decision to cut its dividend have been the driving forcesa in the share’s decline.

We remain upbeat on the TLS’s prospects and expect market sentiment will soon become positive.

It’s reasonable to expect that the Federal Government will decide to write down the value of the NBN, which will lead to higher margins for TLS.

This would make its 22 cents per share dividend secure over the longer-term.

At the current share price, that pencils out to a fully-franked yield of 7%.

Telstra

Can Telstra Shares Firm Into Ex-Dividend?

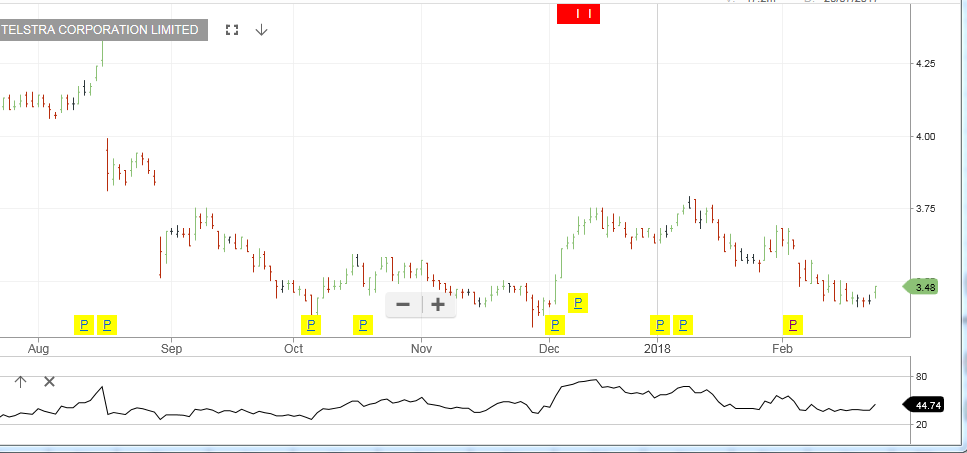
Since the release of their H1 earnings results on February 15th, shares of TLS have traded in a narrow 10 cent range between $3.40 and $3.50.

Looking past the $273 million impairment made against its Ooyala business, the growth in the TLS Enterprise and Whole businesses has been encouraging for top line growth.

The company reported earnings per share of 14.3 cents for the period and declared an interim fully franked dividend of 11 cents per share.

This was made up of a 7.5 cents per share ordinary dividend and a 3.5 cents per share special dividend.

The record date for both dividends is March 1, with payment then expected to be made on March 29.

It’s reasonable to expect some buying interest to come into the share price in front of the dividend date.

We prefer the long side of TLS at these levels and look for a return to the $4.00 handle over the medium-term.

Telstra


Buy And Hold Telstra

Over the course of the last six months, TLS shares have been beaten down as the company purges its liabilities to the NBN and re-calibrates other assets.

As part of that process, the telecom giant announced that it will be writing down the value of its Ooyala video streaming firm to zero.

This will result in an impairment charge of $273 million in the half year numbers.

Technically, TLS shares have been building a solid base in the $3.50 to $3.60 area and we expect to see the stock trade back into the $4.00 handle over the medium-term.

With an annual dividend yield just under 8%, we suggest investors look to accumulate TLS shares in this price area.

Telstra


The Technical Picture Is Improving For Telstra

Shares of TLS have traded back into a significant technical price area.

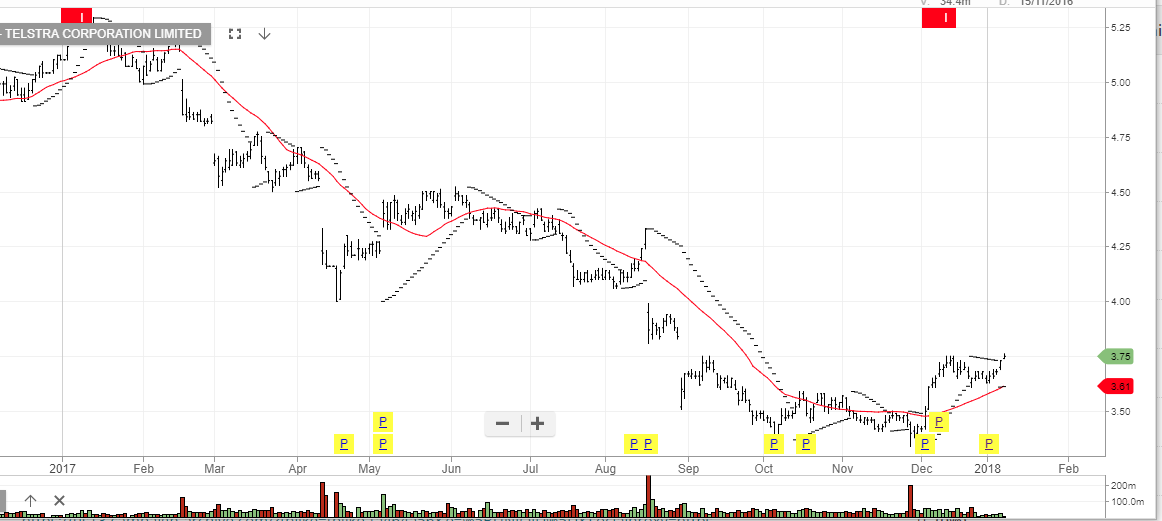
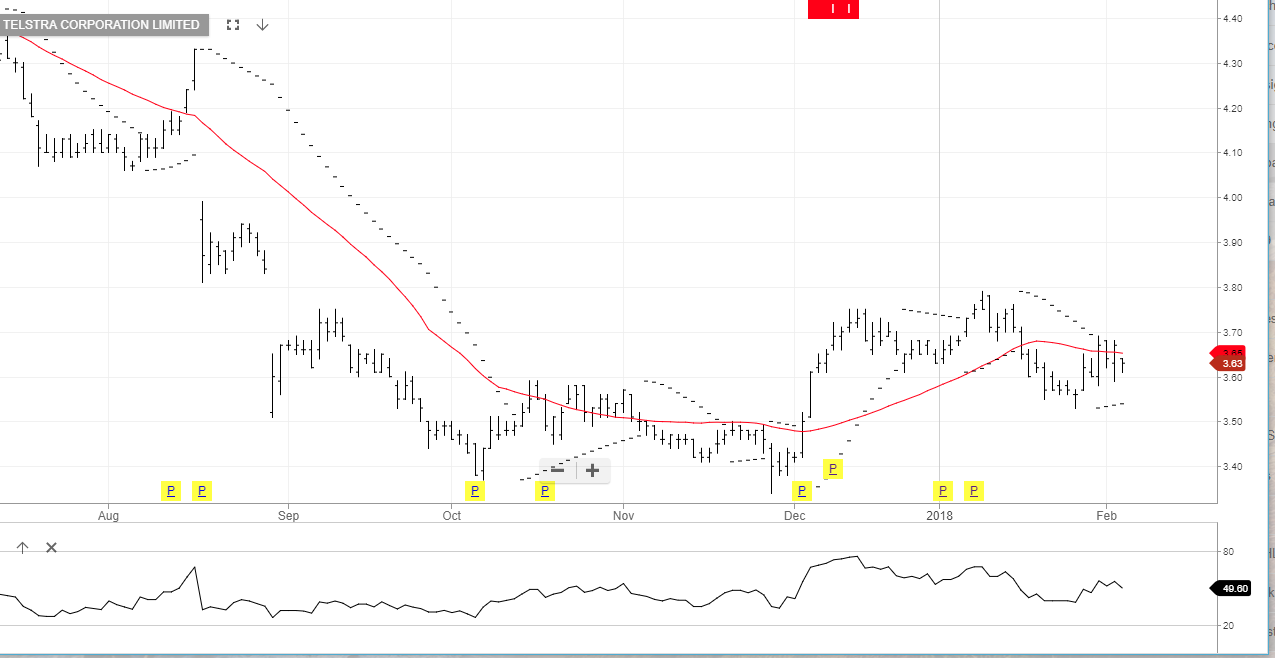
Looking back to mid-August, the share price was beaten down from $4.33 to $3.50 just 10 trading sessions. This price action has left several gaps on the daily chart which are now being challenged.

TLS goes ex-dividend on March 1st and is on about a 6% yield at current prices.

It’s reasonable to believe that the current technical buying could lift the share price back over $4.00, which would still pencil out to over 5% yield, fully franked.

We still believe accumulating shares of TLS in this price range will benefit investor portfolios throughout 2018.

Telstra


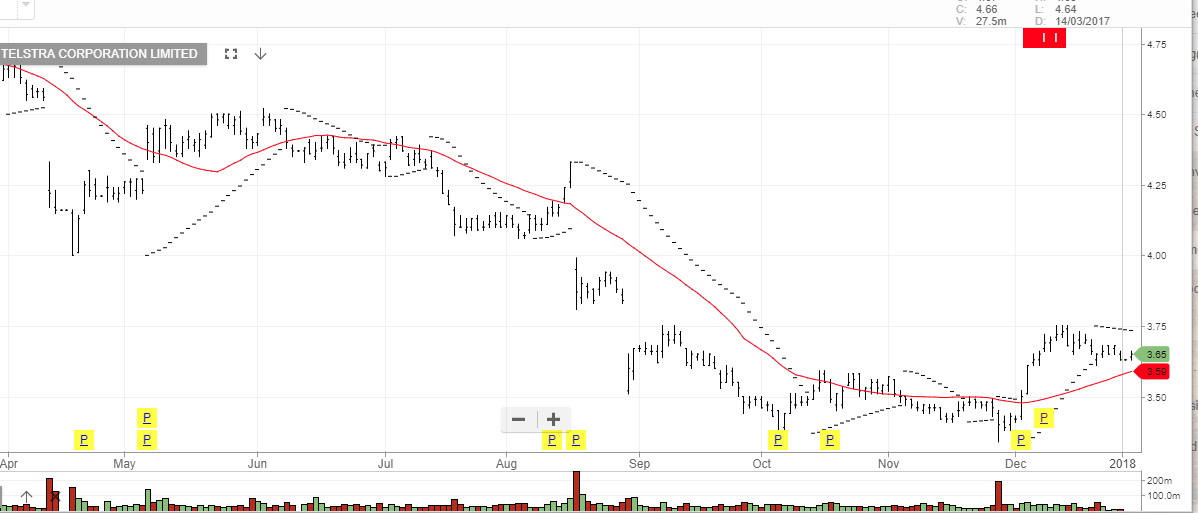
Telstra Continues To Firm Into 2018

Even with the 10% rally from the $3.34 low posted on November 28th, shares of Telstra dropped close to 30% in calendar year 2017.

We believe that investors were overly focused on past NBN issues and earnings estimates which seem to be pricing in worst case scenarios that assume TLS could be losing its dominate position in the telecommunications sector.

With the best existing mobile network and largest customer base, it’s our view that TLS is best positioned to profit from the growth area of mobile data application outside the NBN.

At $3.65, the projected full year dividend of 31 cents pencils out to an 8.5% yield. We consider TLS a solid addition to portfolios at these levels.

Telstra