Telstra Disappoints

Telstra shares are down over 4% in early trade as Australia’s largest telecommunication company announce half-yearly profits down 14.2% and revenue 3.6% lower.

The company reported half-yearly profits of $1.79 billion compared to $2.09 billion this time last year. Revenue fell to $12.8 billion from $13.3 billion over the same period of time.

Their EBITDA of $5.18 billion was at the low end of earlier guidance, which is a sign that Telstra is undergoing a difficult transition to the post-NBN world.

The company announced an interim dividend of 15.5 cents per share, fully franked, which returns $1.8 billion to shareholders.

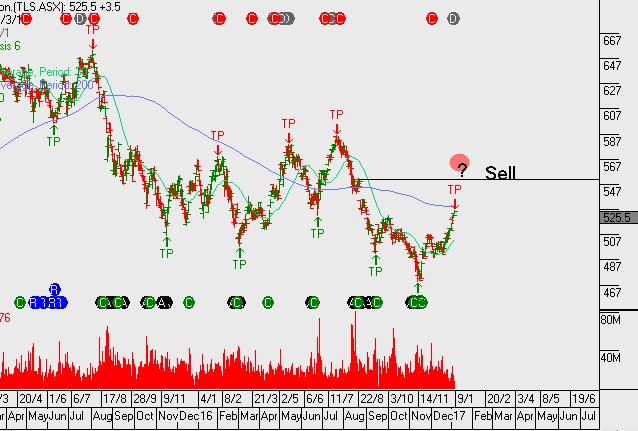
Our Algo Engine created a short signal in January at $5.27
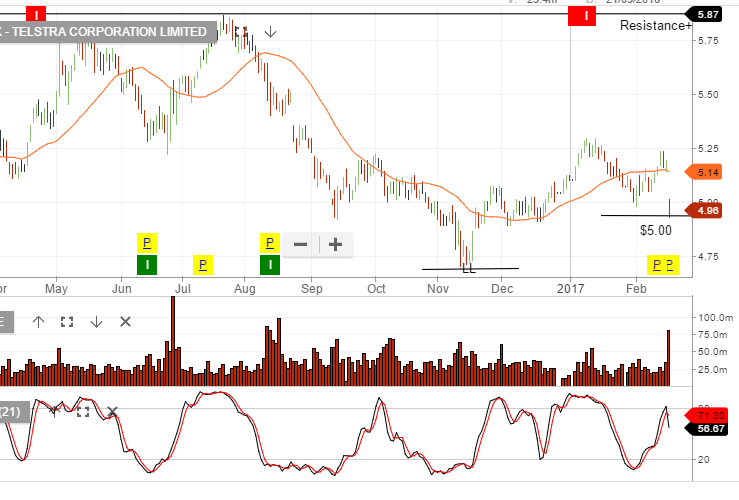
Chart -TLS

Telstra & TPG Valuation Review

Until October 2016, TPG Telecom was the fast growing telco with almost 20% EPS growth whilst trading on a low 2% yield.

Then came the earnings update and the company suggested future EPS growth will be more like 5%. If Telstra is growing earnings at 3 – 5% and paying a 6% yield, why would an investor buy TPG on a substantially different yield or valuation?

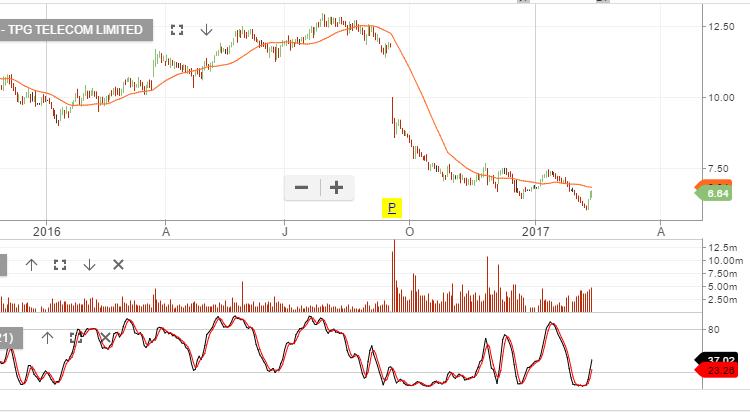
You just wouldn’t. As such,  we’ve watched TPG sell-off from $12.50 to $6.20 and the stock is now back on a  4.5% yield. TPG will likely find buying support now and the market is hoping EPS growth will creep higher into the range of 5 – 10% to support the yield differential with Telstra.

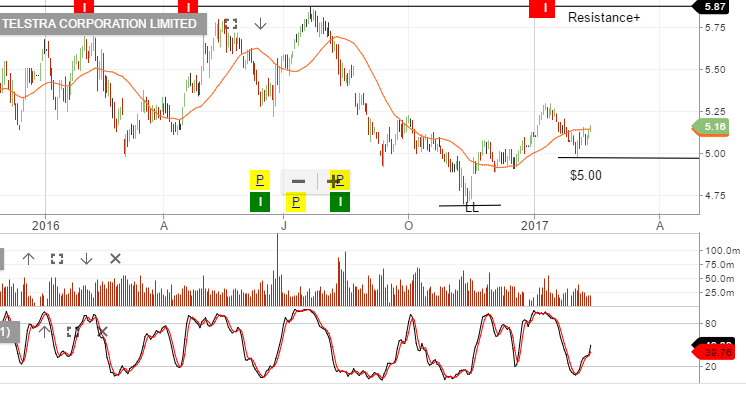
We’ve been buyers of Telstra at sub $5.00 and we’re looking for the stock to trade $5.50 before evaluating a covered call option strategy.


Chart – Telstra
Chart – TPG Telecom


Telstra – Counter Trend Rally

We’ve been buyers of Telstra from the recent lows and see the possibility of the stock trading into the $5.40 to $5.70 range in the weeks ahead. We are undecided if we sell covered calls over TLS and will likely wait until the February earnings result, to see what the underlying EPS growth trends look like.

We have TLS on a 6% yield and delivering around 4 – 6% EPS growth into 2017.

Chart – TLS

Telstra FY16 Earnings Result

Telstra (TLS.ASX) released its FY16 result with total income up 2.3% to $26.5bn and EBITDA down 3.9% to $10b, final dividend of $0.155 taking the full year dividend to $0.31 FY17 outlook is for 5% income growth and 3 – 5% EBITDA growth.  Capital management of $1.5bn in the form of a share buyback will be welcomed by investors. 

We have been buyers of Telstra since the $5.20 low in June and again on this pullback it’s worth looking for an entry point.   

TLS

Long TLS

Long TLS.ASX

TLS

We had a buy signal at $5.20 in June. Telstra is now in a higher high, high low technical pattern and supported by 6% div yield. Investors are positioning ahead of the upcoming 1.5billion dollars to be retuned to shareholders in the next 6 months. TLS can rally through to $6.00 before investors may wish to look at locking in gains.