Astera Labs

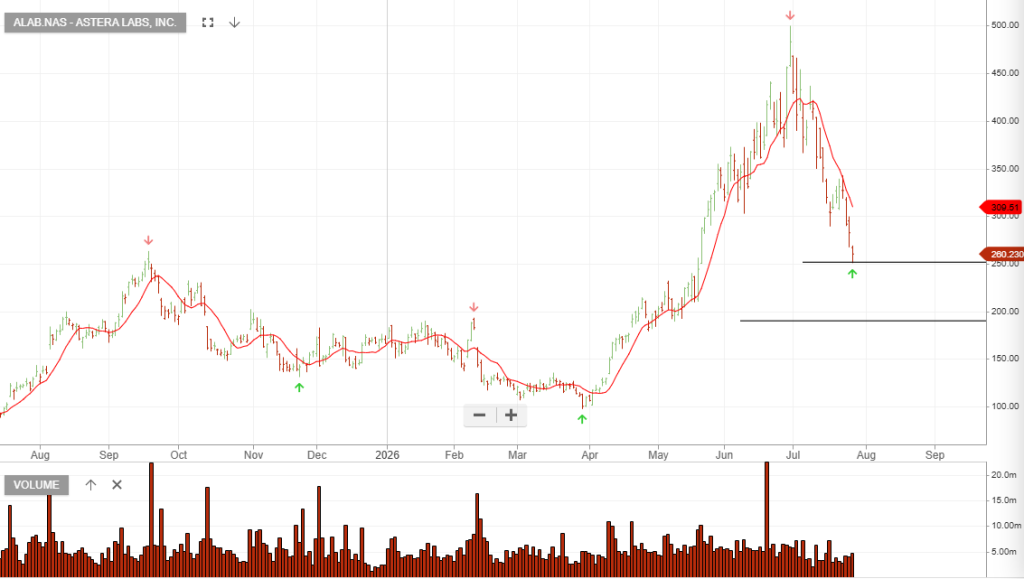
Astera Labs,

Critical AI Bottleneck Layer: As GPU clusters grow into tens or hundreds of thousands of chips across multi-rack networks, high-speed signal integrity over copper and optical media becomes vital.

    Emerging Competition: Larger networking/semiconductor players (Broadcom, Marvell, Credo) continue developing competing scale-up connectivity solutions.

    Upcoming Earnings Announcement

    • Next Earnings Date: Tuesday, August 4, 2026 (After Market Close)
    • Q2 2026 Guidance (Provided by Management):

    * Revenue: $355.0M – $365.0M (~15%–18% sequential QoQ growth)
    Most Recent Quarter: Q1 2026 (Quarter Ended March 31, 2026)
    Astera Labs delivered record-breaking top- and bottom-line results, beating Wall Street estimates driven by accelerating demand for high-speed PCIe Gen6 and switch fabric hardware in AI clusters.

    • Revenue: $308.4 Million

    * YoY Growth: +93.4% vs. Q1 2025 ($159.4M)
    United Micro

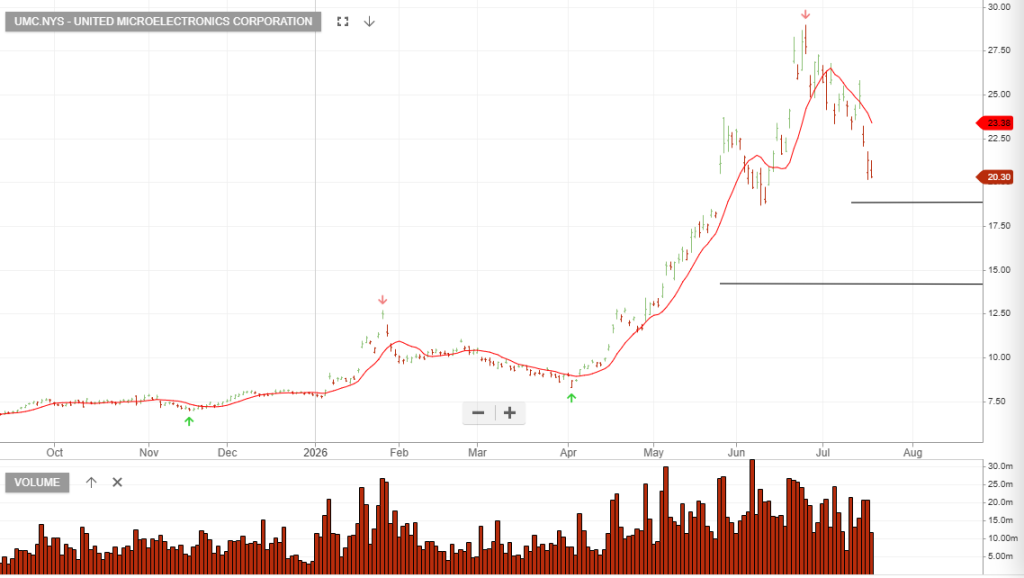
    NAS:UMC add to watchlist and look for interest to build near $18.50

    In early 2026, UMC announced a high-profile partnership with Intel to collaborate on a 12nm platform manufactured in the US. This partnership is slated for commercial production in late 2027 and vastly diversifies UMC’s geographic footprint.

    • Strong Balance Sheet: Fitch affirmed UMC’s BBB+ credit rating with a “Stable” outlook in June 2026. The company boasts a low debt-to-equity ratio of ~0.19 and a healthy current ratio of ~2.72.
    • Next Earnings Release: UMC is scheduled to report its Q2 2026 earnings on Wednesday, July 29, 2026. Analysts expect EPS of 15 cents on revenue of ~$2.06 billion, representing growth over the prior year.

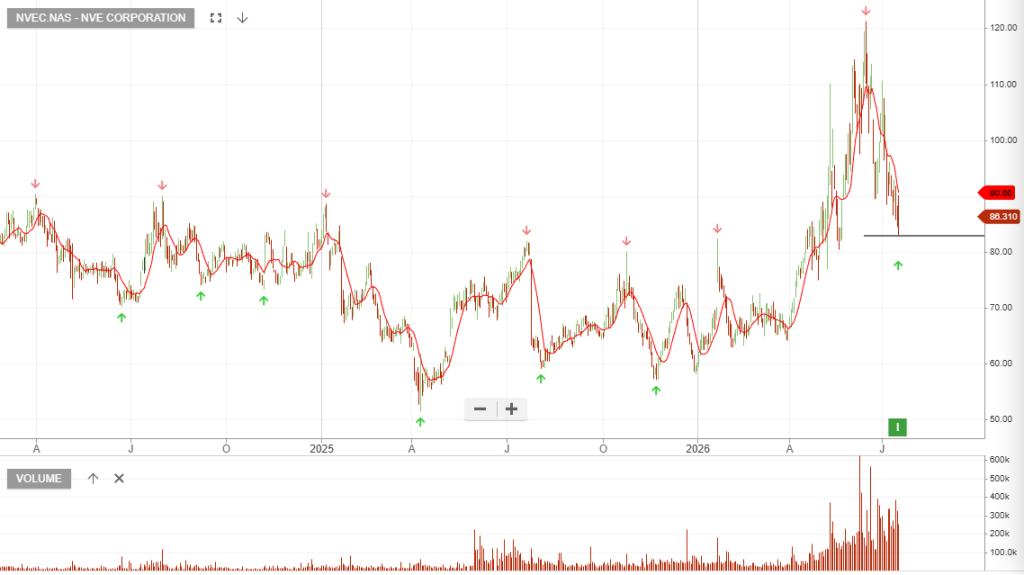
    NVE Corp

    NVE

    While NVE is a niche semiconductor player rather than a massive chipmaker, it fits into the broader AI infrastructure landscape via:

    1. Next-Gen Memory (MRAM): As AI workloads and edge computing demand faster, more energy-efficient non-volatile memory, MRAM technology is highly regarded for its low power consumption and high endurance.
    2. High-Speed Data Isolation: Their spintronic couplers handle high-speed data transmission with high noise immunity, which is crucial in rugged Industrial IoT (IIoT) applications and server power supplies.

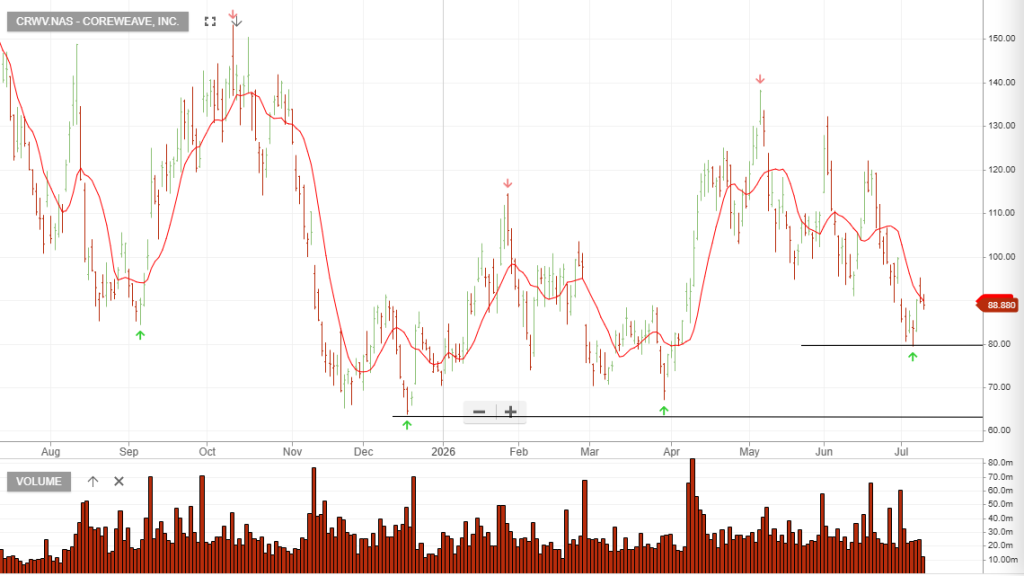
    CoreWeave

    {NAS.CRWV}

    Full-Year FY 2026 Guidance: The company has reaffirmed full-year revenue guidance of $12.0 billion to $13.0 billion (with consensus currently sitting at $12.6 billion). This represents an incredible ~146% year-over-year growth rate compared to FY 2025 revenue of $5.13 billion.

      • Management secured over $20 billion of financing this year, with no material debt maturities before 2029 despite elevated leverage.
      • Ten customers have committed at least $1 billion each, while the financial services backlog alone has approached $10 billion.
      • The stock now trades near 3.5x FY2026 revenue despite consensus expecting revenue to nearly double to $25 billion next year.

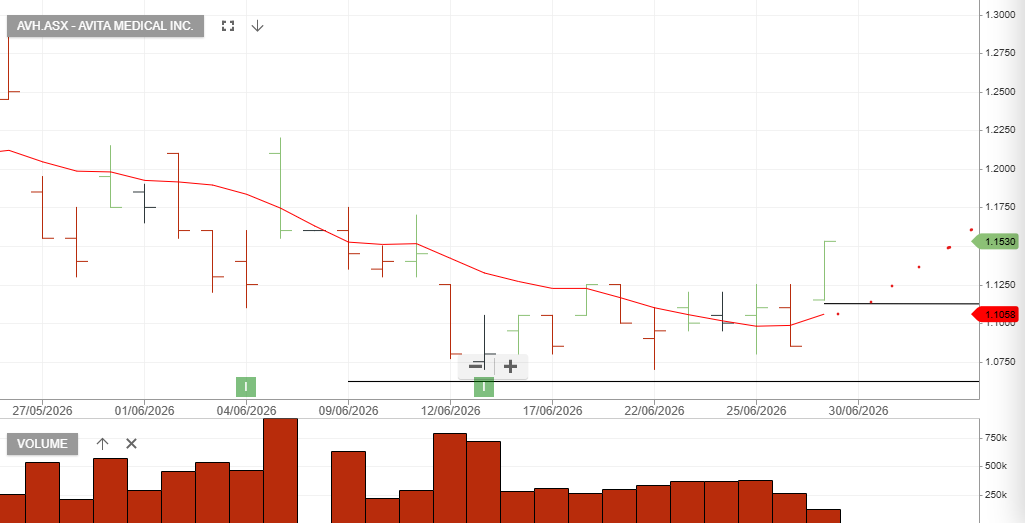
      Avita Medical

      Avita Medical is a commercial-stage regenerative medicine company focused on acute wound care and therapeutic skin restoration.

      • Market Capitalization: ~AUD $170.81M – $174.95M
      • Earnings Per Share (EPS): -AUD $0.452 (unprofitable)
      • Performance (2026 YTD): +3.33% (though down roughly 27% over the past 12 months as the company works to scale and reduce cash burn).

      Revenue Growth: Q1 2026 revenue reached $19.3 million USD, a 4% year-over-year increase and a 10% sequential increase from Q4 2025, showing gradual recovery following reimbursement and distribution disruptions in late 2025.

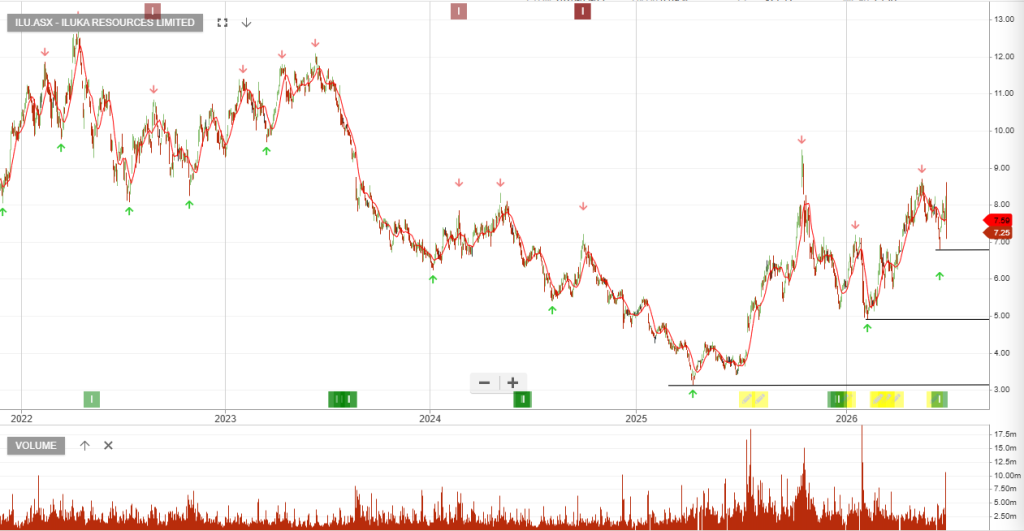
      Iluka

      Iluka Resources earnings forecasts reduced due to the slower ramp-up profile.

      First Rare Earths Offtake Agreement Secured

      • Iluka announced a four-year take-or-pay offtake agreement covering approximately 1,200 tonnes of Nd, Pr, Dy and Tb from CY28 onward.
      • The contract represents about 10% of planned rare earth production and validates demand for Eneabba’s future output.

      Production Ramp-Up Appears Slower Than Expected

      • Contracted volumes imply a more gradual production ramp-up than previously forecast.

      Eneabba Refinery Funding and Construction De-Risked

      • Export Finance Australia confirmed access to the full A$1.65bn non-recourse government loan.
      • The refinery is over 50% complete, capital cost remains A$1.7–1.8bn, and commissioning is targeted for mid-2027.

      The offtake agreement is a strategic positive that validates Eneabba’s rare earth project, but the market may need to temper expectations around the speed of production ramp-up. Macquarie remains constructive on the longer-term rare earths opportunity.

      Ramelius Resources

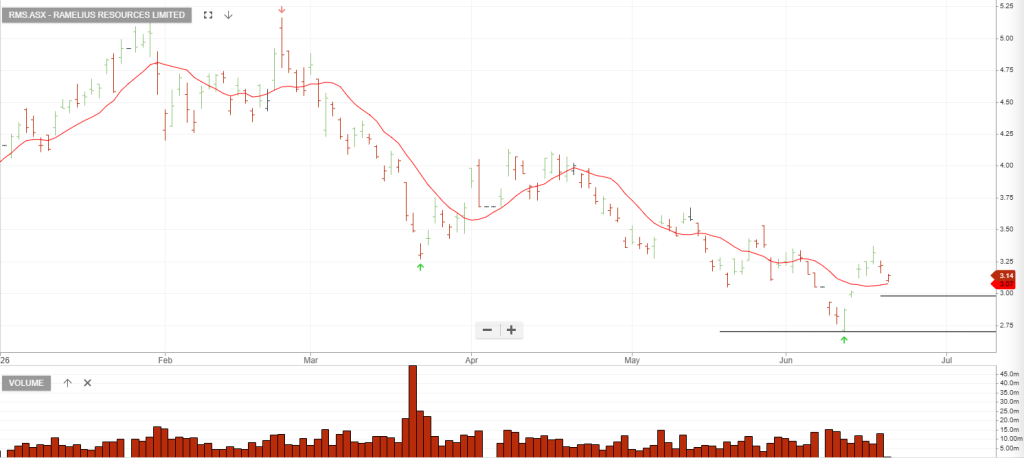
      Ramelius Resources

      Buy with the stop loss at $2.97.

      Statutory figures were heavily impacted by the acquisition of Spartan Resources.

      • Revenue: A$485.6 million, down 4% (H1 FY25: A$508 million) due to transitional production phases.
      • Underlying EBITDA: Record H1 of A$347.7 million, up 13% (H1 FY25: A$307.6 million), driven by high spot gold prices.

      CSL

      CSL

      CSL appears to be approaching a profitability low point in FY26, with FY27 expected to mark a return to earnings growth. Management’s transformation initiatives, lower plasma collection costs, and the removal of excess immunoglobulin (Ig) inventory from the US market should support margin recovery and earnings improvement. While challenges remain from competitive pressures in Ig, albumin, KCentra and Vifor pricing, the company is positioned to deliver modest profit growth.

      Key Bull Points

      • FY27 earnings recovery expected: FY26 is likely the trough year, with FY27 benefiting from easier comparisons, including the removal of ~$300m of excess Ig inventory and ~$300m in transformation savings.
      • Behring margins should improve: Lower plasma collection costs from nomogram collections are expected to drive a noticeable gross margin recovery, supported by around a 10% increase in plasma collected per donor at no extra cost.
      • Transformation programme provides meaningful support: CSL expects approximately $300m of gross cost savings in FY27, equivalent to roughly 8% of FY26 NPATA guidance, helping offset industry pricing pressures.
      • Impairments are largely irrelevant to cash flow: The estimated $5 billion impairment charge is non-cash, with the main benefit being lower future amortisation expenses, which could modestly support reported NPAT.
      • Valuation remains attractive: Despite lowering the price target to $158/share (from $175), the stock trades at a significant discount to the broader market multiple, offering potential upside as earnings recover in FY27.