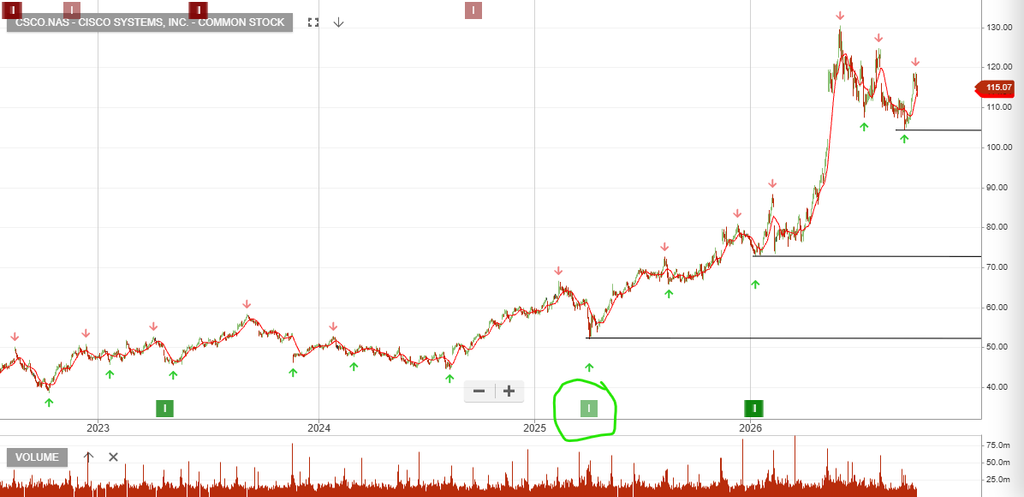
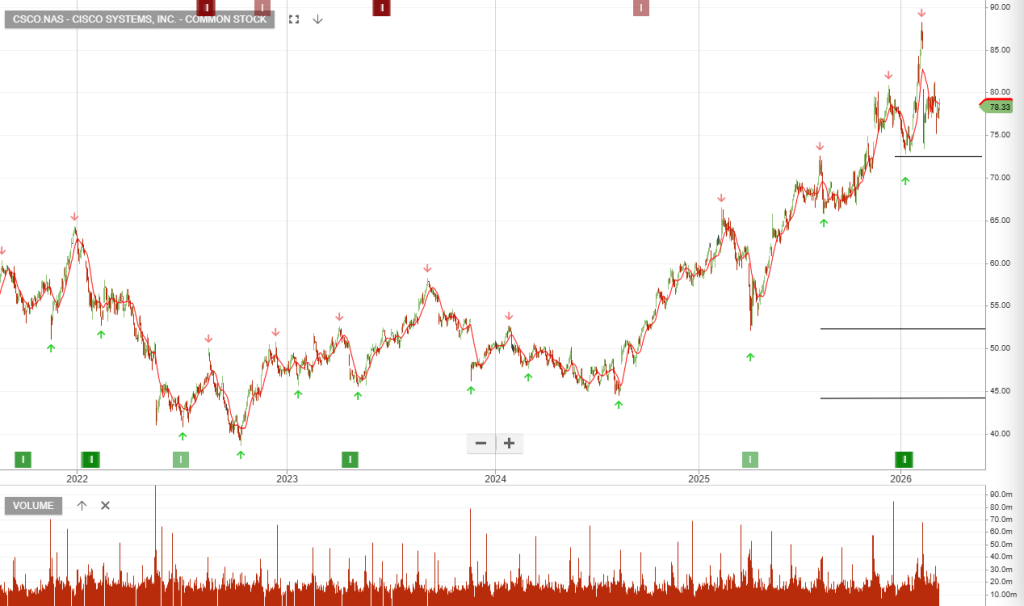
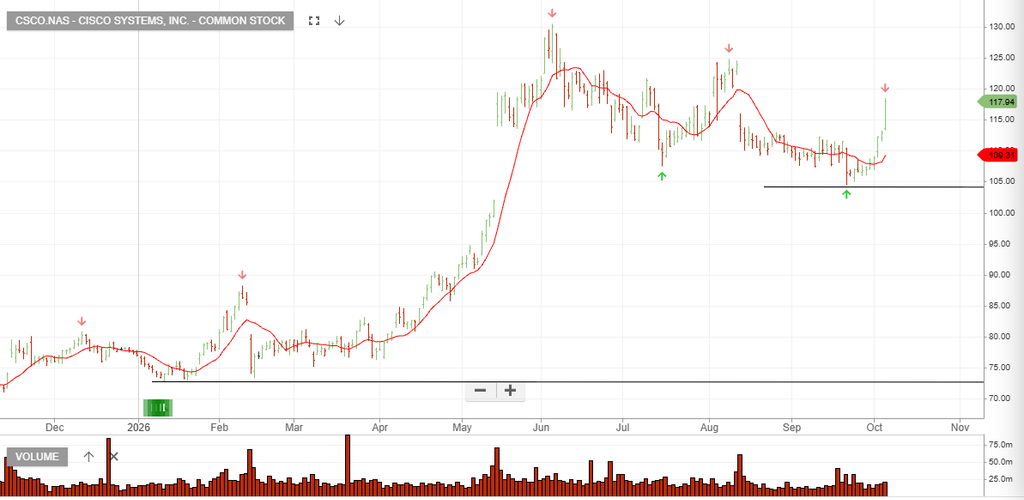
Cisco Systems, Inc. – Common recently reported strong results for its second fiscal quarter (ended January 2024, reported Feb 2026):
Earnings Beat: Reported record revenue of $15.3 billion (+10% YoY) and non-GAAP EPS of $1.04, exceeding analyst expectations.
Guidance: For the full fiscal year 2026, Cisco raised its revenue outlook to $61.2B–$61.7B.
As of March 2026, Cisco (CSCO) is undergoing a major transition from a traditional hardware-focused networking company into an AI-infrastructure and cybersecurity powerhouse.
Here are the key takeaways you should know:
### 1. Recent Financial Performance (Q2 FY2026) Cisco recently reported strong results for its second fiscal quarter (ended January 2024, reported Feb 2026):
Earnings Beat: Reported record revenue of $15.3 billion (+10% YoY) and non-GAAP EPS of $1.04, exceeding analyst expectations.
Market Reaction: Despite the beat, the stock saw a ~9% post-earnings dip (trading around $75–$78) as investors weighed short-term margin pressures against long-term AI growth.
Guidance: For the full fiscal year 2026, Cisco raised its revenue outlook to $61.2B–$61.7B.
### 2. The AI Growth Engine AI is currently the most significant driver for Cisco.
AI Orders: The company took $2.1 billion in AI infrastructure orders from hyperscalers (like Amazon, Google, Meta) in Q2 alone.
Raised Targets: Cisco now expects total AI orders to exceed $5 billion for FY2026.
New Silicon: They recently unveiled the Silicon One G300 chip, designed specifically for massive AI clusters, positioning them as a direct competitor to Broadcom in the high-end networking space.
### 3. Strategic Shift: Cybersecurity & Splunk Cisco is aggressively moving toward a software-subscription model to reduce “lumpy” hardware revenue.
Splunk Integration: Following its $28 billion acquisition, Splunk is being deeply integrated. Security is now viewed as a “native function” of the network rather than an add-on.
Recurring Revenue: Annual Recurring Revenue (ARR) has reached $31.4 billion, with software and services now making up a significant portion of the business.
Backlog (RPO): Cisco has a massive backlog of $43.4 billion in Remaining Performance Obligations, providing high visibility for future revenue.
### 4. Valuation and Dividends For income-focused investors, Cisco remains a “Dividend Aristocrat” in the making:
Dividend: Recently increased to $0.42 per quarter (approx. 2.2% yield).
Capital Returns: The company returned $3 billion to shareholders last quarter ($1.6B dividends, $1.4B buybacks) and still has $10.8 billion authorized for further buybacks.
P/E Ratio: Currently trades at a forward P/E of roughly 25x–27x, which is slightly below the sector median, leading many analysts to view it as undervalued relative to its AI growth potential.
### 5. Analyst Outlook
Consensus: Most analysts hold a “Moderate Buy” rating.
Price Targets: Average targets range between $89 and $96, suggesting a potential upside of 15% to 24% from current levels.
Key Risks: Watch for margin pressure from rising component costs (like memory) and the speed of enterprise AI adoption beyond just the giant “hyperscalers.”
Summary for Investors: Cisco is no longer just “the router company.” It is a massive play on the plumbing required to run AI models and the security required to protect them. The current valuation reflects a transition phase that may offer a more conservative entry point into the AI trade compared to high-flyers like Nvidia.
Sophisticated Investor?
We have special opportunities available for Sophisticated Investors. If you're interested, and qualify, please provide your details below.