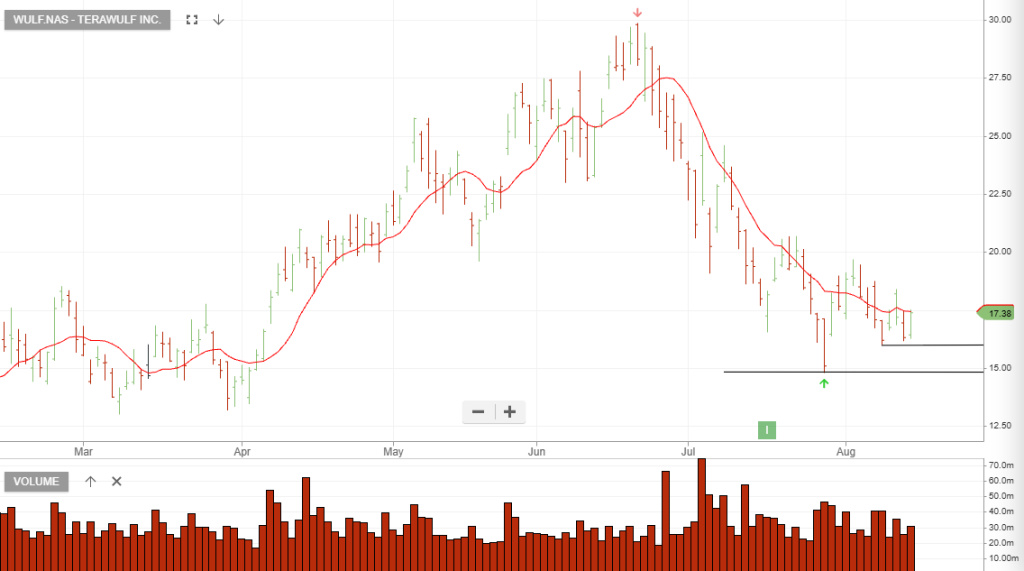
TeraWulf Inc. is a digital infrastructure owner and operator originally founded as a low-cost, zero-carbon Bitcoin mining company. Over the past couple of years, the company has transformed itself into a power-first digital infrastructure platform purpose-built for High-Performance Computing (HPC) and Artificial Intelligence (AI) data centers.
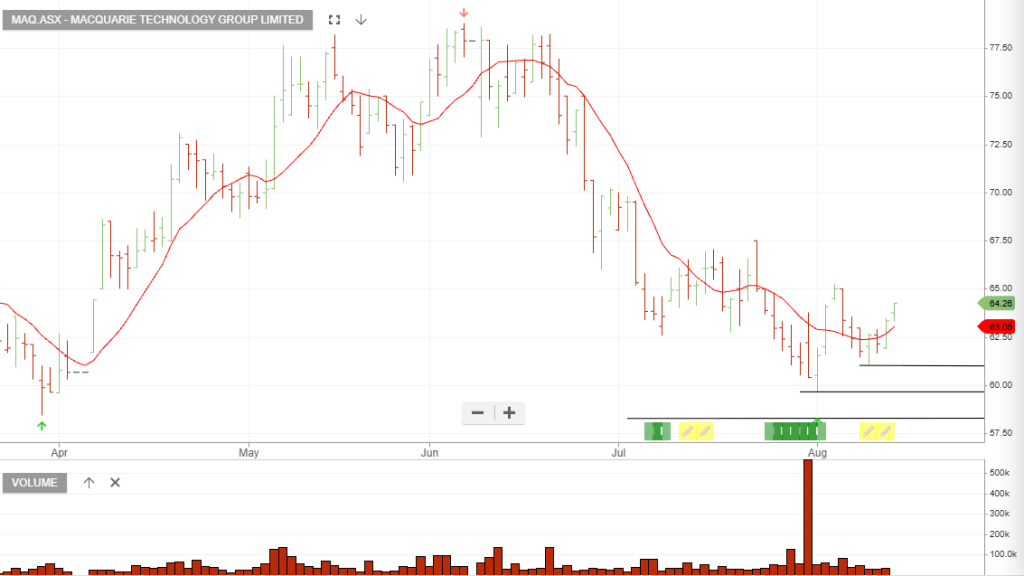
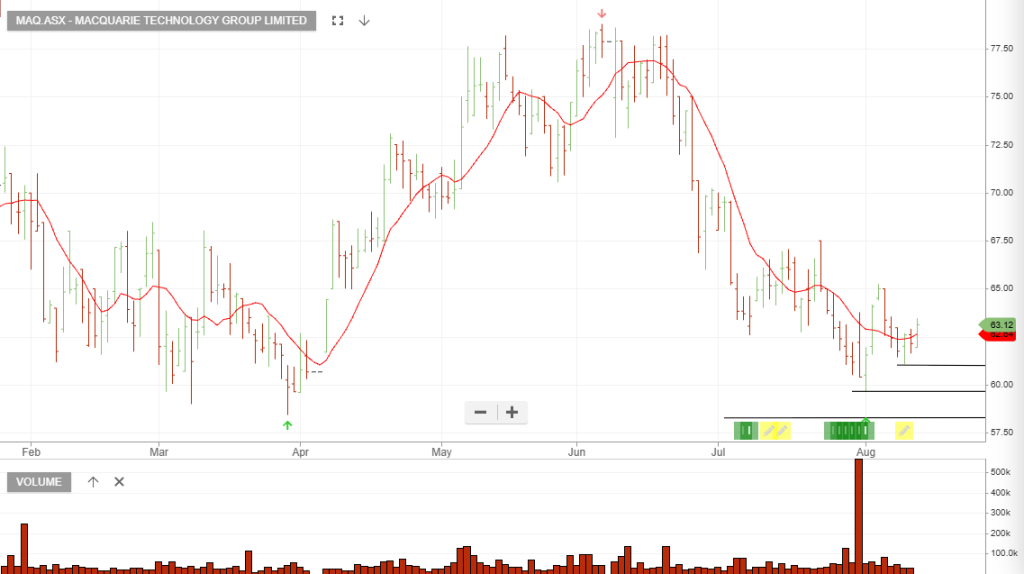
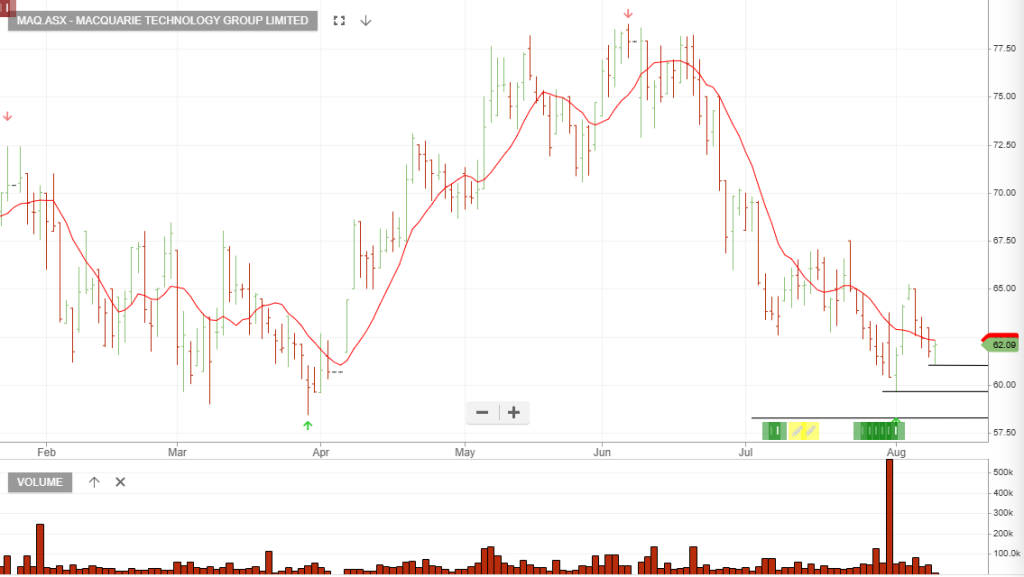
Update 14/8: Buy and place the stop loss at $61.09
Update 13/8: Entry condition triggered, buy with a stop loss at $61.09
Full-Year FY26 Consensus Forecast: Analysts expect full-year FY26 revenue in the range of A$380M – A$390M, representing a year-over-year revenue growth of roughly 3% to 5% compared to FY25
Valuation & Comparative Context
Trailing P/E (TTM):~48.5x – 50.7x (based on recent reported 12-month net profit).
Why the Forward P/E expand relative to Trailing: Net profit after tax (NPAT) is temporarily compressed in the near term due to significant growth capital expenditures—specifically heavy ongoing investments into data centre capacity (e.g., IC3 SuperWest) and increased depreciation/financing costs.
EV/EBITDA Multiple: Shares trade at a forward EV/EBITDA of approximately 17.5x – 18.0x, reflecting strong underlying EBITDA cash flow performance relative to net bottom-line profit.
strategic equity investment and multi-year supply agreement with NVIDIA, fortifying cash balance ($1.59 Billion in cash/equivalents) to fund capacity expansion.
Q4 FY2026 revenue guidance represents expected year-over-year top-line growth of 24.9% to 34.1%, with the midpoint implying a ~29.5% YoY expansion driven by continued momentum in AI data center optical transceivers.
Revenue:$582.3 million, up 454% YoY (beating consensus estimates of ~$573.9 million).
Adjusted EBITDA:$236.2 million (41% EBITDA margin), up from a loss of $21.0 million in Q2 2025.
Q3 2026 Analyst Expectations:Consensus Revenue Target: ~$951.55 million.Consensus EPS Estimate: -$1.41 per share (reflecting heavy capital investments into infrastructure buildouts).