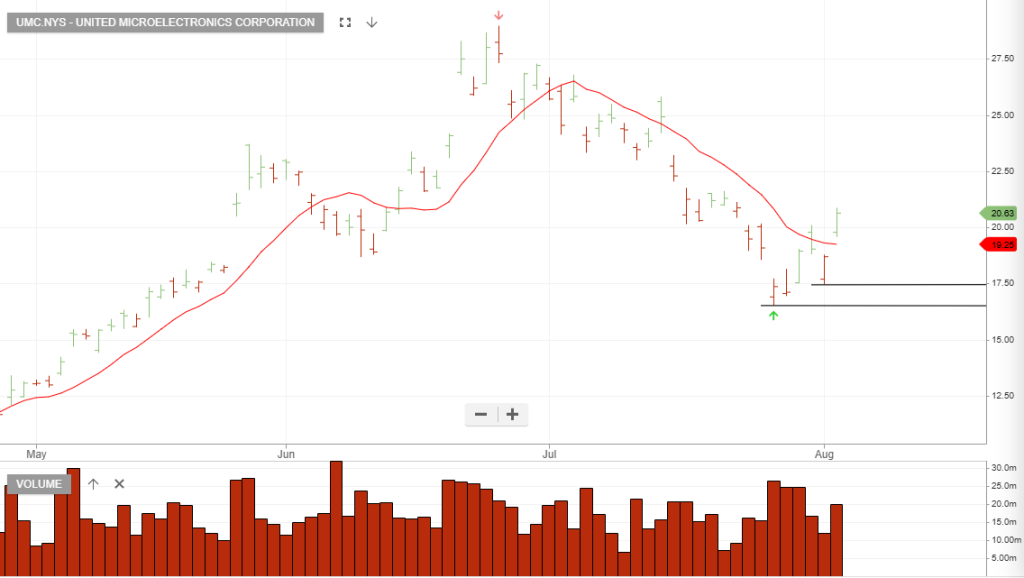
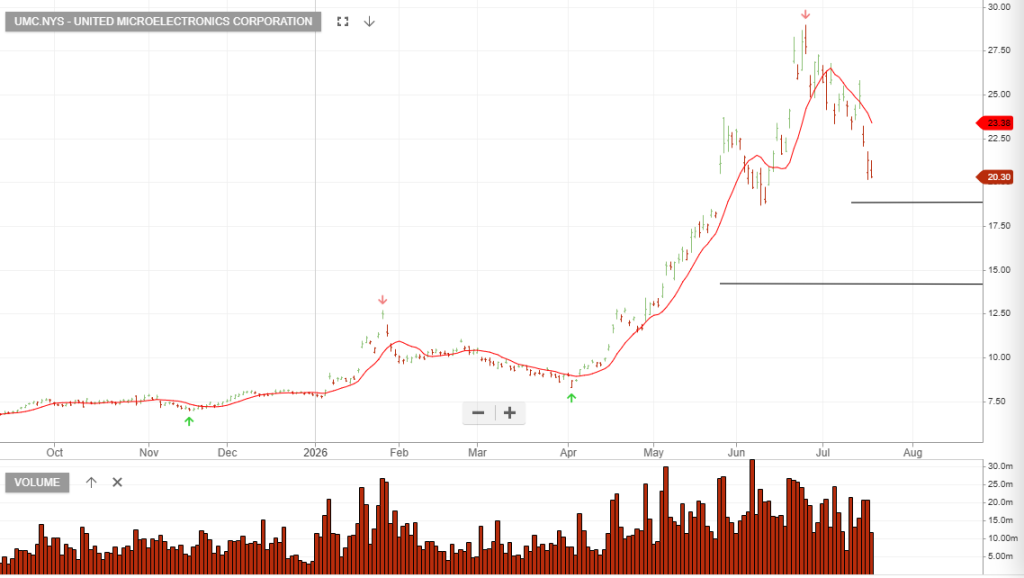
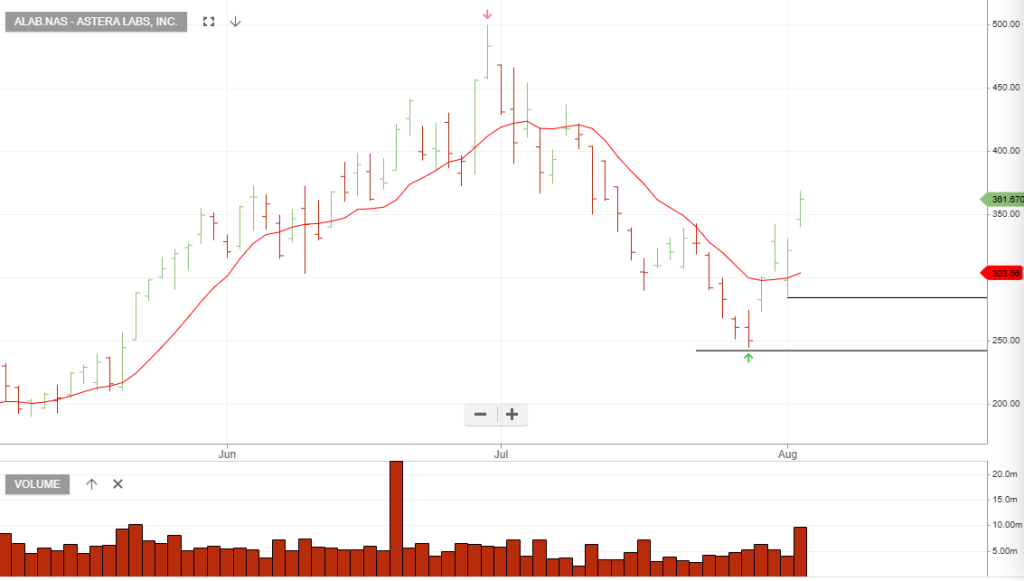
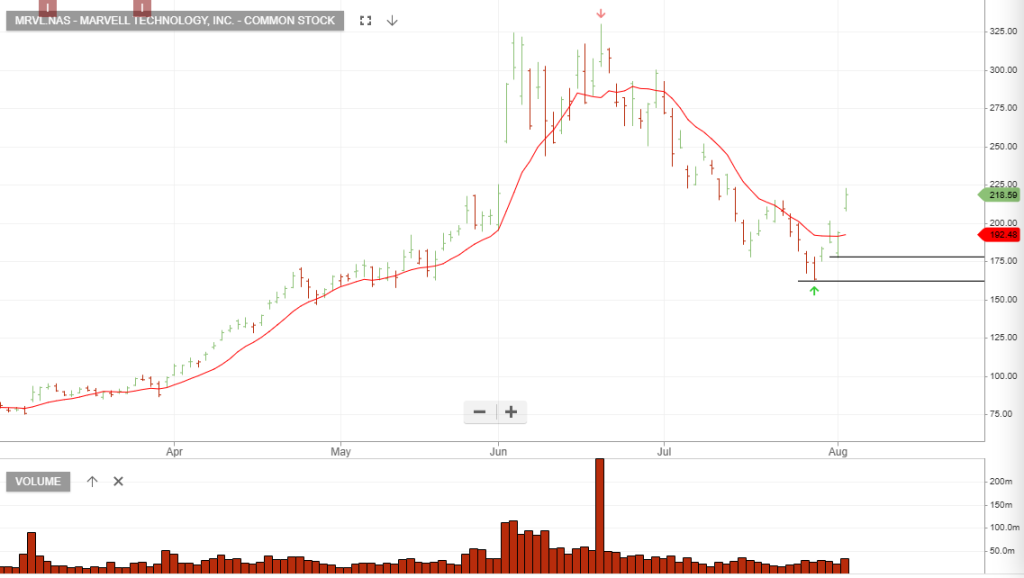
5/8 update: is rated a buy with the stop loss at $17.49
Add to watchlist and look for interest to build near $18.50
In early 2026, UMC announced a high-profile partnership with Intel to collaborate on a 12nm platform manufactured in the US. This partnership is slated for commercial production in late 2027 and vastly diversifies UMC’s geographic footprint.
Strong Balance Sheet: Fitch affirmed UMC’s BBB+ credit rating with a “Stable” outlook in June 2026. The company boasts a low debt-to-equity ratio of ~0.19 and a healthy current ratio of ~2.72.
Next Earnings Release: UMC is scheduled to report its Q2 2026 earnings on Wednesday, July 29, 2026. Analysts expect EPS of 15 cents on revenue of ~$2.06 billion, representing growth over the prior year.
Key Drivers & Long-Term Growth Outlook: Marvell’s custom ASIC program (designing tailored AI chips for cloud hyperscalers like AWS, Google, and Microsoft) and optical connectivity solutions (800G / 1.6T DSPs) remain the primary catalyst.
Accelerating Quarterly Trajectory: Management guided sequential revenue acceleration throughout FY2027, aiming for quarterly revenue to reach ~$3.0 billion in Q3 and Q4.
Full-Year FY2027 & FY2028 Targets:
FY2027 Revenue: Expected to reach ~$11.5 billion (+40% YoY growth), driven by >50% growth in the Data Center segment and >70% growth in optical interconnects.
FY2028 Target: Revenue guided toward ~$16.5 billion as cloud hyperscaler AI capital expenditure expands further.
Key Things to Watch on Earnings Day
Custom AI ASIC Shipments: Progress on hyperscaler customer design wins ramping into volume production.
Gross & Operating Margins: Non-GAAP gross margins (target zone ~59–60%) and expense control as R&D investment increases.
Hyperscaler AI Capex Trends: Any commentary on customer demand pacing for 800G/1.6T electro-optics and PCIe/CXL switches.
Supply Chain Capacity: Lead times and substrate/co-packaged optics assembly capacity.