Graincorp – Finding Support
GrainCorp is under Algo Engine buy conditions and we highlight the buying interest following the share price finding support at $7.10.
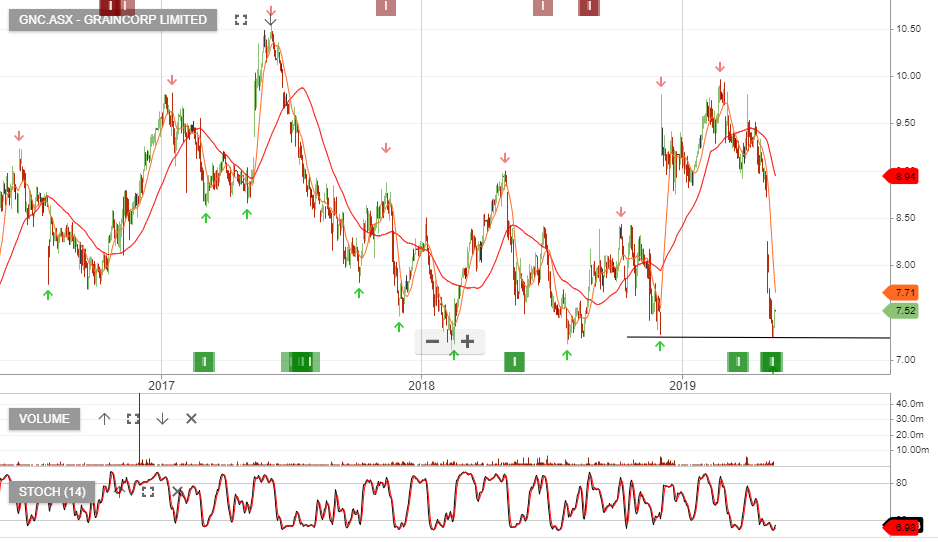
GrainCorp is under Algo Engine buy conditions and we highlight the buying interest following the share price finding support at $7.10.
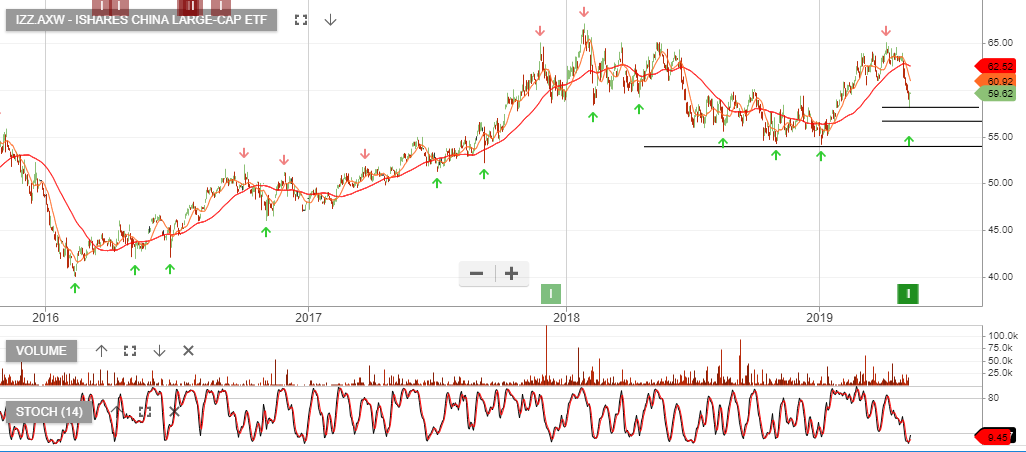
Following the approximate 10% sell-off within the various ETFs which provide exposure to Asia large cap and more specifically China, we now have a series of Algo Engine buy signals to consider.
The IZZ.AXW iShares China Large Cap and the IAA.AXW iShares Asia 50 are two high quality considerations. If investors are seeking a tilt towards the faster growth tech sector, we suggest adding the Betashares Asia Technology Tigers to your watch list.
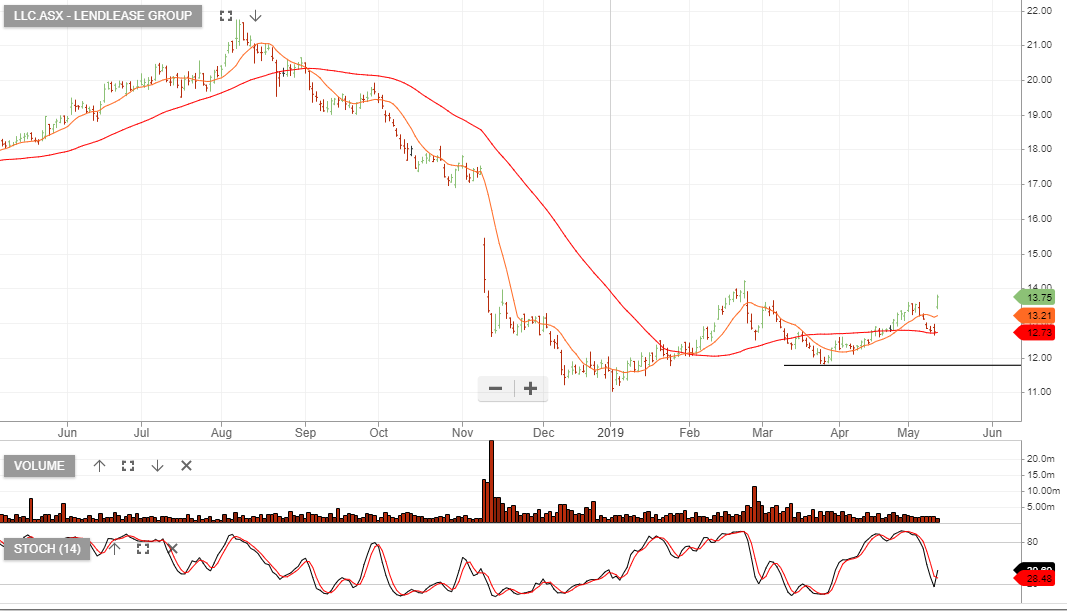
Over the past 6 months, we’ve been promoting Lendlease as a high conviction buy-side idea, based on the long-term value the business offers.
The stock price has rallied 7% this month, following The Australian newspaper reporting Japanese group Mitsui may be considering a takeover and breakup of LLC.
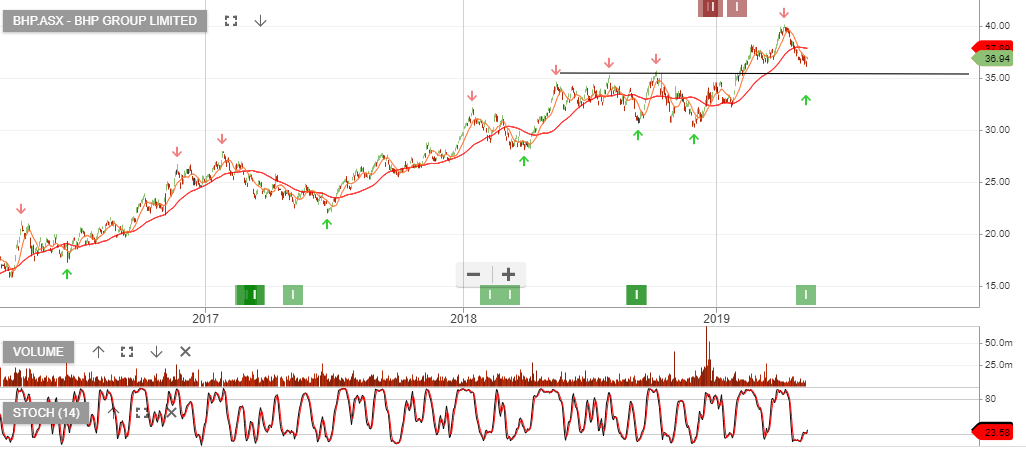
BHP Group is now under Algo Engine buy conditions following the retracement from $40 in April, back to $36 in today’s session.
Iron Ore prices remain elevated at US$93 per tone and the energy complex looks well supported from global demand and geopolitical issues with Iran.
Investors seeking income should consider adding a BHP Sept call option and stripping out the dividend, plus the call option premium.
BHP goes ex-div $0.89 on the 6th of September.
To learn more about the derivative overlay on BHP, please call our office on 1300 614 002.
Within the Energy sector we like Woodside Petroleum and Origin Energy as our preferred exposures.
WPL offers 5% franked dividend yield and when combined with a covered call option, we’re generating 10% cash flow whilst allowing for a moderate level of capital growth.
ORG offers appealing capital growth prospects as the company pays down debt and reinstates a more progressive dividend policy.
Strong oil prices and increasing LNG production numbers are tailwinds that are likely to continue for ORG. Capital expenditure is also tracking lower than guidance and these factors combined are helping to add to group cash generation.
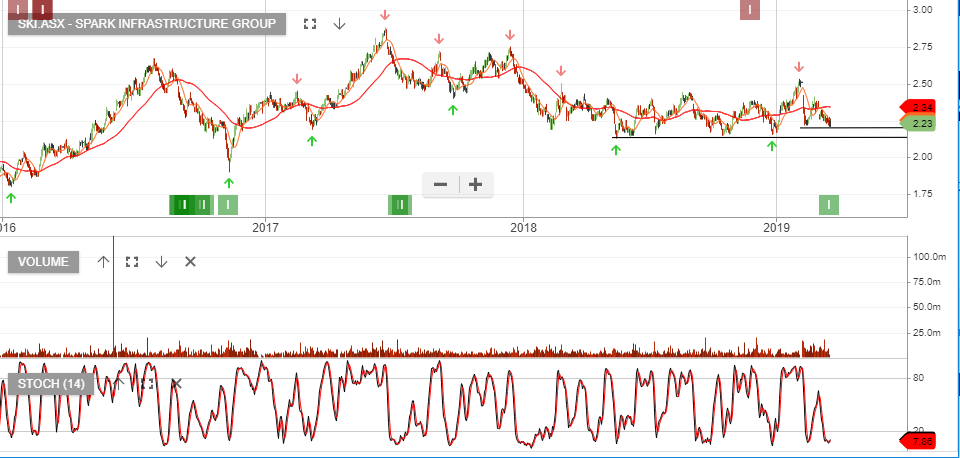
Spark Infrastructure is under Algo Engine buy conditions following the higher low formation at $2.20.
Spark Infrastructure has a long history of owning and investing in essential service infrastructure. Their networks deliver electricity to more than 5 million Australian homes and businesses.
This enters our radar and we’ll continue to review the earnings outlook and business fundamentals.
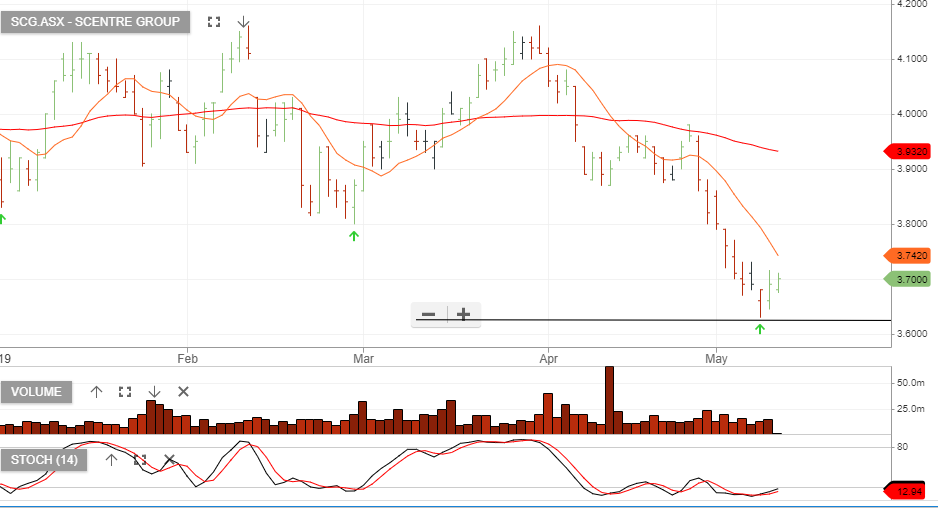
We recommend buying Scentre for a move back towards $3.90.
Once the stock is trading at our target, investors should then add a call option to enhance the income return.
SCG goes ex div $0.11 on the 14th of August.
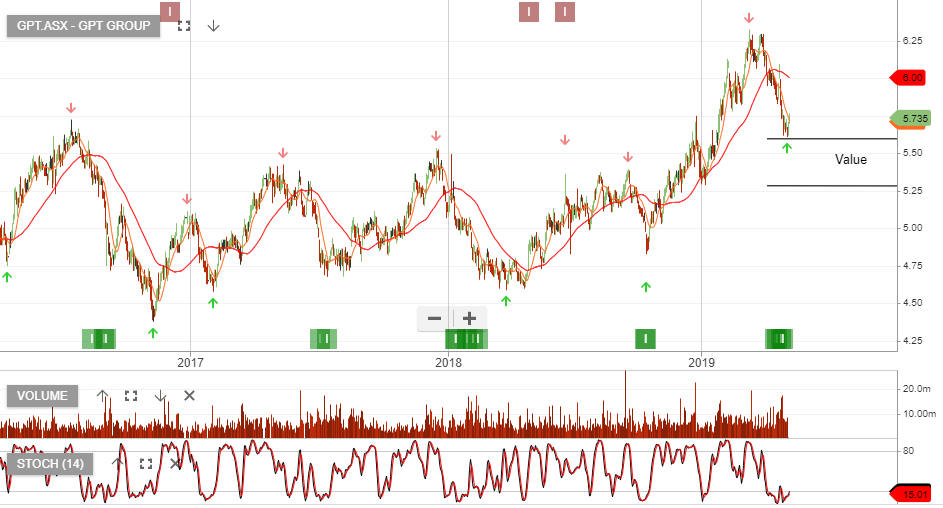
We recommend buying GPT and selling an out of the money call option to enhance the income return.
GPT goes ex div $0.126 on the 28th June.
For more information on the option strategy, please call our office on 1300 614 002.
If a picture tells a thousand words, maybe nothing more needs to be said?
Long-Term graph of the NASDAQ.
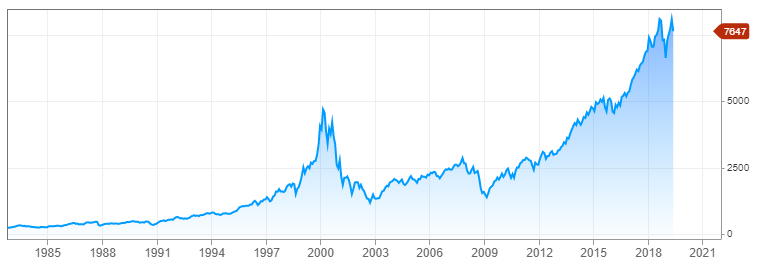
US Markets are muddling through the March quarter earnings as investors grapple with a weak earnings picture and trade tariff related issues. The bar was lowered significantly heading into the March quarter earnings season. Where consensus expectations were looking for -5% EPS growth, we’re now 75% of the way through the S&P500 earnings and the average EPS is tracking around -1%.
The graph above of the long-term pattern in the NASDAQ, highlights where investors’ concerns should be pointed. Elevated PE ratios in an environment of flat to contracting earnings could soon become a big problem, especially for technology stocks where in some instances there is little to no profit.
Short-term we’re watching the 10 day average on the NASDAQ and highlight last night’s close below the average. Longer-term, we remain cognizant of the need for the NASDAQ index to revert to the mean.
For more detail, please call our office on 1300 614 002.
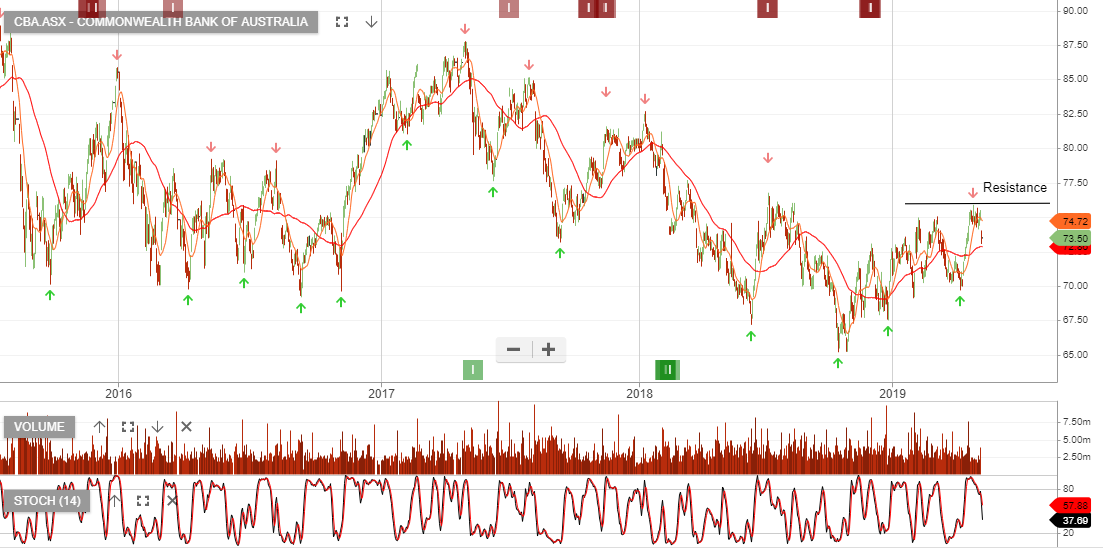
Commonwealth Bank of Australia reported 3Q19 cash earnings of A$2.2bn,
being below market consensus by 10%.
Analysts have downgraded FY19 earnings by 6%, (which incorporates the $500m post tax remediation charge), while FY20 and FY21 estimates are also lowered on weaker revenue numbers.
CBA currently trades 13x earnings on a 5.8% yield. A key risk for the business is an adverse turn in the credit cycle, which is not reflected in the current share price.
CBA has been under Algo Engine sell conditions following the lower high formation over the past 3 years.

Level 17 Chifley Tower
2 Chifley Square
Sydney, NSW 2000
1300 614 002
Investor Signals Pty Ltd
ABN 44 143 555 453