CBA – now under sell conditions
We draw your attention to the lower high formation now in place across CBA, NAB, ANZ, WBC, BOQ, BEN and Suncorp.
The lower high patterns are also in place on most of the major global banks as well.
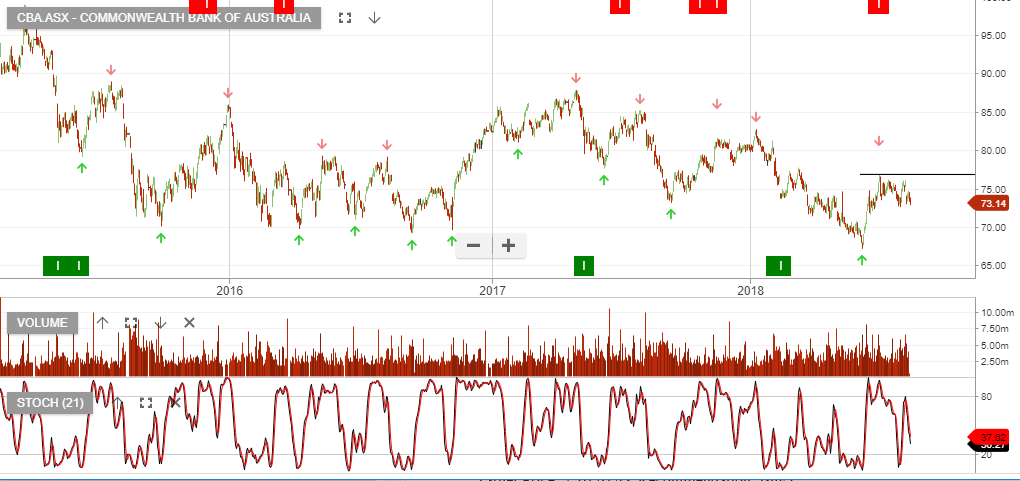
We draw your attention to the lower high formation now in place across CBA, NAB, ANZ, WBC, BOQ, BEN and Suncorp.
The lower high patterns are also in place on most of the major global banks as well.
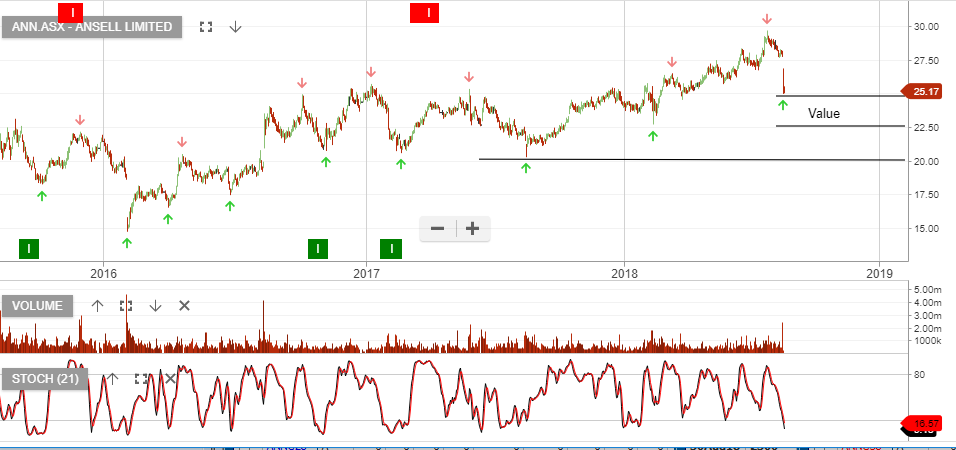
Ansell reported FY18 earnings with 5% revenue growth and 15% increase in NPAT. This represented the mid point of guidance.
FY19 looks a little more challenging, as the outlook is likely to disappoint on higher raw material cost growth.
We will watch for the next Algo Buy signal, as it is likely the market will over react and a discounted entry opportunity will soon present.
ANN goes ex-div $0.25 on the 24th August.
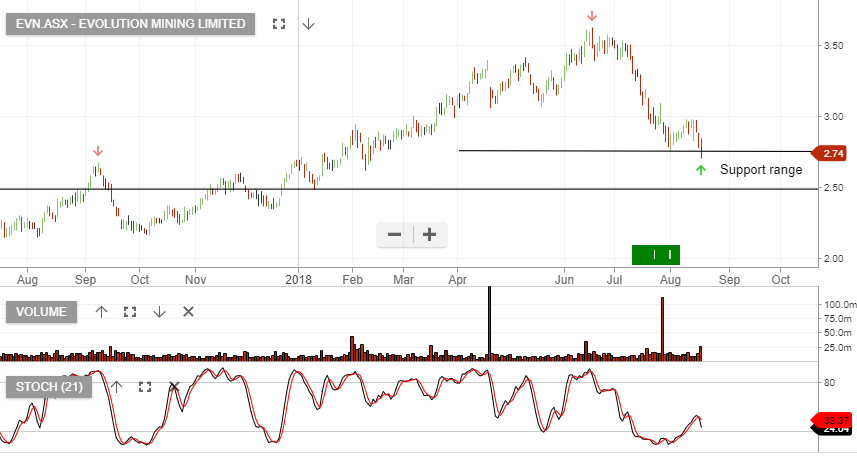
Evolution Mining reported FY18 earnings in line with consensus with revenue of $1.5b, EBITDA $795m, EBIT $360 and NPAT of $250m.
FY19 production guidance 720k-770k ounces at an expected all in cost $880oz. EVN was one of the lowest cost gold producers over FY18.
EVN declared a fully franked 2HFY18 dividend of 4c. On a full year basis into FY19, we have EVN on a 2.8% yield.
We see EVN as a buy opportunity within the $2.50 to $2.75 price range. Supported by a rebound in the oversold gold price.
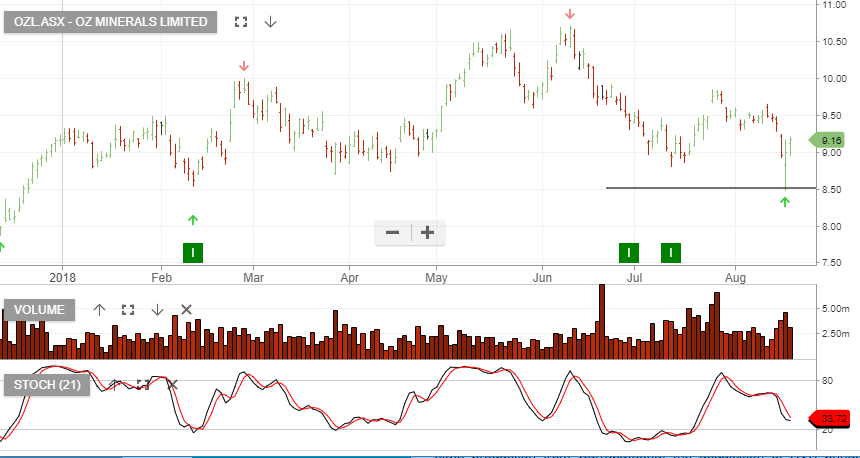
Our Algo Engine generated a buy signal recently in OZL, the stock is a current holding within our ASX100 model. We see current share price support near $8.50.
OZL announced its 1HCY18 earnings last week, with revenue reported at $534m, EBITDA $290m and net earnings $220m.
The numbers were slightly below market expectations, however, diversification of its future production base and extended mine life extensions at Prominent Hill, should underpin future earnings growth.
On a forward basis, we have OZL trading on a 2.5% yield into FY19.
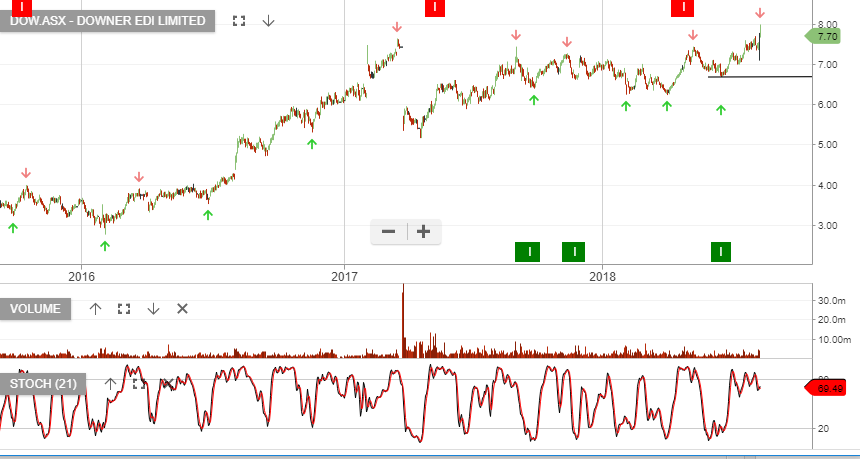
Our Algo Engine generated a buy signal in Downer EDI back in June at $6.60, with the stock price now pushing $8.00, most of the good news is priced in.
The FY18 earnings were announced on Thursday and the numbers were in line with consensus expectations. The highlight is the forward guidance of 13% growth.
FY18 NPATA came in at $296 & FY19 guidance now sits at $335m. This places Downer EDI on a forward yield of 4%.
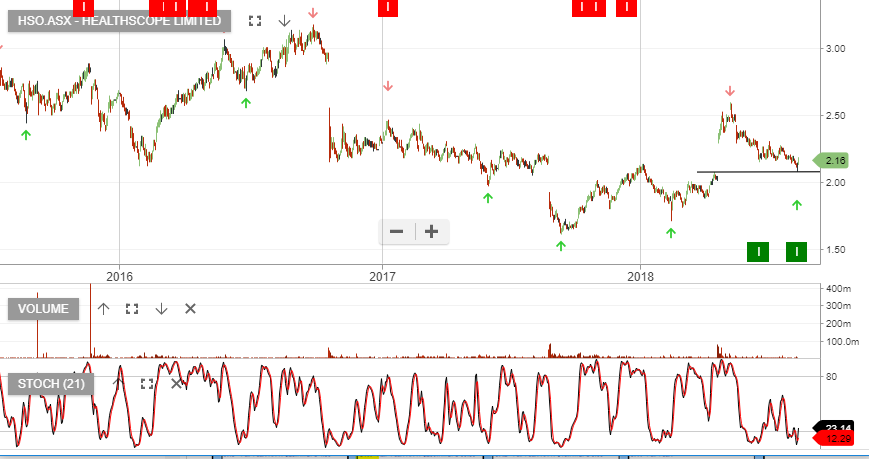
Healthscope report earnings on Tuesday and the market is looking for NPAT to increase to $170m. We’re expecting the FY19 outlook statement to support the share price.
Technically, HSO has now filled the price gap to $2.08
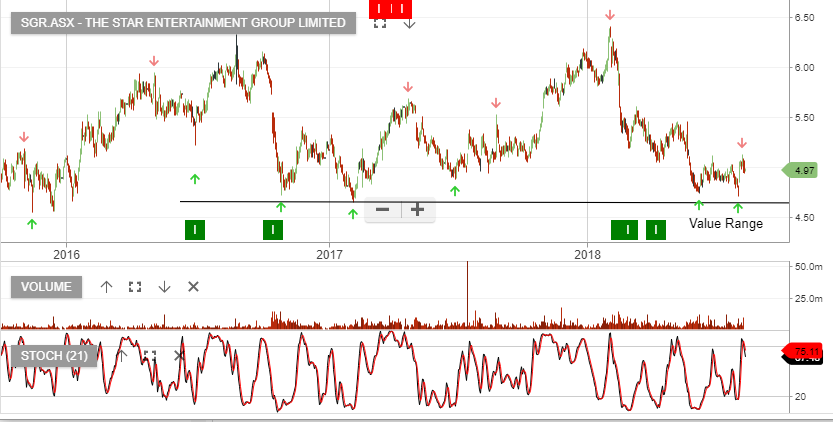
Star report their earnings on the 24th August and we expect to see stronger numbers than the market is currently forecasting.
SGR goes ex-div on the 28th August $0.085
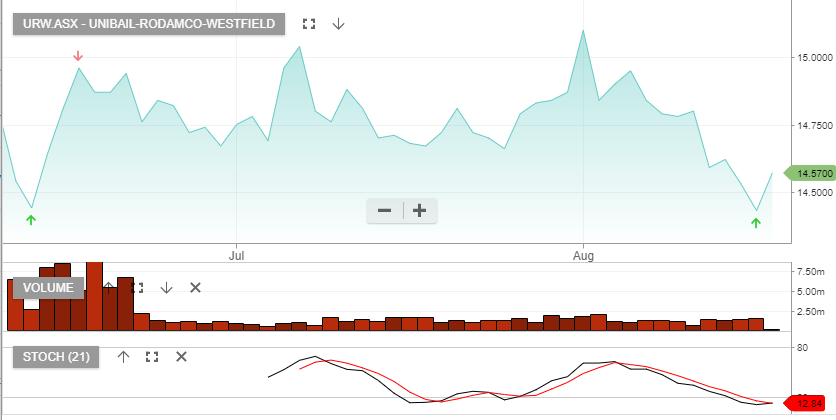
We recommend buying Unibail ahead of the 2H18 earnings release on the 29th August.
We’re expecting positive forecasts following the merger with Westfield.
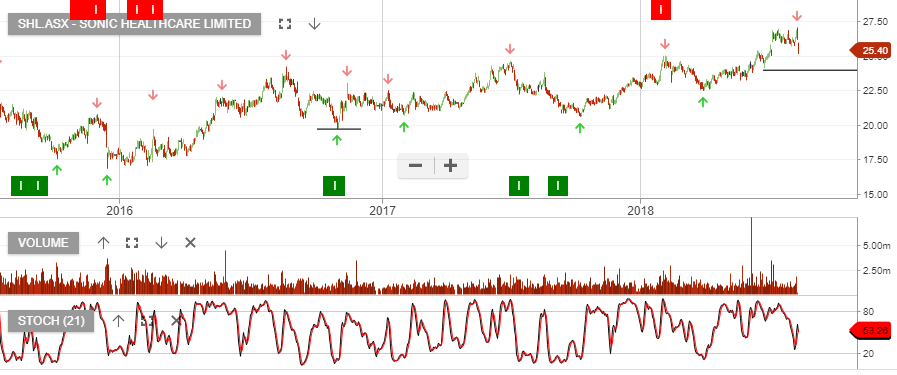
As price action in Sonic Healthcare retraces back to $25, we recommend investors look to accumulate the stock and sell covered call options to enhance the yield.
Sonic goes ex-div on the 12th September.
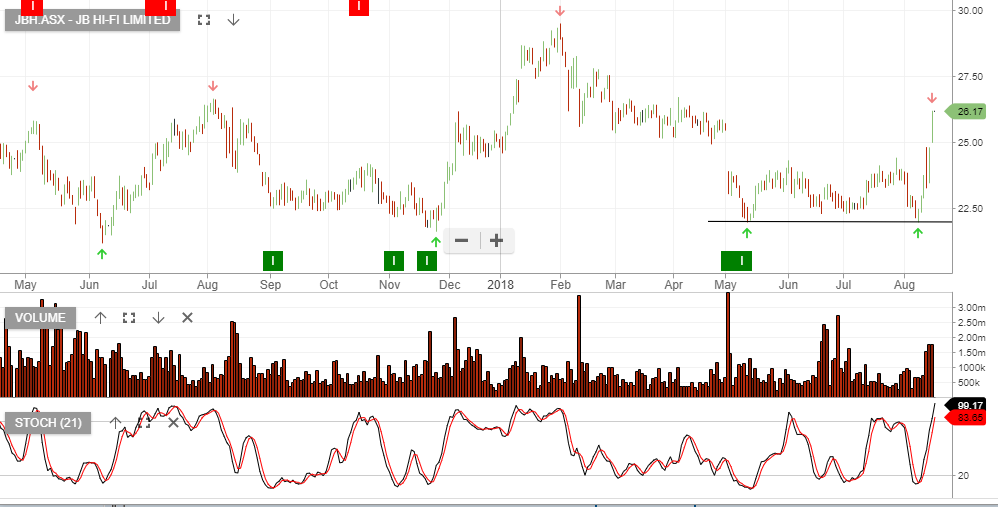
A stronger consumer environment at the back end of the financial year has helped JB Hi-Fi.
Our Algo Engine generated a buy signal recently at $22.00 and the stock was added into our ASX100 model portfolio. We continue to prefer JBH over HVN.
JBH goes ex-div $0.46 on the 23rd August.

Level 17 Chifley Tower
2 Chifley Square
Sydney, NSW 2000
1300 614 002
Investor Signals Pty Ltd
ABN 44 143 555 453