ALGO UPDATE: Woodside Is In The Buy Zone

With the company announcing a rights issue last week and going ex-dividend for 62 cents today, shares in WPL have been very active.

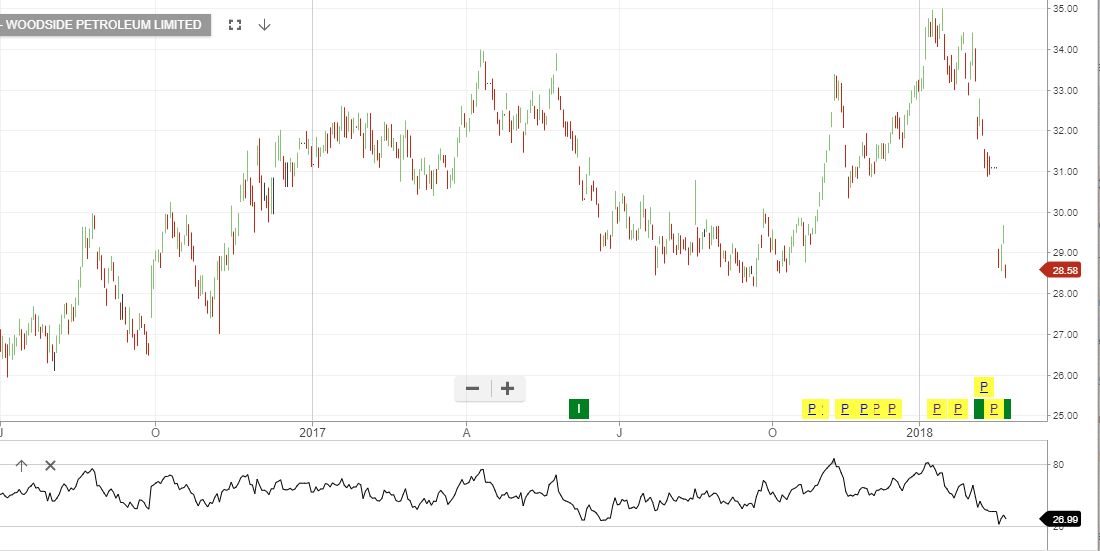
Our ALGO engine triggered a buy signal on Monday at $28.63.

This signal has a technical basis on the “higher low” structure relative to the $28.20 low posted in September and the $22.90 low from November 2016.

From a fundemental perspective, we believe the company’s decision to raise money to secure a bigger stake in the Scarborough gas field ensures steady earnings growth during 2018 and beyond.

We expect to see investor support for WPL in the $28.50 area and a move back into the $31.00 handle over the medium-term.
Woodside


CCL Has Reached The Sell Zone

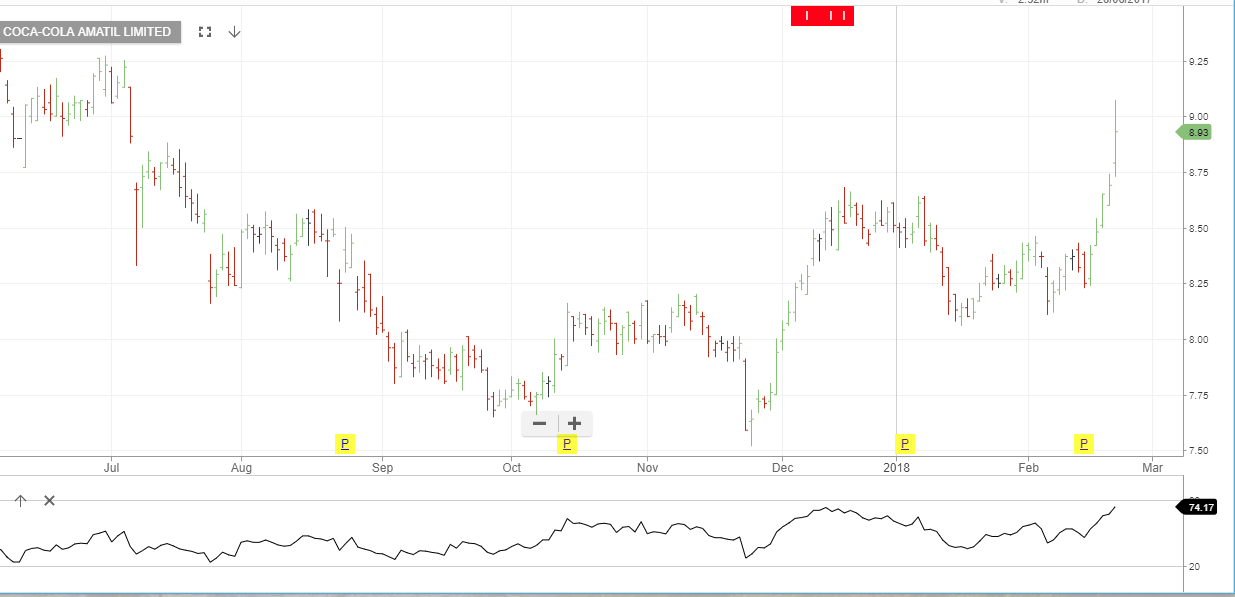
Shares of CCL are up 3% in early trade as the company announced an 80% increase in net annual profit to $445.2 million.

Despite the underlying EBIT falling .7%, the share price has reached a 7-month high of $9.07.

In a blog post last Wednsday, we highlighted the bullish technical structure and that a break of the $8.45 level could point to an extention above $9.00.

Internal momentum indicators are now overbought and we suggest exiting long positions and looking to enter again at a lower level.

The company announced a dividend of 26 cents (70% franked) and goes ex-dividend on February 27th.

The first area of technical support for CCL will be at, or around, the $8.65 level.

Coca-Cola Amatil


BHP Bumps Dividend As Earnings Slip

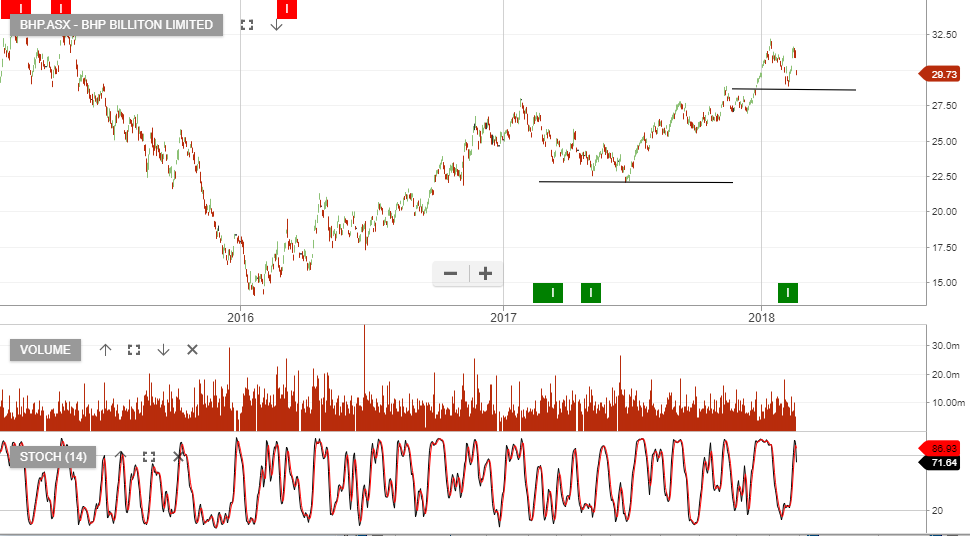
BHP’s 1H FY18 earnings result was below market expectations.

Despite the cost pressures, BHP has stepped up cash returns to shareholders, with the US$0.55 interim dividend a positive surprise in the 1H FY18 result.

FY19 revenue and underlying profit is forecast to remain flat, placing the stock on a forward yield of 4.2%.

We own BHP at lower levels and sold the $29.50 March calls for a $0.60 credit to enhance the cash flow. We continue to remain exposed to the March dividend.

BHP


QANTAS Firms Into H1 Earnings

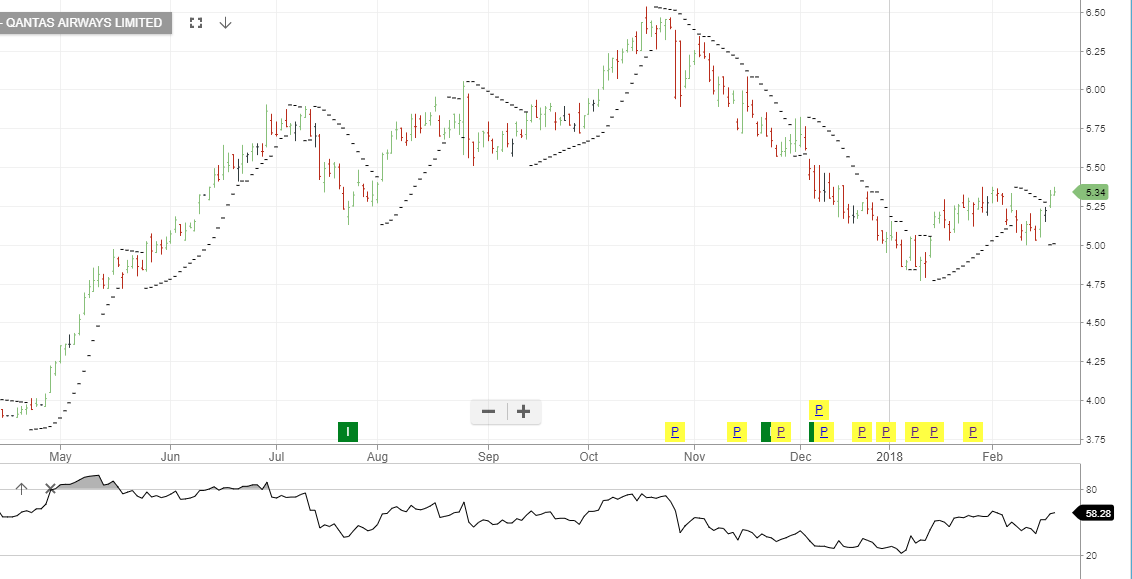
Since trading as low as $5.00 last week, shares of QAN have gained some altitude to reach $5.37 in early trade today.

The airline is scheduled to release H1 results on Thursday with the preliminary numbers showing a NPAT of $690.4 million and a DPS of 12.5 cents.

From a technical prespective, the internal momentum indicators look positive and the next key resistance level is near the December high of $5.81.

QAN was added to our Model portfolio on July 24th at $5.25, and we prefer the long side from these lelvels.

QANTAS


Tabcorp – Value Opportunity

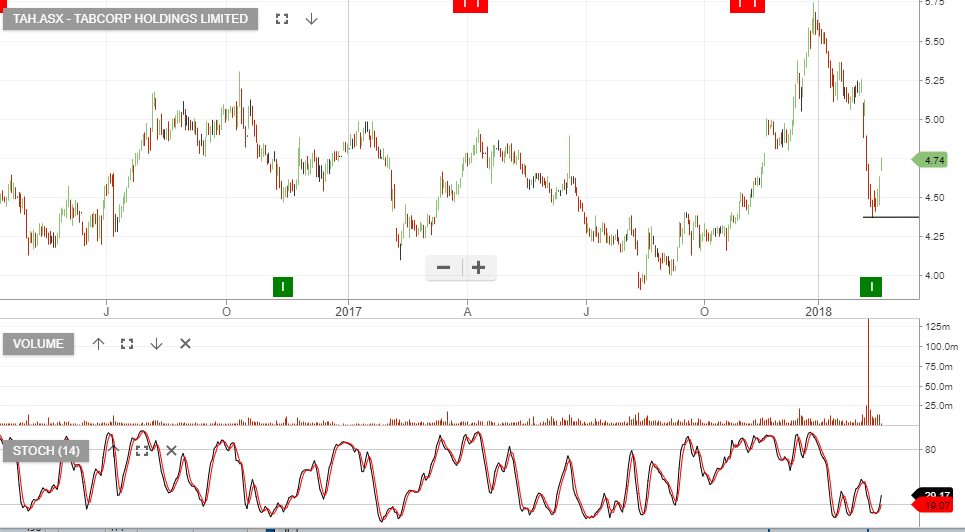
The recent drop in Tabcorp shares provides a low risk entry level where future earnings are underpinned by the $110 million synergy cost savings after the Tatts merger.

The FY19 revenue is forecast to be $5.4billion, EBIT $850 milion, EPS, $0.28 and DPS $0.23, placing the stock on a forward yield of 4.9%, (fully franked).

Our ALGO engine triggered a buy signal in TAH on February 13th at $4.47.

TAH shares have reached a high of $4.74 in early trade and we see the next resistance level near $4.90

TabCorp


Medibank Delivered 1H18 earnings

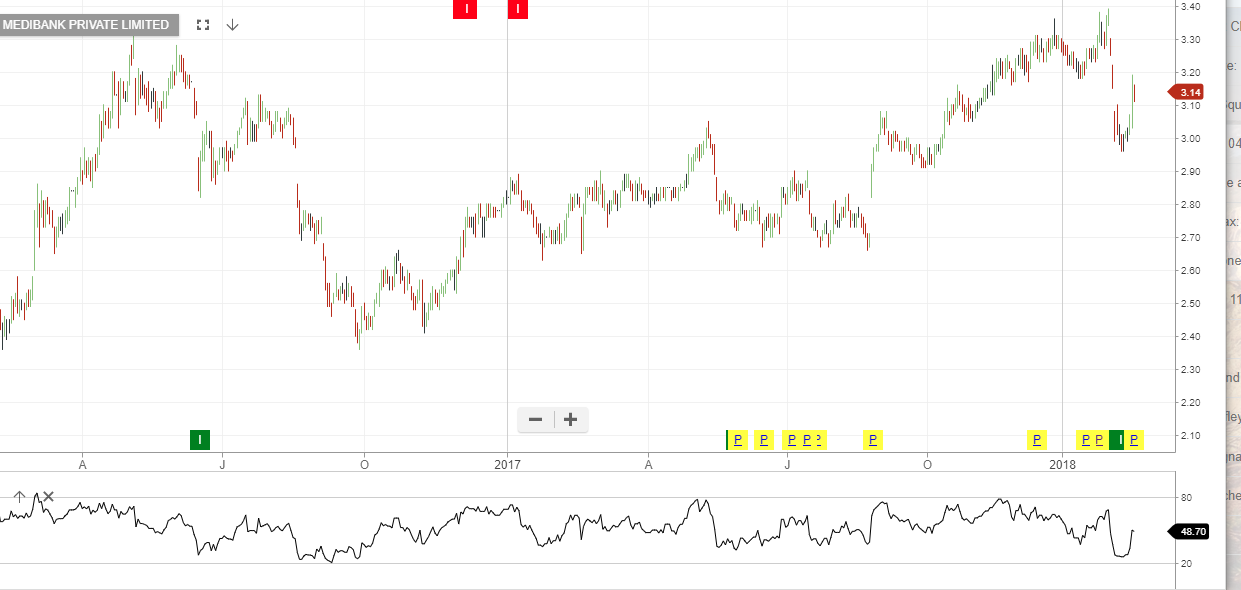
Medibank delivered 1H18 NPAT of $245 million, which is an increase of 6% versus the same time last year.

Operating conditions are expected to remain largely unchanged and we expect revenue and underlying profit to remain flat in FY19.

With the stock trading 20x earnings and 4.1% yield, investors should add an at-the-money-call option to strip out the maximum cash flow from dividends, call option premium and franking credits.

Medibank


Star and Crown Casino – Back On The Radar

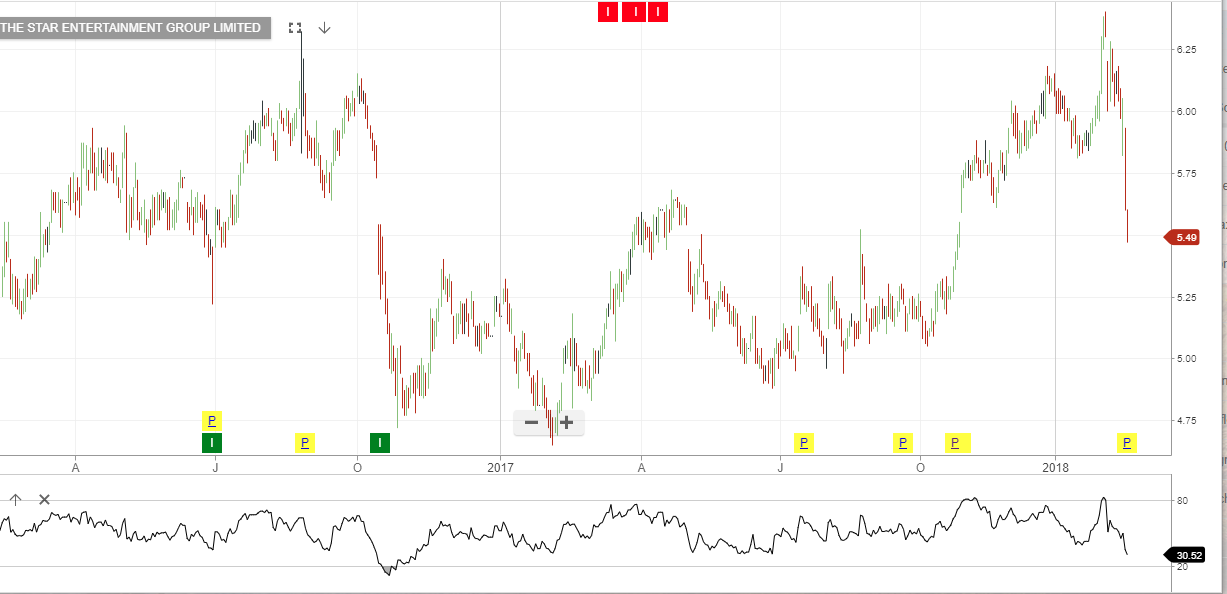
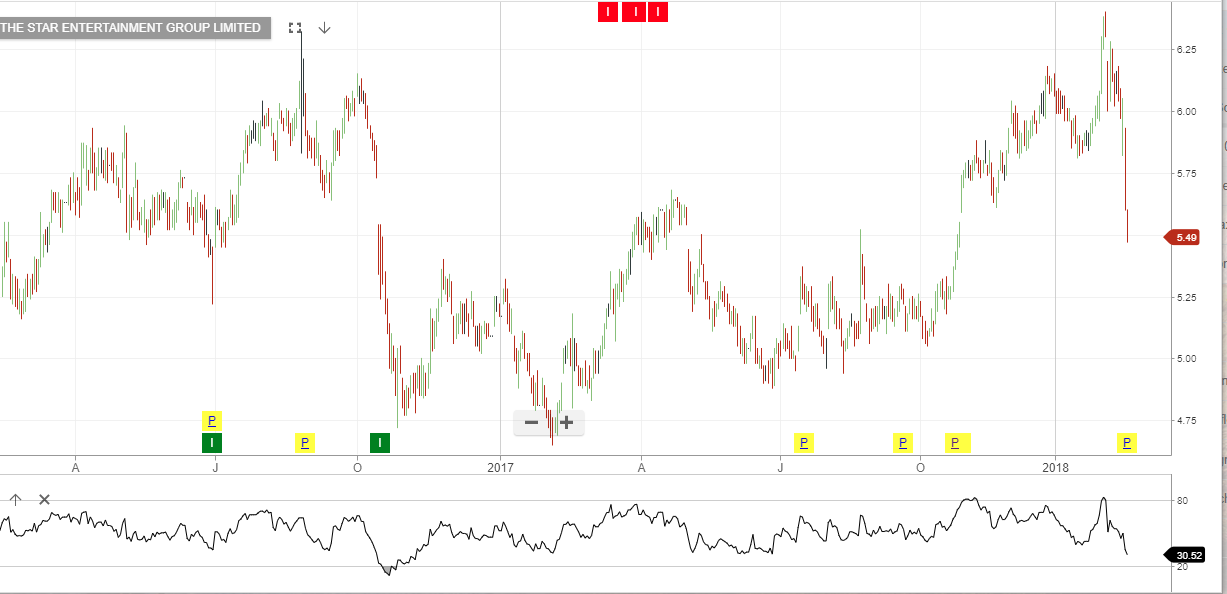
Star reported normalised NPAT of $120m, up 12% on the same time last year and revenue growth was strong, up 16%.

FY19 revenue is forecast to be $2.9b, EBIT $430m, DPS $0.16, placing the stock on a forward yield of 3%.

Investors should watch for the next Algo Engine buy signal in both Star and Crown as they approach a new higher low formation, which will provide a good entry level.

Star Casino

Crown Casino


Sonic Healthcare Firms On 1H18 result

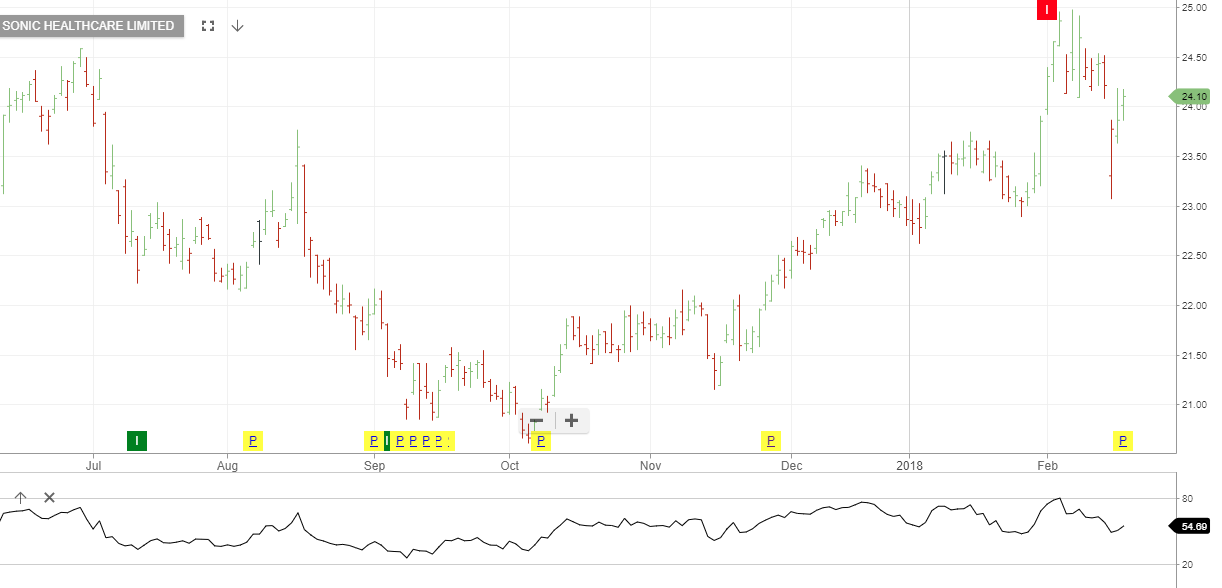
Sonic Healthcare delivered 1H18 revenues of $2.7 billon, which was up about 8% versus last year.

Group EBITDA margin missed forecasts and therefore, at 21 x forward earnings and only a 3.4% dividend yield, we view SHL as full value.

The stock was removed from our ASX 50 model a few weeks back when the Algo Engine triggered a sell signal.

Investors looking for cashflow should look to buy SHL on a pullback below $23 and then sell $24 December call options; whilst remaining exposed to the Mar and Sep dividends along with collecting the added option premium.

This strategy  delivers 12% cash flow on an annualized basis.

Sonic Healthcare