US Jobs Outlook Weakens, Debt Ceiling Concerns Continue To Grow

There were no bright spots in yesterday’s US Payroll report.

The 156,000 growth in jobs disappointed and is well below the recent averages. The back two months were revised lower by a total of 41,000 jobs.

The unemployment rate ticked up to 4.4% even though the participation rate was unchanged at 62.9%. Weekly average earnings fell from .2% to .1%.

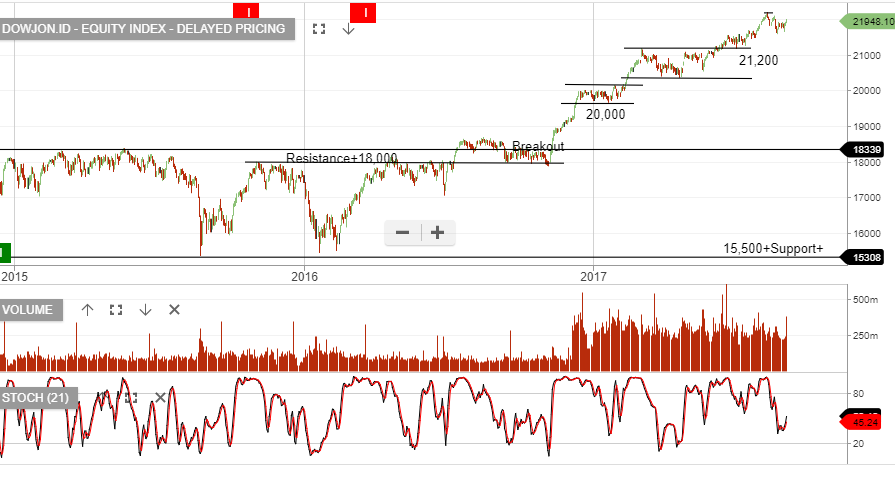
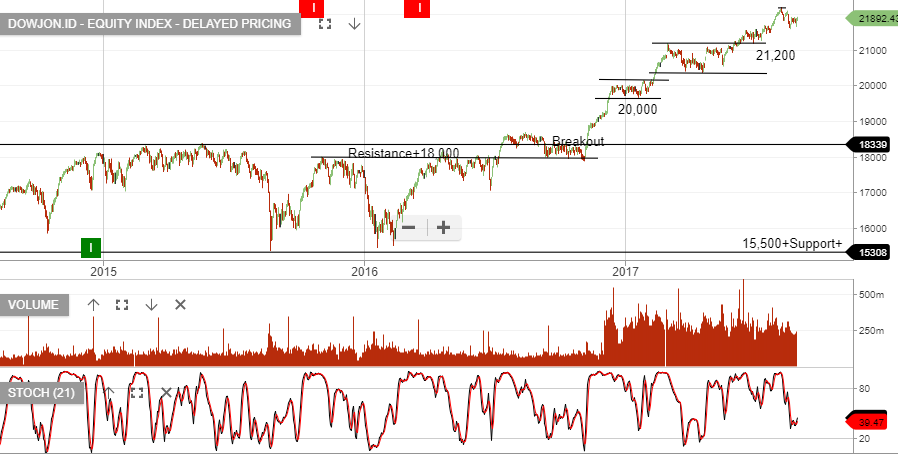
This was enough to lift US Stock Indexes higher into the weekend.

The NASDAQ had it’s best week since December 2016, finishing 2.75% higher, and the S&P 500 rose 1.5% for its best weekly performance in 4 months.

However, as illustrated in the chart below, the shortest end of the Treasury curve remains troubled as the debt ceiling panic continues to build.

And while the US 10-yr yields rose modestly to 2.16% after the payroll data, the T-Bill yield dislocation has extended out to 32 .25 basis points.

This  indicates that the market remains extremely nervous about a debt ceiling crisis over the next month, which is not bullish for US equities. 
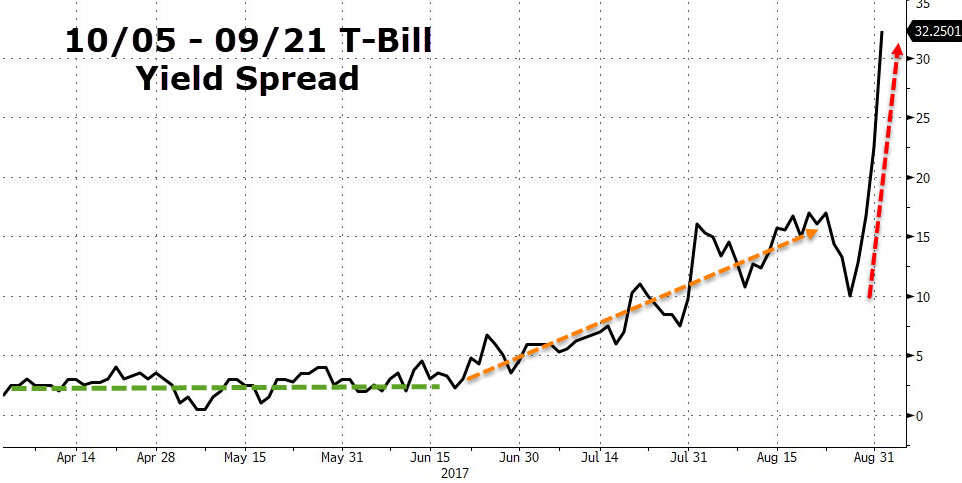
September 21st versus October 5th T-Bill yield spread
  

Algo Buy Signal in Healthcare Names

Resmed formed a “higher low” at $8.94 and found buying interest within our “buy zone”, as advised on the blog.

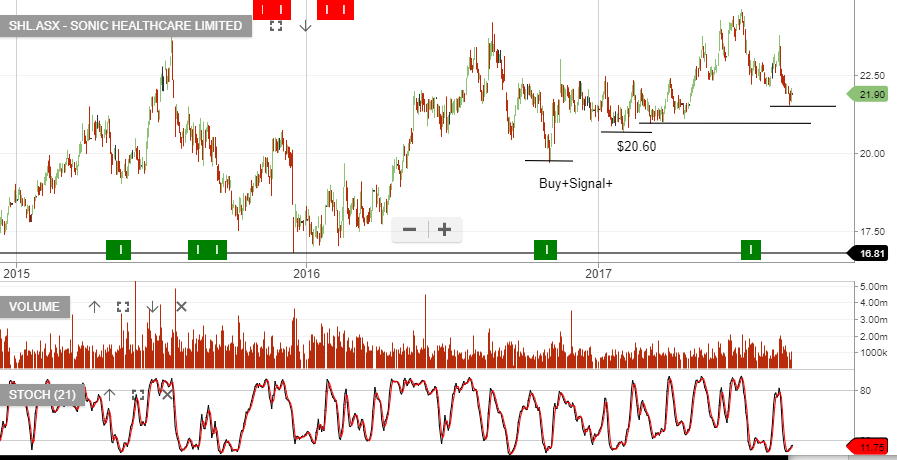
Sonic Healthcare should find buying support at $21.55. Apply a stop loss below the $21.55. SHL – Ex-Div 8/9/2017 (Div 46c, Franking 20%)

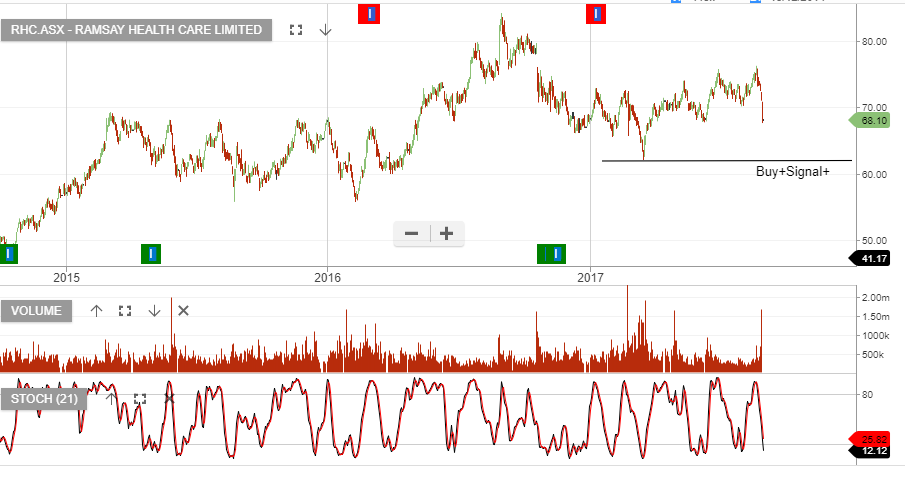
Ramsey Healthcare –  Strong reversal of yesterday’s low at $65.

CSL – Algo Engine buy signal at $125.00   CSL – Ex-Div 12/9/2017 (Div $0.91 Franking 0%)

Medibank – Now looks expensive. Take profit!


Record Levels of Margin Debt

At the end of July 2017, margin debt on the New York Stock Exchange reached an all-time high of $550 Billion. 

Prior to the 2007 market correction, NYSE margin debt peaked at 2.63% of GDP. In 2000 margin debt peaked at 2.78%.

NYSE margin debt to GDP now stands at 2.86%.

As the Fed prepares to reduce their holdings of Treasuries and MBS securities on its balance sheet, we may start to see tightening credit conditions in the U.S financial markets and a general withdrawal of market stimulus from the BOJ and the ECB.  


US GDP & 10YR Bond Yields

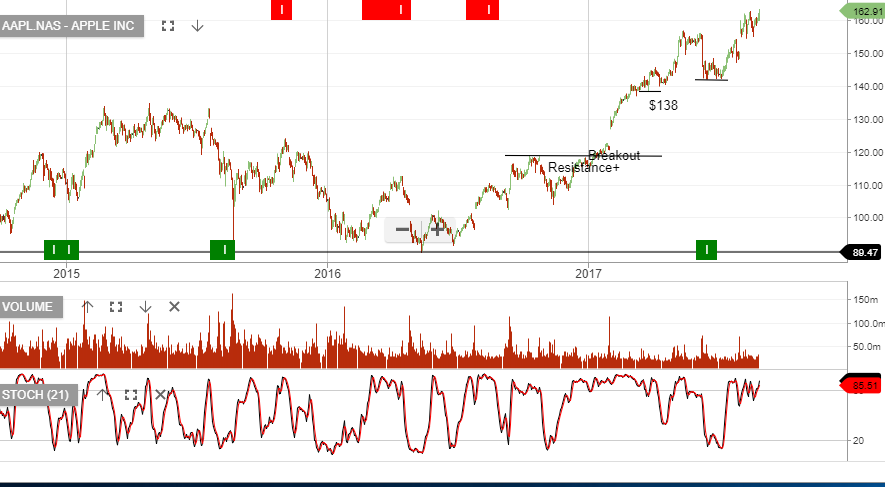
The technology sector in the US continues to perform against a backdrop of data showing stronger-than-expected growth in the US economy.

The US economy expanded at its most robust pace in more than two years in the second quarter, supported by solid consumer spending and a pickup in business investment.

GDP rose at a seasonally and inflation-adjusted annual rate of 3% in the second quarter.

Interestingly, the bond market remains less than convinced with the 10 year yields retreating to a low of 2.11%, down 50 basis points from their 2017 high of 2.64%.


Ramsey Healthcare – FY17 Earnings

Ramsey reported FY17 NPAT in line with guidance at A$543 million, up +12.7% on the same time last year. Revenue was also in line at A$8.7 billion.

All divisions contributed to earnings growth with Australia & Asia as the standout.

Assuming underlying EPS growth of 15% into FY18, we have Ramsey on a 2.2% forward yield, as dividends increase to $1.45 per share.

We view Ramsey as a strong buying opportunity on the next higher low formation, or Algo Engine buy signal.