Wesfarmers – Selling Call Options

WES has reported a slightly better-than-expected 1H17 result, with EBIT of $2.4b.

Coles’ earnings were disappointing, declining by 2.6% on headline basis or 6% after adjusting for one-off property sales. At a group level, the strong result from the industrial division and Bunnings off set the weakness in Coles.

With Coles accounting for 40% of earnings, we believe group earnings growth will be moderate (3 – 4%) and full value for the stock is $40 – $43.

FY18 we assume revenue of $71.b, EBITDA of $5.9b, Net Profit $3.1b, EPS of $2.70 and DPS of $2.10 placing the stock on a forward yield of 5.5%

With the above in mind, we are selling covered calls over WES and a combination of the dividend and option premium is generating 10 – 12% annualized cash flow.
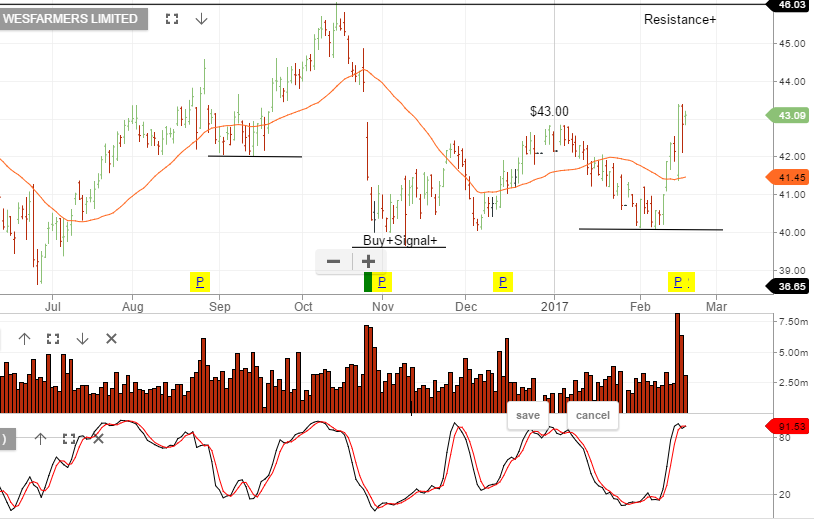
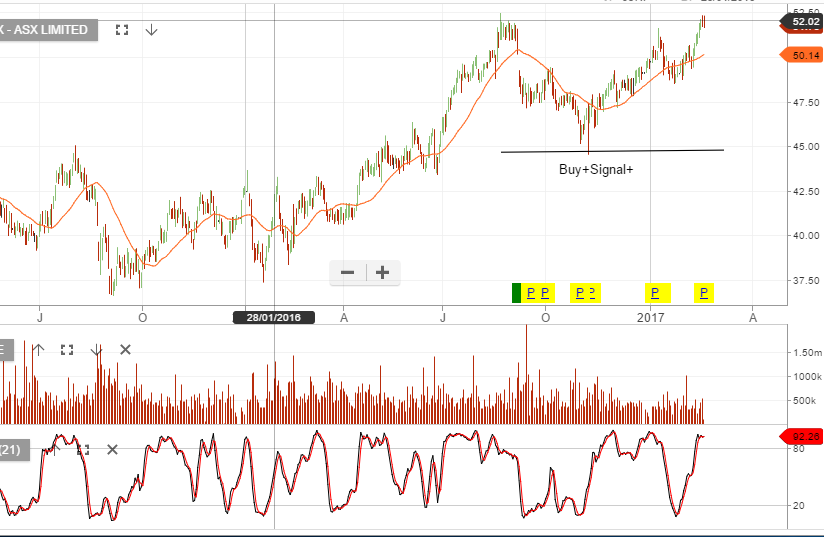
Chart – WES


Santos

After taking  a US$ 1.1 billion write-down on its GLNG project in Queensland, Santos posted a full-year loss of US$ 1.05 billion. No interim dividend was paid.

The oil and gas producer claims their free cash flow is at a Crude Oil price of US$36.50 per barrel, which is considerably lower than current levels.

The share price is essentially unchanged on the day. Longer-term investors can look for buy interest to return near the November lows at $3.50.

ASX Limited

ASX Limited reported continued profit growth for H1 2017, up 3% to $219 million. Earnings per share was posted at $1.13 per share, which is 2.9% higher than a year ago.

The exchange operator declared a fully franked dividend of $1.02 per share, which pencils out to a 90% pay out ratio.

ASX also announced a 2.8% increase in operating revenue to $386.6 million, which is a 10.4 million increase from the previous reporting period.

Solid growth in Derivatives, OTC products and the sharp increase in ETF interest has underpinned the company’s  forward guidance.

However, we see a potential “double top” pattern on the daily charts dating back to the August highs of $52.40 and would look for a pull back in the share price.

Chart – ASX

Medibank Private

Medibank Private announced its net profit rose 1.9% in the half-year ending December 31st. The profit of $231.9 million compared to the $227.6 million earned in the year-ago period.

Directors reported an interim dividend of 5.25 cents per share out of earnings per share of 8.4 cents.

However, Medibank shares are down over 3.5% today as the company announced operating profits fell 6.4% to $250 million.

Higher claims by members and amortization on a new information technology system pushed health insurance operating profits down 8.2% to $249.4 million.

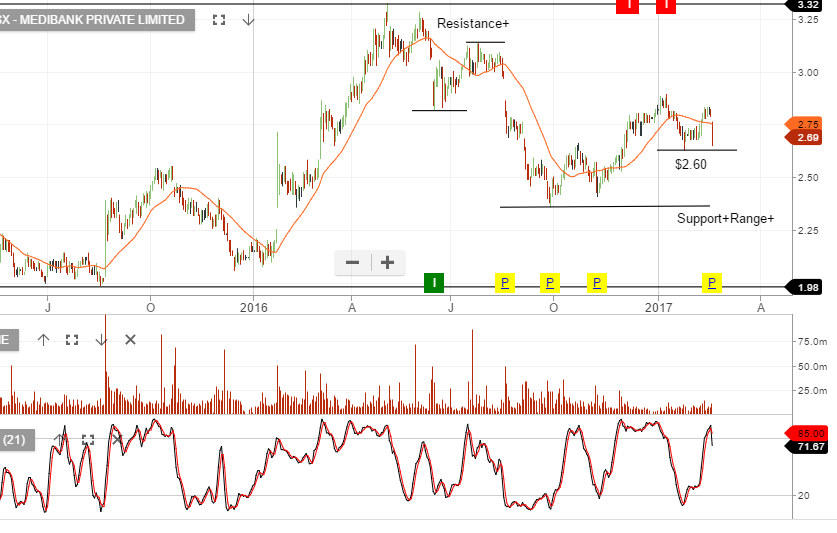
Initial chart support for the stock will be found in the $2.60 area, which will place MPL on a 4% forward yield. We own the stock in client portfolio’s and we’ve sold covered calls to enhance the yield.

Chart – MPL

Origin Energy

Shares of Origin Energy continue to slide after announcing yesterday that the company will take a $1.031 billion impairment charge on the APLNG gas export project in Queensland. This was the largest part of a broader $1.9 billion post-tax write-down.

Origin raised the bottom end of its forecast range for annual EBITDA by 3% to $2.45 billion, but kept the top end of the forecast at $2.62 billion.

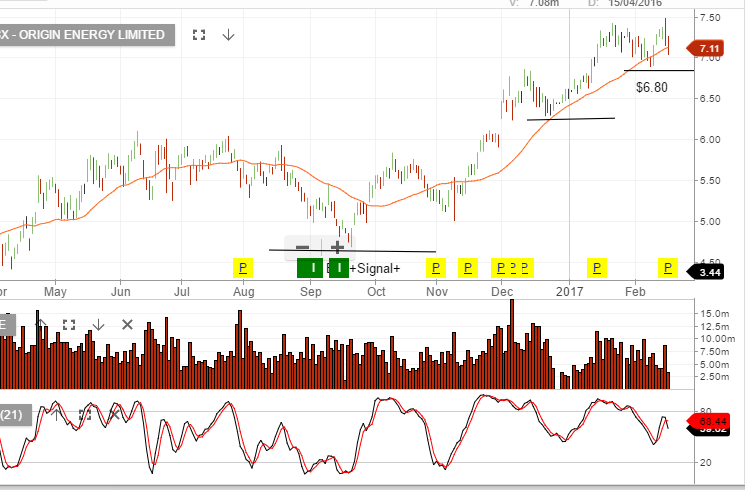
Origin shares are down over 2% so far today at $7.10. We see initial support coming in at or near the $6.88 level.

Our Algo Engine created a buy signal in September 2016 at $5.00

Chart – ORG

Sydney Airport

Stronger retail revenues helped Sydney Airports lift its 2017 guidance as 2016 annual profits were reported up 13.2% to $320.9 million.

The company announced that it will pay a full-year dividend of 31 cents per share for 2016 as total revenue climbed 11% in the year ended December 31st.

Total 2016 revenue was announced at $1.365 billion from $1.229 billion during the year ago period.

Forward guidance was higher, but slightly negative as the company forecast a 2017 dividend of 33.5 cents per share versus the street’s expectation of 34 cents per share. EBITDA rose 8.2% to $1.08 billion, and operating margins are running at 8.2%.

Total passenger numbers increased 5.6% to 41.9 million , with international passenger numbers rising 8.8% to 14.9 million.

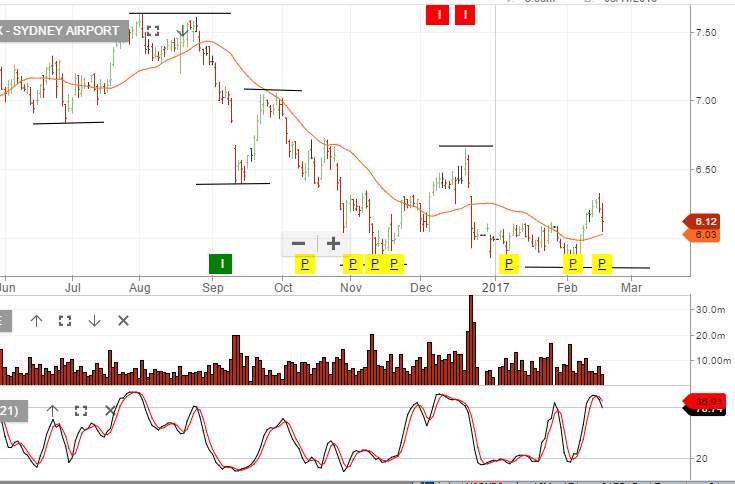
Technically, the share price should find support at the $6.00 area, which is also the 30-day moving average.

Our Algo Engine created a short signal in December at $6.70.

Chart – SYD

Telstra Disappoints

Telstra shares are down over 4% in early trade as Australia’s largest telecommunication company announce half-yearly profits down 14.2% and revenue 3.6% lower.

The company reported half-yearly profits of $1.79 billion compared to $2.09 billion this time last year. Revenue fell to $12.8 billion from $13.3 billion over the same period of time.

Their EBITDA of $5.18 billion was at the low end of earlier guidance, which is a sign that Telstra is undergoing a difficult transition to the post-NBN world.

The company announced an interim dividend of 15.5 cents per share, fully franked, which returns $1.8 billion to shareholders.

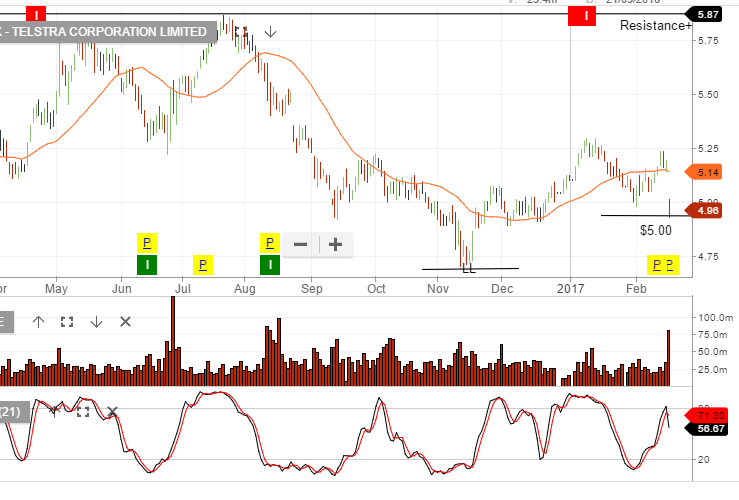
Our Algo Engine created a short signal in January at $5.27

Chart -TLS

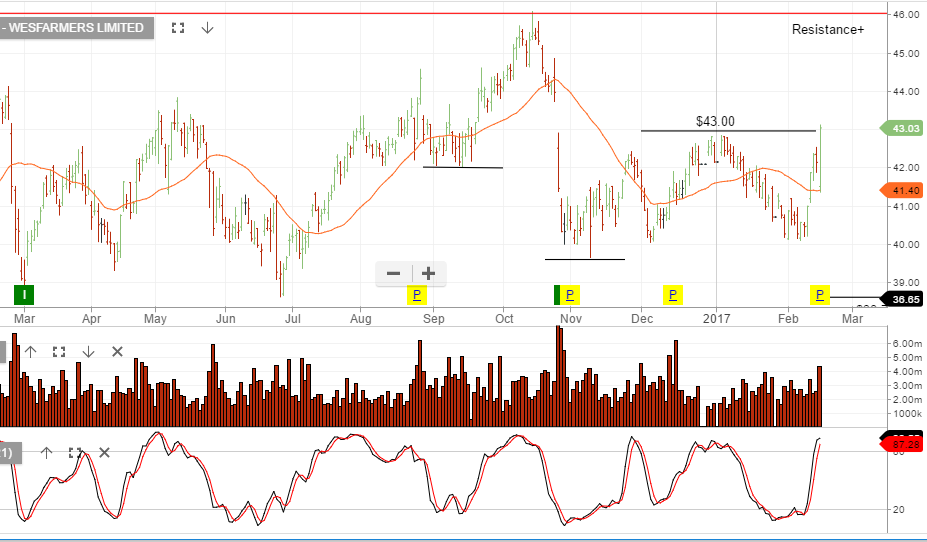
Wesfarmers

Wesfarmers‘ officials have credited their conglomerate structure for a 13.2% increase in half-year net profits to $1.57 billion. This result was well above the street’s expectation of $1.47 billion.

The company announced it will increase its interim dividend to $1.03 from 91 cents, payable on March 28th. Wesfarmers’ revenue grew by 4.3% to $34.9 billion, and EBIT were up 15.1% to 2.42 billion.

The strongest results from the conglomerate came from the industrial division, where earnings rose from $22 million to $377 million, largely from the $256 million turnaround in resources as coal prices moved higher during the quarter.

On the other side of the ledger, Coles’ same store sales grew by 1.3%, but lower prices meant revenue from the supermarket remained steady and earnings fell 6.8% .

Chart – WES

Commonwealth Bank

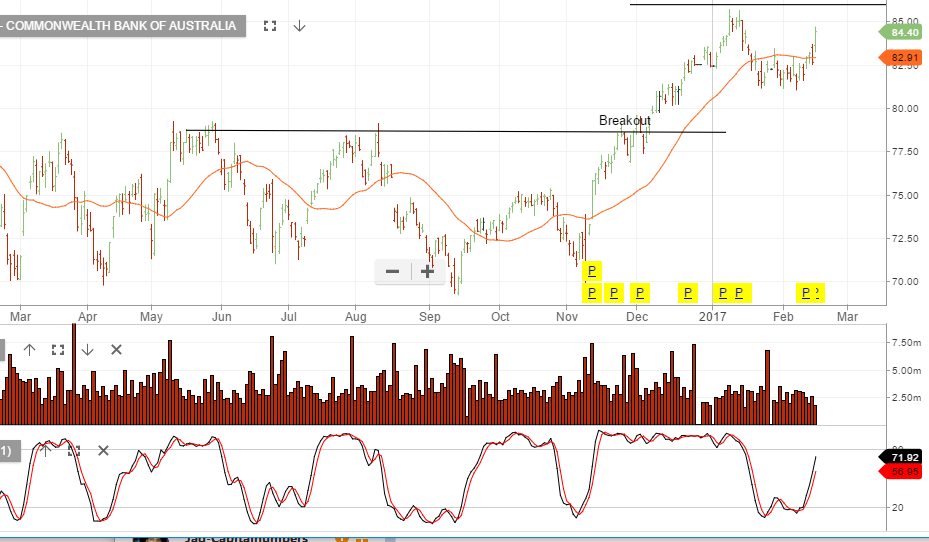
Shares of Commonwealth bank have opened 2% higher to $84.50 after reporting a record first-half profit of $4.9 billion.

The result was 6% higher than the previous record reported in the first half of last year. An interim fully franked dividend of $1.99 was declared, which was 1 cent higher than expected.

Upside price momentum could be tempered as the bank announced net interest margin was lowered to 2.11% from 2.15% and their wealth management division saw a net profit drop of 34% compared to the same period last year.

Chart – CBA

Treasury Wine Estates – 1H17 Earnings

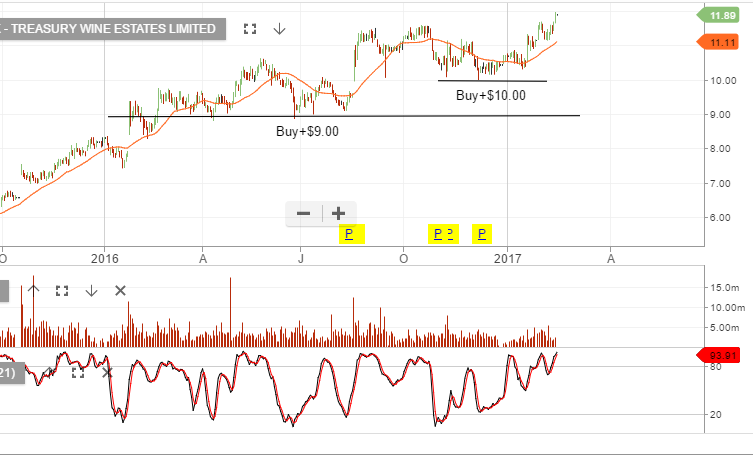
TWE has reported its 1H17 EBITS of $227m, underlying NPAT was $136m  and an interim dividend of$0.13

Assuming 2H17 is in-line with the first half, we expect a full year result slightly above consensus, which currently sits at $440m

FY18 revenue $2.6b, EBIT $490m, EPS $0.42 and DPS of $0.28, places the stock on a  forward yield of 2.4%

Chart – Treasury Wines