REA Group is up 57%

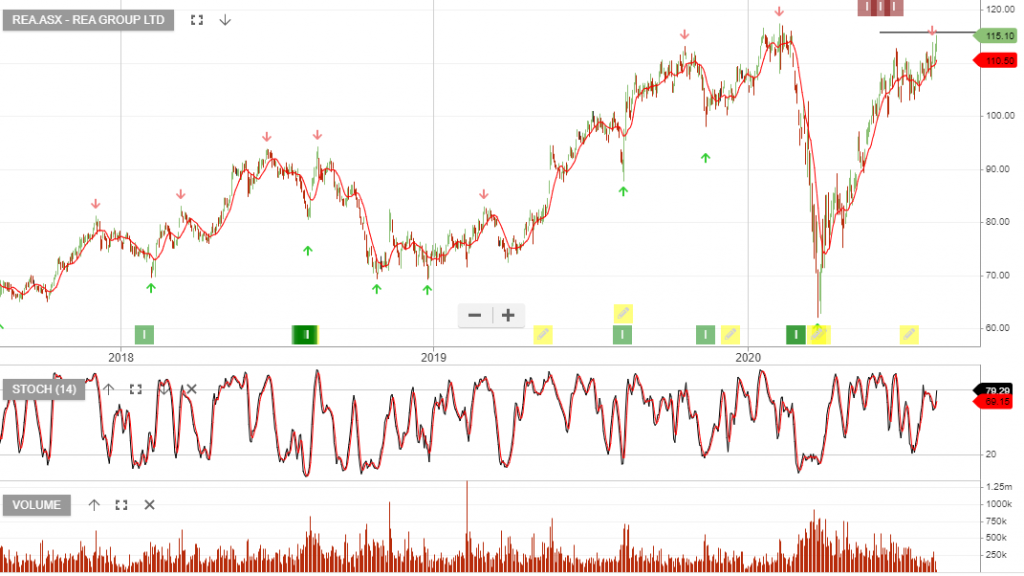
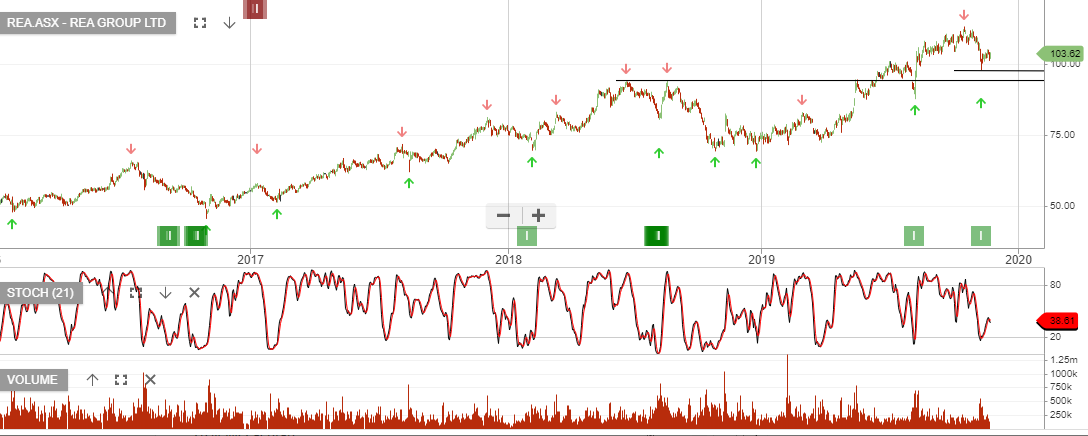
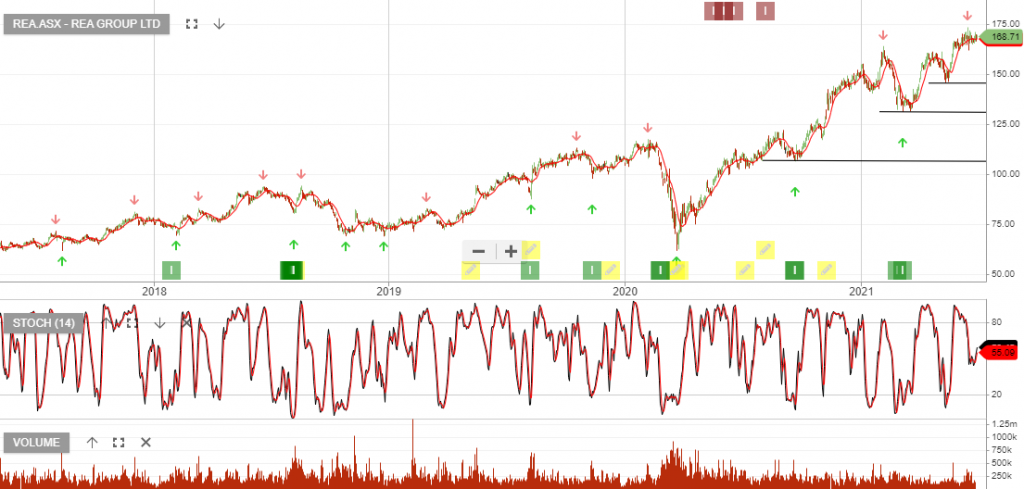
REA Group is among the best-performing stocks in our ASX 100 model portfolio, with the share price up 57% since being added in September last year.

REA Group has acquired 100 percent of the shares in Mortgage Choice for $1.95 a share, valuing the company at $244 million. REA is now focused on accelerating its financial services strategy to become a leading player in the home loan market.

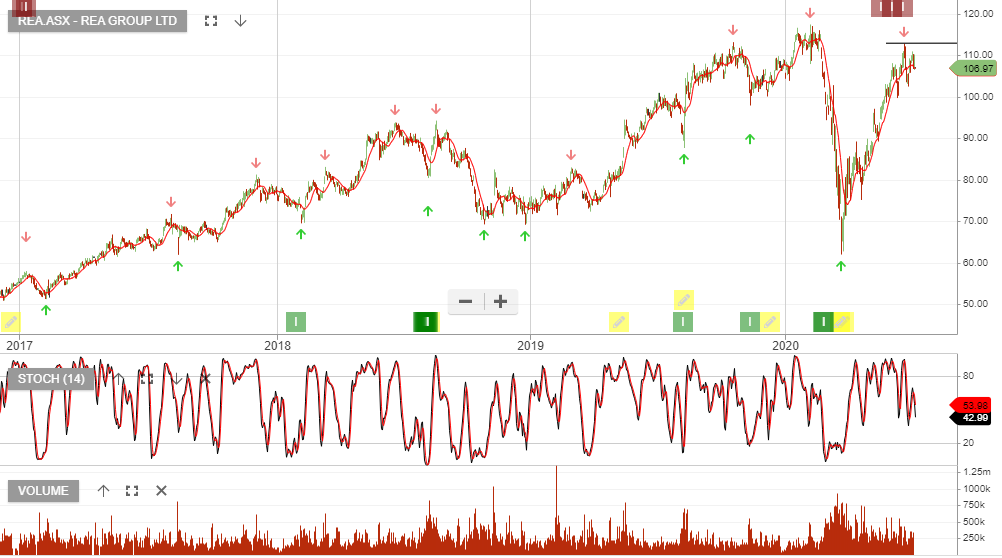
REA is a high quality business with terrific growth potential, however, the 65x PE multiple is a little rich and we recommend waiting for the next Algo Engine buy signal.
REA Group – Earnings

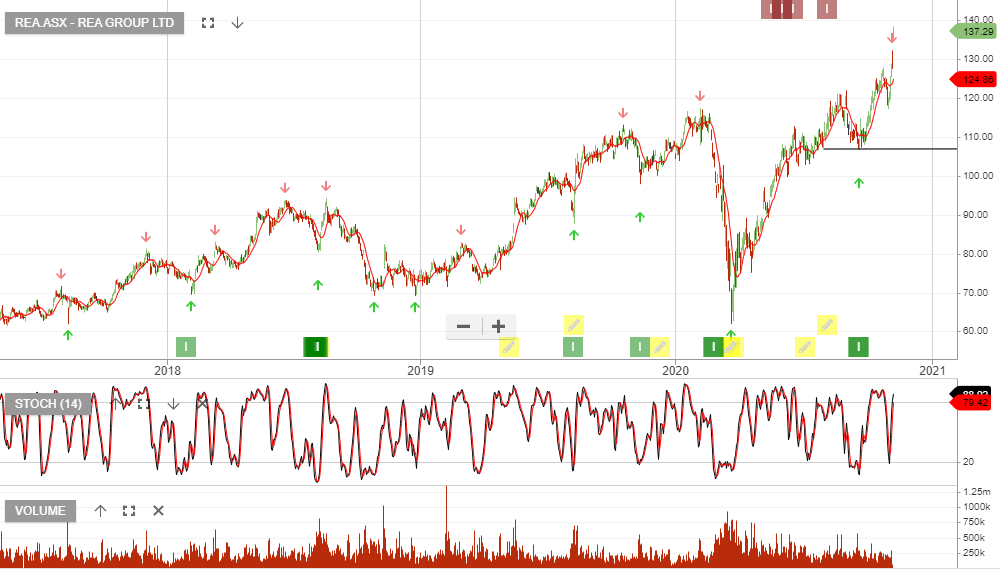
REA Group is under Algo Engine buy conditions since switching in mid-September at $106.

REA has reported 1Q21 results ahead of analysts estimates with revenue of $196mn nd EBITDA of $124mn.

Although the management outlook statement remains positive, we have some concerns about valuation and consider the stock near resistance.

REA Group – Value Has Emerged

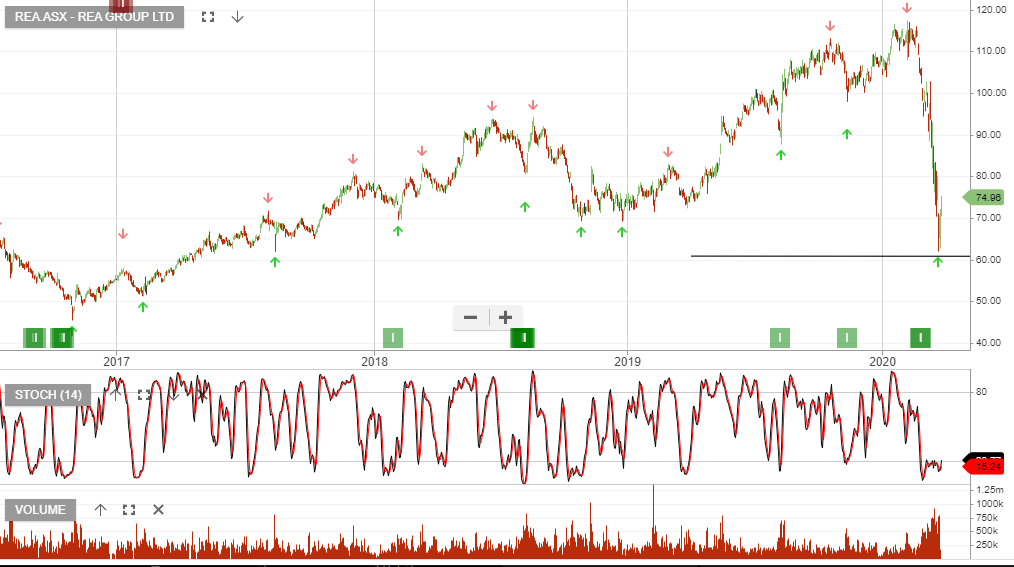
REA Group is under Algo Engine buy conditions and is a current holding in our ASX 100 model portfolio.

The share price has corrected over 40% due to the impact of COVID-19. Earnings will decline over the coming months as restrictions impacting open homes and slower vendor listings bite in the short-term.

In the medium term, we see scope for a full recovery in the business and therefore, the current share price at 20x forward earnings looks attractive.


REA – Rallies 5.5%

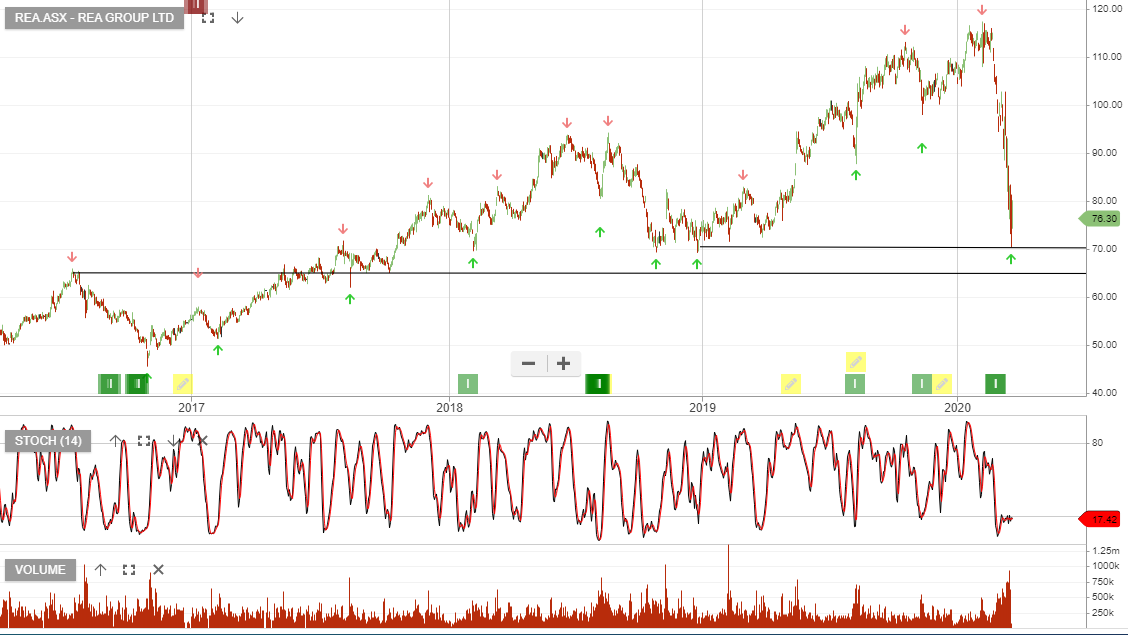
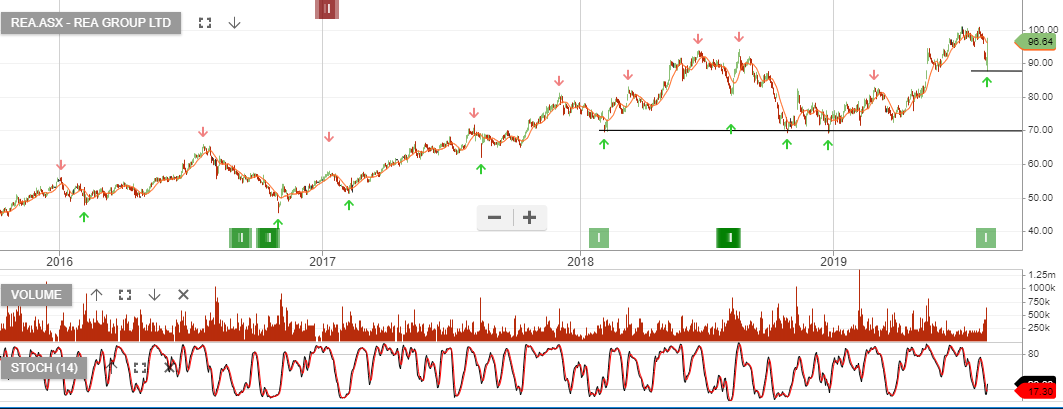
REA Group rallied 5.5% on Friday following a better than expected earnings result. Our Algo Engine triggered a buy signal Thursday after 3.30pm going into the market close.

The chart below shows the entry signal, along with the $87 support level where buying interest began to accelerate.


REA Group – Valuation Review

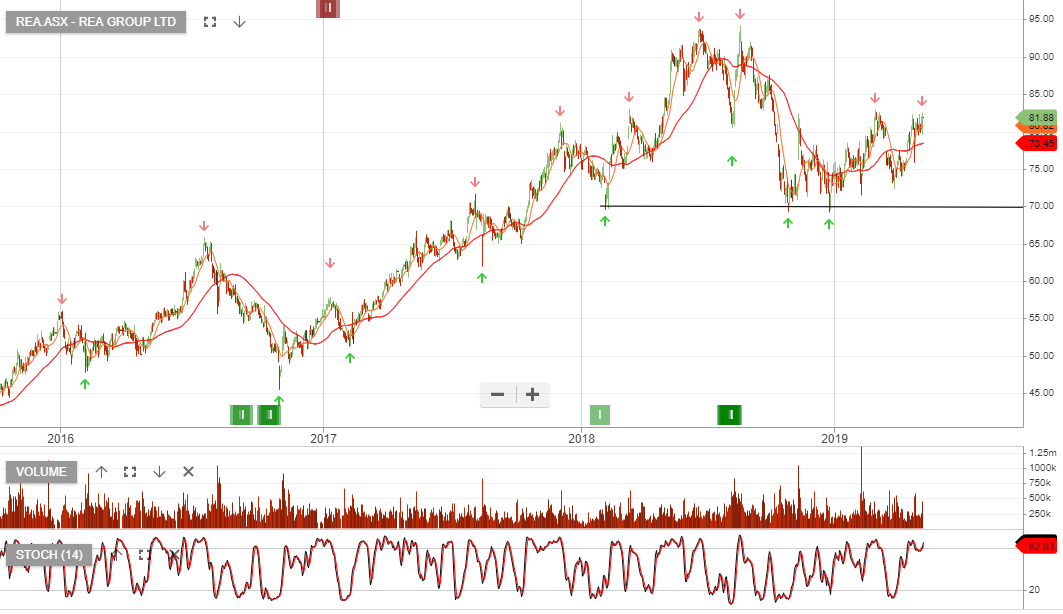
REA Group is under Algo Engine buy conditions and is a current holding in our ASX 100 model portfolio.

REA Group announced that its results for the nine months ended 31 March 2019. Reported 3Q revenues up 7% and EBITDA up 6%. The result highlights the quality of the REA business, with solid growth despite a very challenging macro environment.

If we assume FY20 revenue of $990mn, EBIT $520mn and DPS of $1.50, it places REA on a forward yield of 1.8%.

Underlying earnings growth in FY20 is forecast to be up  12%.


REA – Algo Update

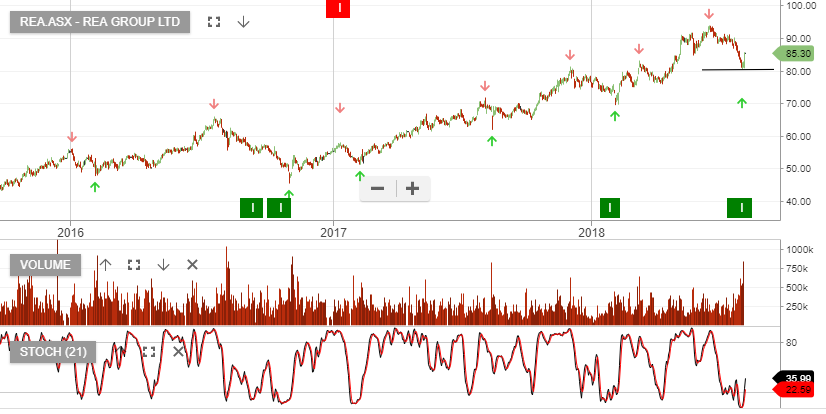
Our Algo Engine generated a buy signal in REA last week at $80.50.

Since then the stock has rallied almost $5.00, following a solid FY18 earnings result which met consensus forecasts.

Revenues were reported at  $808m, EBITDA $464m and NPAT from core operations $280m.

In FY19,  the market is looking for 15% revenue growth, flowing through to similar underlying earnings growth. This places REA on an FY19 forecast yield of 1.8%.

Despite, risks in soft listings and developer pipeline, we recommend maintaining long exposure to REA and applying a stop-loss below the recent $80.50 low.

REA