Crown Resorts – up 10%

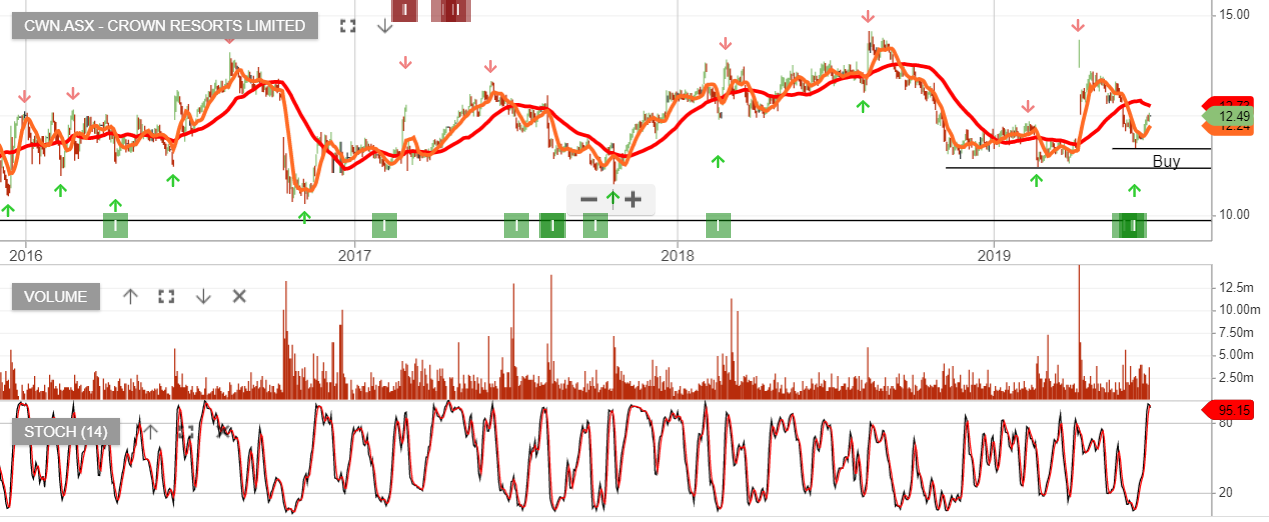
Crown Resorts has been a high conviction buy expressed on the blog. The share price made a low at $11.69 and is now trading at $12.80.

Following Melco Resorts (NASDAQ listed) buying 50% of James Packer’s holding in Crown at $13 per share, we see scope for increased VIP flow from Melco’s large high roller customer base.

Whilst there is scope for Melco to make a full takeover of Crown, it is not our base assumption. We suggest investors hold Crown for the 4.5% yield and for those seeking greater cash flow, selling an out of the money covered call option will boost the annualised cash flow to 10% plus.


Scentre Group – Algo Update

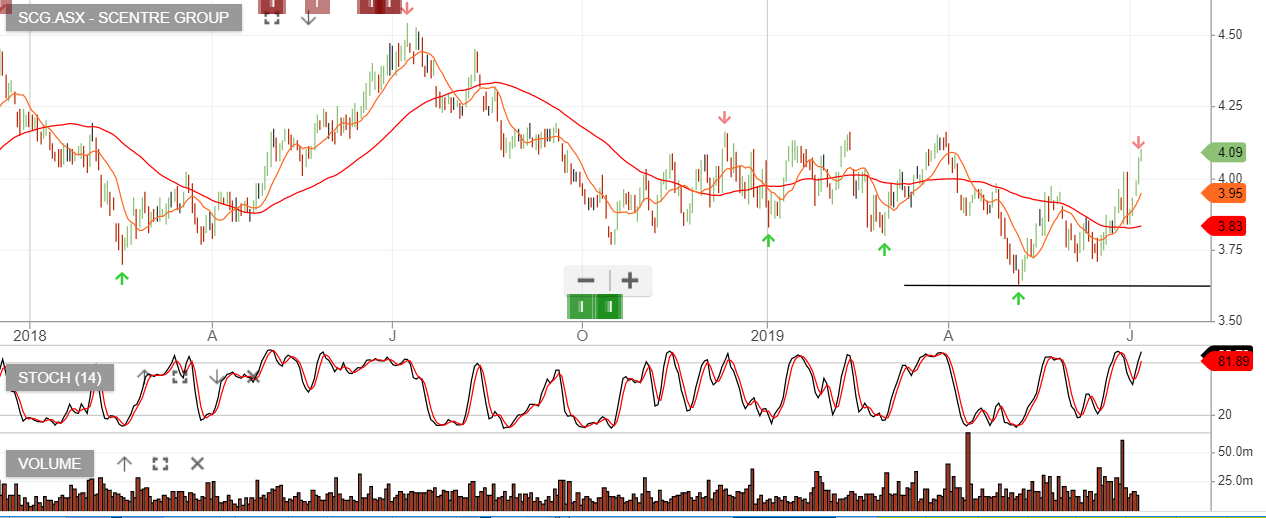
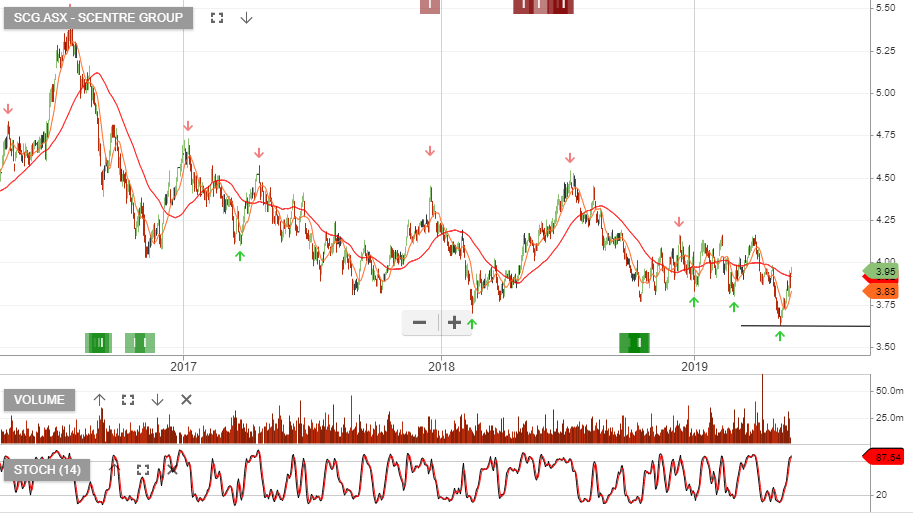
Scentre is under Algo Engine buy conditions and  a name we’ve recently drawn our readers attention to, as a buy write.

The share price has since rallied from $3.80 to $4.08. We still  see scope for gains from a buy write strategy, which captures the upcoming dividend .

SCG goes ex div $0.11 on the 14th of August.

Low global bond yields and the  announced share buy back by SCG, will help underpin downside risks.

Boral, CIMIC & Downer EDI

$280 billion in announced public infrastructure projects by 2020 in Australia, will help support growth for Boral, Downer EDI and CIMIC.

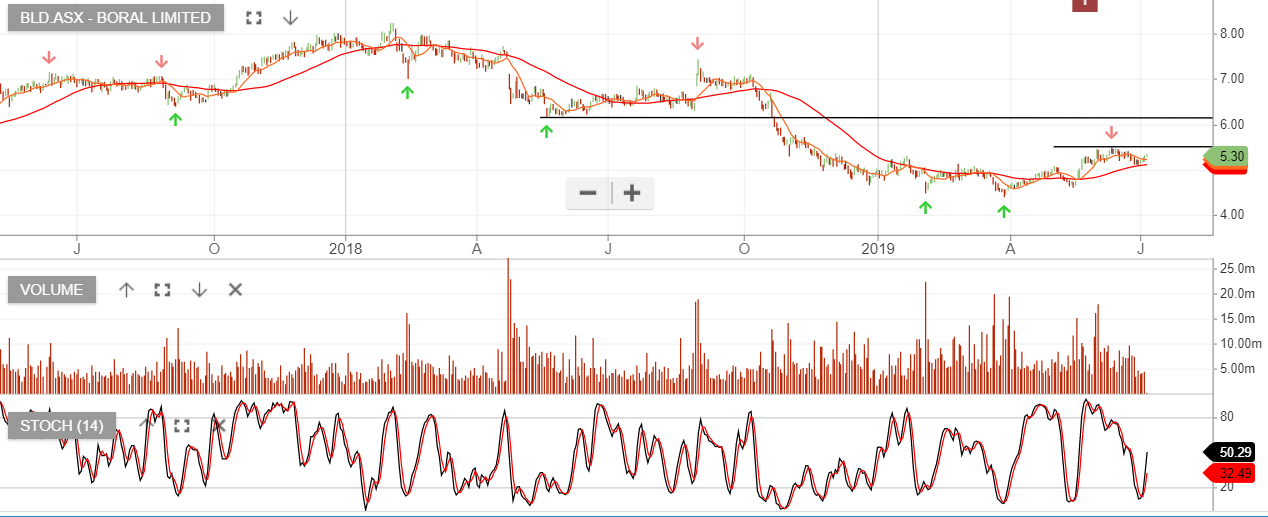
Boral & CIMIC are showing  Algo Engine sell signals, whereas, DOW is under a a recent Algo Engine buy signal.

All three names are attractive on a fundamental basis, however, the deep discount in Boral makes it our preferred allocation.


Altium – algo update

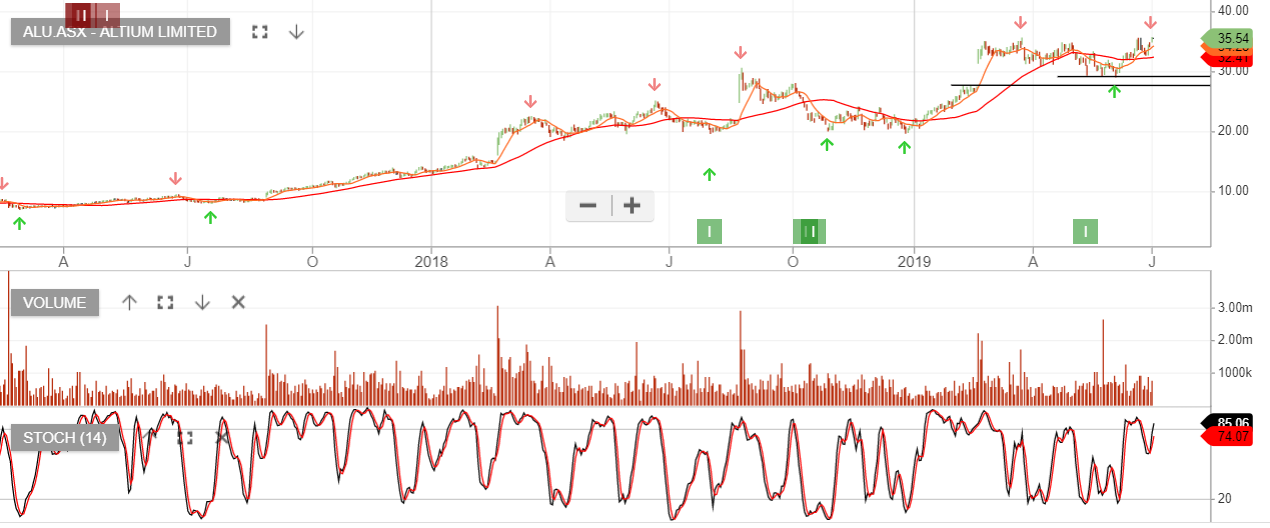
Altium switched from sell to buy conditions in July 2018 at $21 and more recently we had an Algo Engine buy condition again in May at $31.00.

ALU is a strong momentum play and the stock is now up 10% in the past 4 weeks. We continue to hold ALU and will look to take profit once the short-term indicators turn negative.

–

Scentre Group – Buy to generate 10% cash flow

Scentre Group announced an on-market buy-back of outstanding shares, the Company intends to complete the buyback within 12 months. The buy-back will add incremental support to our suggested buy-write strategy.

We recommend buying Scentre and selling covered call options. The stock goes ex-div $0.11 on the 14th of August.

Selling a Sept out of the money call will generate an additional $0.12 per share of income.

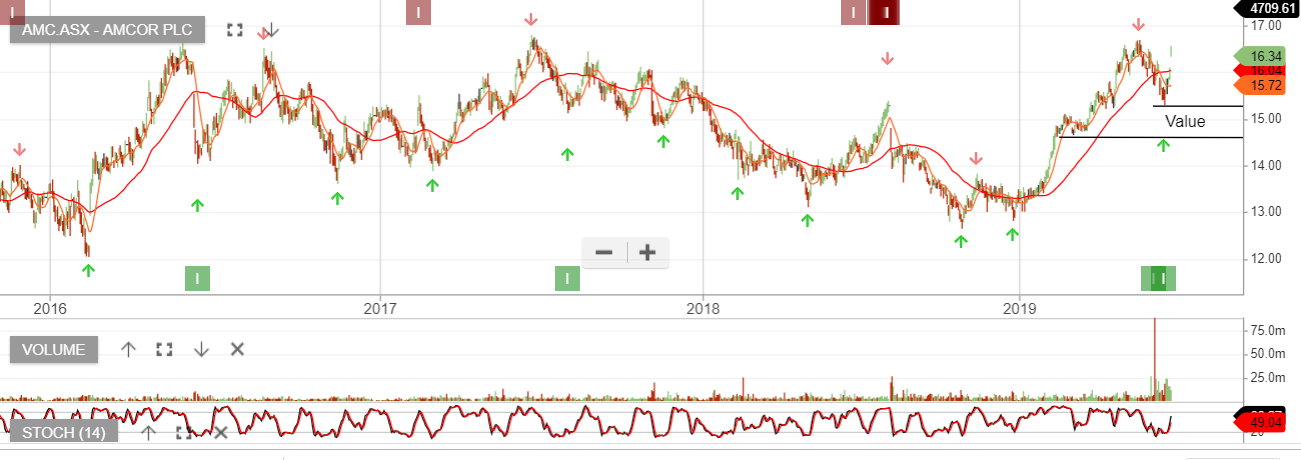
Amcor – Take Profit

Amcor strong share price movement suggests investors are
pricing in an earnings upgrade, but we think a significant EPS upgrade
is unlikely and investors should now take profit or sell covered calls.

Stock price is up 5% from the recent signal low.