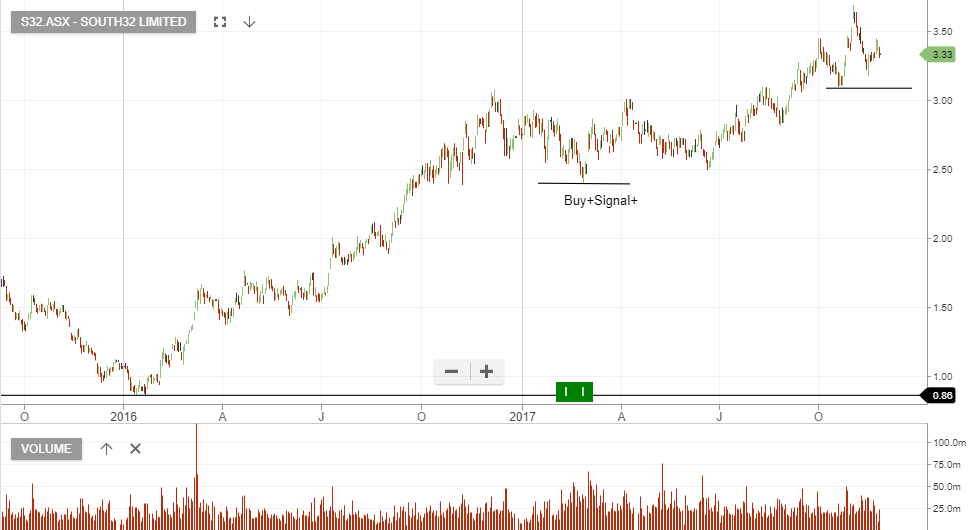
S32 – Spins-Off South African Energy Coal

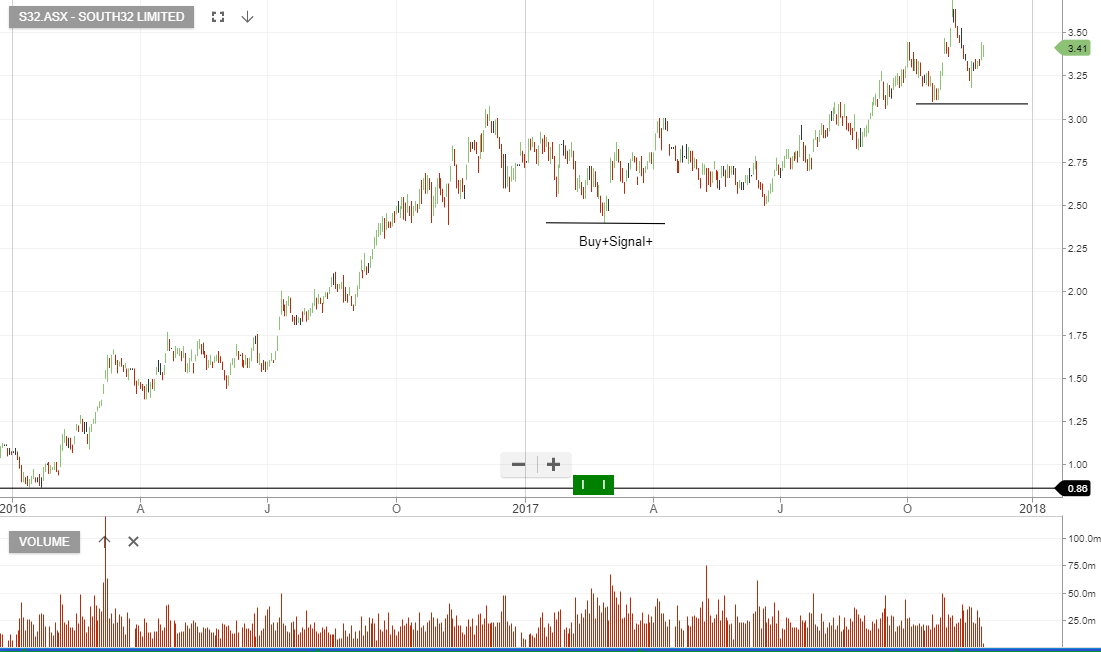
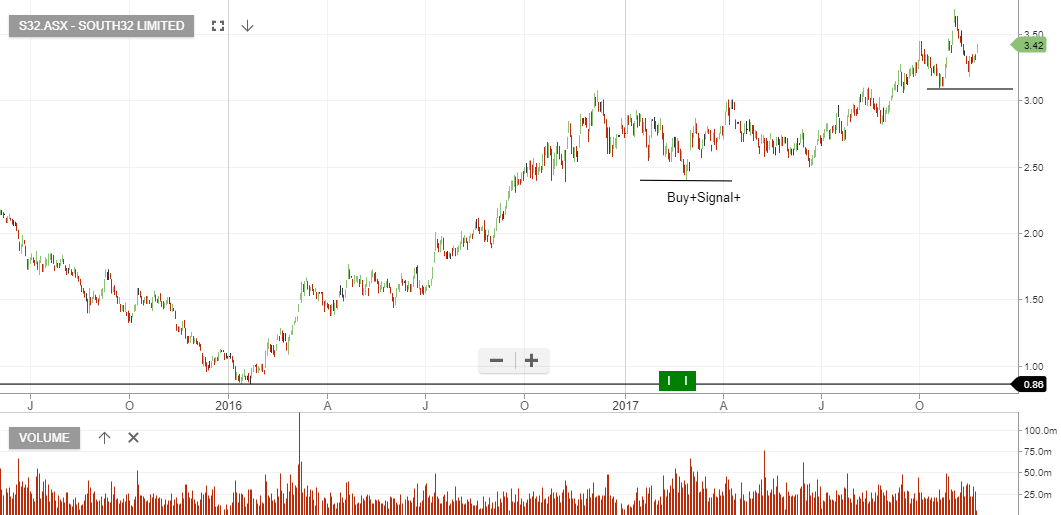
South32 announced plans to run its South African Energy Coal (SAEC) business separately from the rest of the company from April 2018.

We see this announcement as a net positive for shareholders.

Risks to South 32’s earnings relate to their exposure to commodities which have performed strongly over the near term.

S32 trades on a forward yield of 4.1% and we hold the stock in our ASX 50 model.
South 32
Algo Buy Signal – AMP

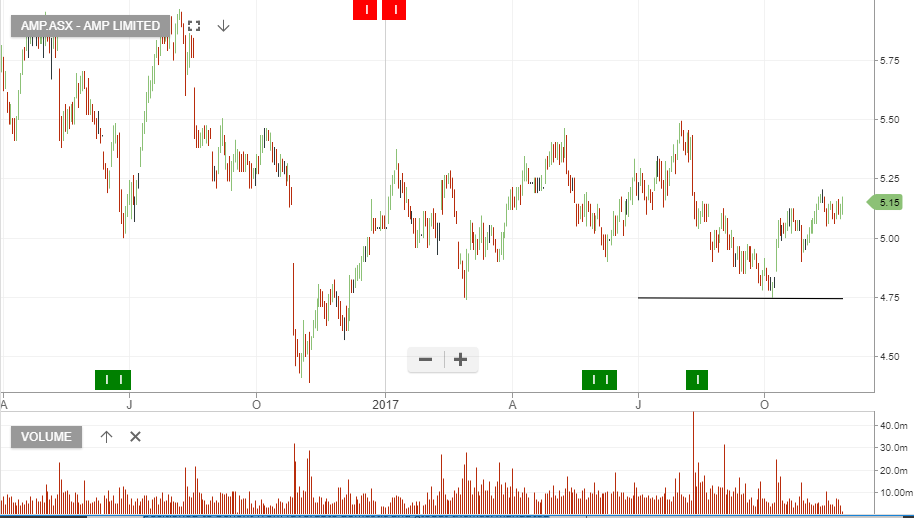
Our Algo Engine generated a recent buy signal in AMP.

With the price action finding support at $4.75 and now trading into the $5.15 range, we continue to see upside momentum.

AMP looks well positioned to benefit from domestic trends in mandated super and search for yield in infrastructure & property.

AMP is currently in our ASX 20 and ASX 50 model portfolios.

AMP

S32 – Valuation Review

We assume no change to S32 earnings guidance but will review commentary on 5 December when S32 is set to host a capital markets day in Perth.

We expect management to update production guidance for its core operations for FY18.

FY18 revenue should be flat on FY17 at $7b and EBIT will also be in-line at $1.7b. We have S32 trading  on a 4% forward yield

We see the potential for earnings upgrades should spot metal prices stay at current levels. Strength in alumina, manganese, coking coal and thermal coal is helping to underpin our outlook.


Ramsay Healthcare – Long Term Value

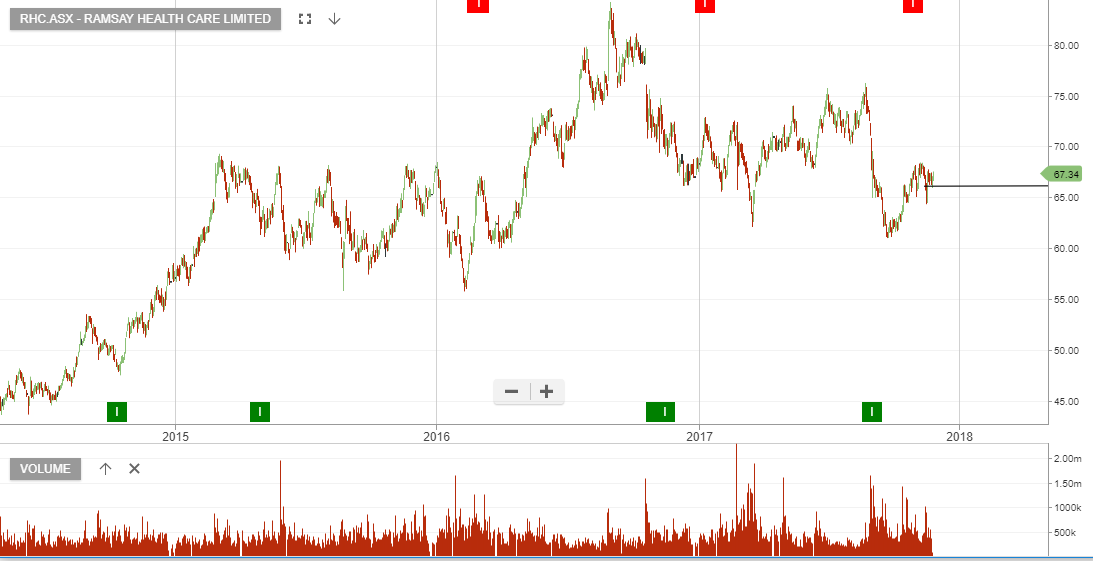
Ramsay Healthcare has been making a “lower high” pattern since selling off from the $75 high in August.

We’re reluctant to look at counter trend trades, however, with the broad thematic of the healthcare space being one of our preferred sectors, we now look to re-enter long positions in RHC.

Over the next 12 months we look for RHC to trade back towards $72 – $75 level on the back of the recent comments from the CEO, where he confirmed the company should deliver 8 – 10% EPS growth.

Ramsay Healthcare


Sydney Airport & Transurban React to Lower Yields

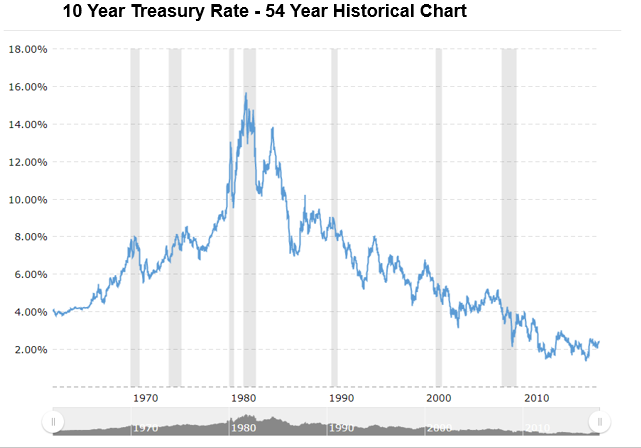
With the short end of the interest curve in the US moderately increasing and the longer end not reacting, we’re seeing a flattening in the US yield curve.

The message this sends,  is the bond market believes US rates will rise short term but the global economy is still fragile and inflation is low, therefor the prospects of longer term rate increases are quite low.

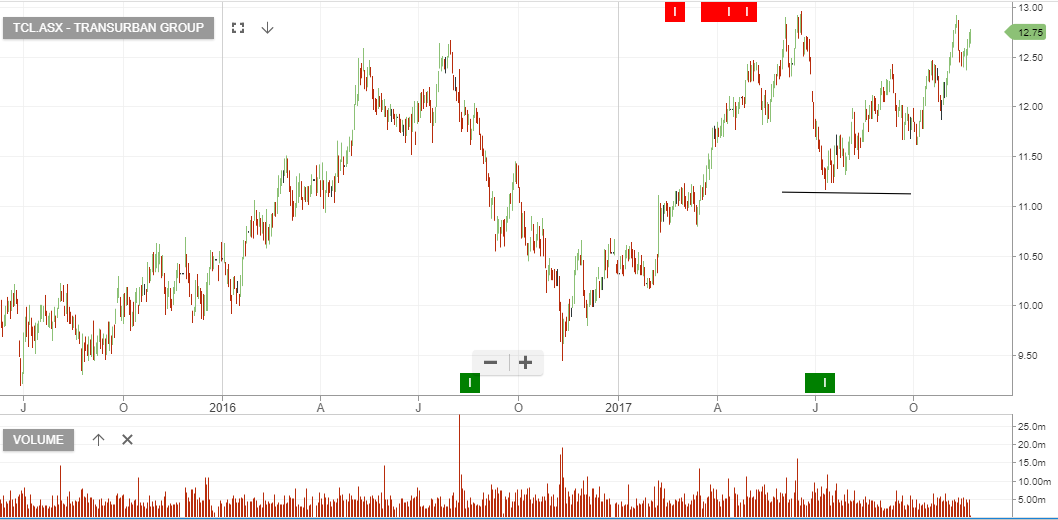
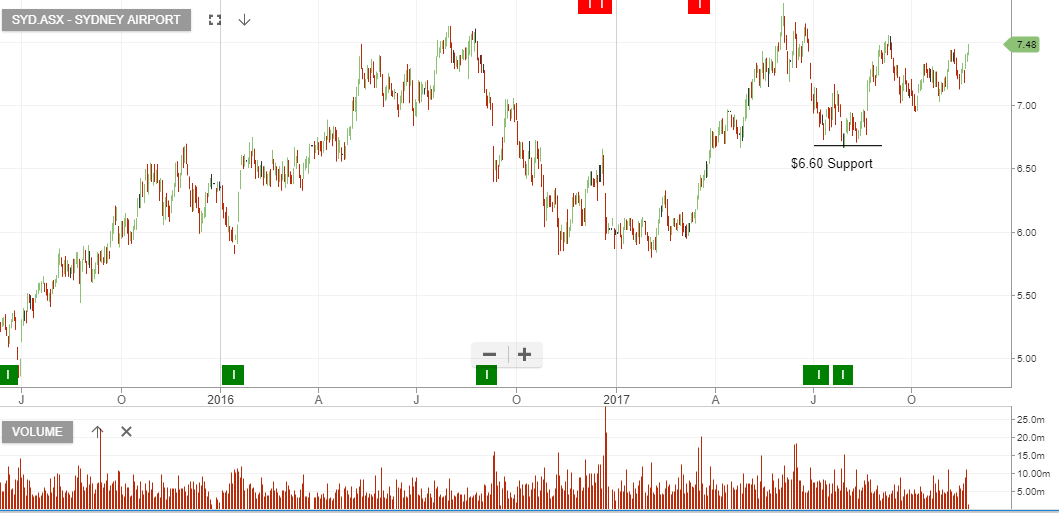
These events are helping to support interest rate sensitive names such as SYD and TCL.

SYD will pay a $0.16 dividend on the 29th of Dec and TCL will pay $0.26.

SYD is in the ASX 50 model and TCL is on both the ASX 20 and ASX 50 model.

We consider both names fully valued at current prices and recommend overlaying a covered call option to enhance the return.


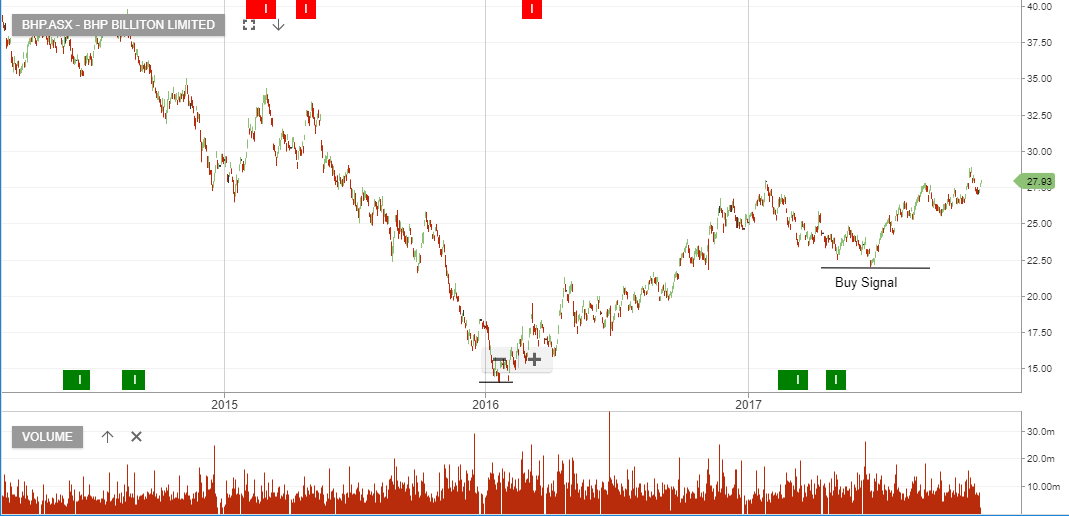
Algo Buy Signal – BHP

Our Algo Engine triggered a buy signal on BHP back in May at $22.60. With Oil prices remaining well supported, we feel the outlook for BHP earnings has now improved, as to has the prospect for a better price for any divestment of their US energy portfolio.

BHP is currently in the top 20 and top 50 model portfolio’s. We recommend buying BHP and selling $29.50 covered calls into March.

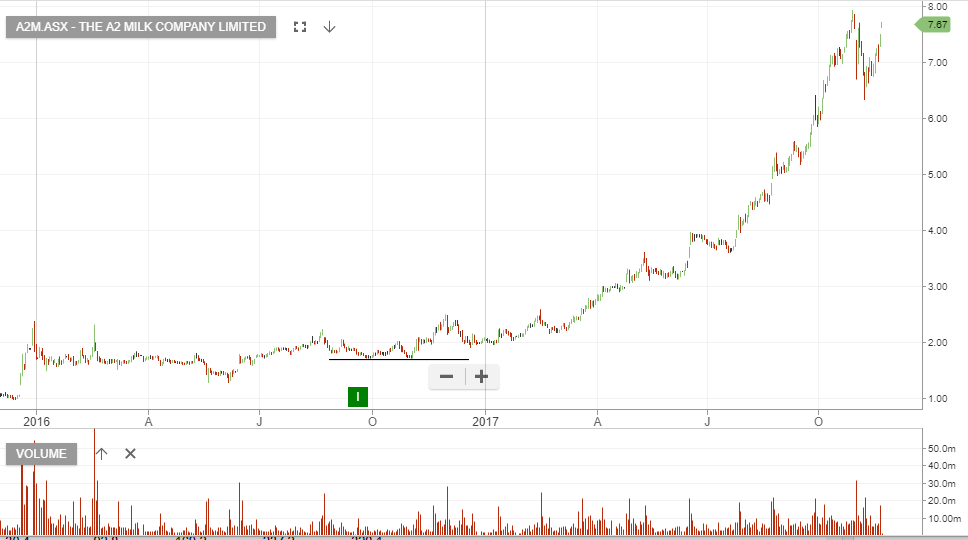
A2 Milk Company – Valuation Review

A2  Milk Company continues to deliver increasing sales and margin expansion. Higher margin infant formula is helping to drive margin expansion from 20 to 30%.

Analysts are forecasting revenue to grow from NZ$550m in FY17 to $900m in FY18 and EBIT to increase from $140m to $250m. By 2020 EBIT is expected to increase to $440m.

These are big growth numbers and when we look at what it means for dividends, we’re a little less excited. If we assume these growth metrics are achieved, it places A2 on a 2020 PE of 21x earnings and a 1.5% yield.

The conclusion is, significant earnings growth is required to support a modest yield and high PE in 2 – 3 years time.

We last had an Algo Engine buy signal in A2 back in September 2016 when the stock was trading at $1.80