Marvell

Marvell Technology, Inc. – Common

Upcoming Earnings Outlook: Expected Release Date: August 27, 2026 (After Market Close)

  • Fiscal Period: Q2 Fiscal Year 2027 (Quarter ending late July 2026)
  • Consensus Estimates: Non-GAAP EPS: $0.87 – $0.93 per share (vs. $0.67 in Q2 FY2026, representing ~30%–38% YoY growth)
  • Consensus Revenue: ~$2.60B – $2.71B (vs. $2.01B in Q2 FY2026, representing ~30%–35% YoY growth)

      Key Drivers & Long-Term Growth Outlook: Marvell’s custom ASIC program (designing tailored AI chips for cloud hyperscalers like AWS, Google, and Microsoft) and optical connectivity solutions (800G / 1.6T DSPs) remain the primary catalyst.

        • Accelerating Quarterly Trajectory: Management guided sequential revenue acceleration throughout FY2027, aiming for quarterly revenue to reach ~$3.0 billion in Q3 and Q4.

        Full-Year FY2027 & FY2028 Targets:

        • FY2027 Revenue: Expected to reach ~$11.5 billion (+40% YoY growth), driven by >50% growth in the Data Center segment and >70% growth in optical interconnects.
        • FY2028 Target: Revenue guided toward ~$16.5 billion as cloud hyperscaler AI capital expenditure expands further.

          Key Things to Watch on Earnings Day

          1. Custom AI ASIC Shipments: Progress on hyperscaler customer design wins ramping into volume production.
          2. Gross & Operating Margins: Non-GAAP gross margins (target zone ~59–60%) and expense control as R&D investment increases.
          3. Hyperscaler AI Capex Trends: Any commentary on customer demand pacing for 800G/1.6T electro-optics and PCIe/CXL switches.
          4. Supply Chain Capacity: Lead times and substrate/co-packaged optics assembly capacity.

          Marvell

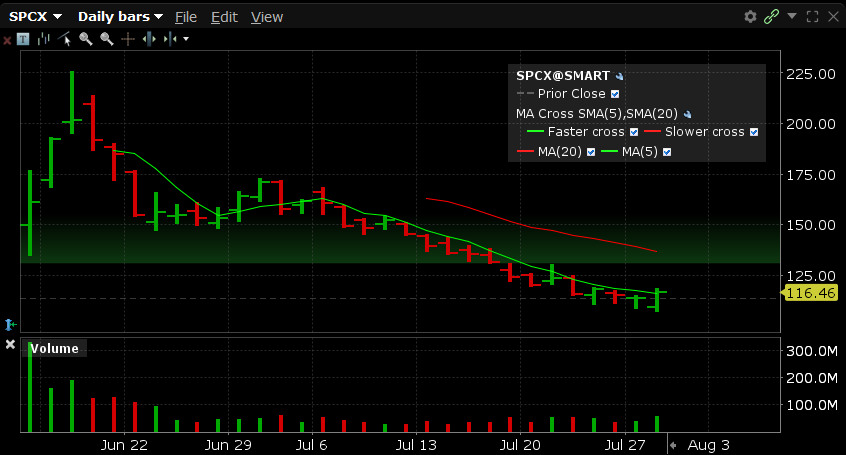
          Maravai Lifesciences Holdings Inc Cl has experienced a sharp pullback, dropping roughly 35% to 40% from its record high near $316 in early June to around $180–$195. This decline is largely attributable to valuation compression, semiconductor sector-wide momentum unwinding.

          In early June, MRVL surged following high-profile commentary at Computex (where Nvidia CEO Jensen Huang called Marvell the “next trillion-dollar company”) and its inclusion in the S&P 500. This drove the stock past $315. At its peak, MRVL traded at a forward P/E exceeding 65x–70x earnings

          Marvell’s upcoming Fiscal Q2 earnings report (scheduled for late August 2026) will be critical. Consensus estimates project Q2 revenue of ~$2.7 billion (+35% YoY)

          Applied Optoelectronics

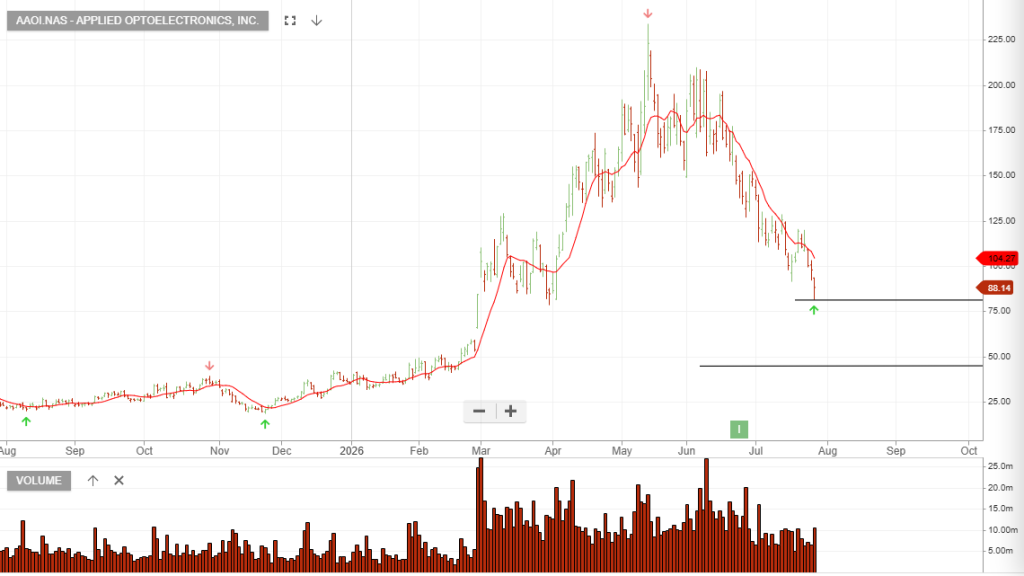
          Applied Optoelectronics, commenced construction on a nearly 400,000-square-foot expansion in Pearland, Texas, to support volume production of its 800G and 1.6T optical transceivers for AI datacenters.

          Sector Rotation out of Crowded AI Infrastructure Trades

          • Capex Sustainability Concerns: Concerns over hyperscaler capital expenditure returns (highlighted by heavy capex outlays across big-tech AI buyers) triggered widespread profit-taking across crowded AI component trades.
          • Peer De-rating: Peers like Lumentum (LITE) and Coherent (COHR) also faced steep pullbacks as high-multiple optical names were sold off in favor of cash-generative value trades.

          scheduled to release its Q2 2026 financial results on Thursday, August 6, 2026, after Market Close.

            Wall Street Expectations

            • Revenue Guidance / Estimates: Management guided Q2 revenue in the range of $180.0M – $198.0M.
            • EPS Estimate: Consensus estimates project Non-GAAP EPS around -$0.03 to +$0.03 per share.

            Astera Labs

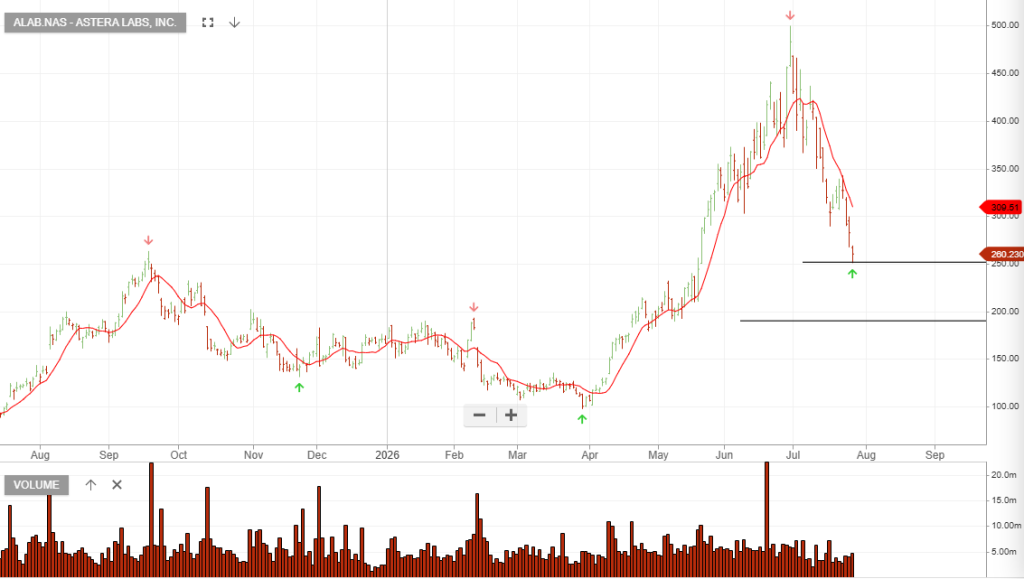
            Astera Labs,

            Critical AI Bottleneck Layer: As GPU clusters grow into tens or hundreds of thousands of chips across multi-rack networks, high-speed signal integrity over copper and optical media becomes vital.

              Emerging Competition: Larger networking/semiconductor players (Broadcom, Marvell, Credo) continue developing competing scale-up connectivity solutions.

              Upcoming Earnings Announcement

              • Next Earnings Date: Tuesday, August 4, 2026 (After Market Close)
              • Q2 2026 Guidance (Provided by Management):

              * Revenue: $355.0M – $365.0M (~15%–18% sequential QoQ growth)

              Most Recent Quarter: Q1 2026 (Quarter Ended March 31, 2026)
              Astera Labs delivered record-breaking top- and bottom-line results, beating Wall Street estimates driven by accelerating demand for high-speed PCIe Gen6 and switch fabric hardware in AI clusters.

              • Revenue: $308.4 Million

              * YoY Growth: +93.4% vs. Q1 2025 ($159.4M)

              United Micro

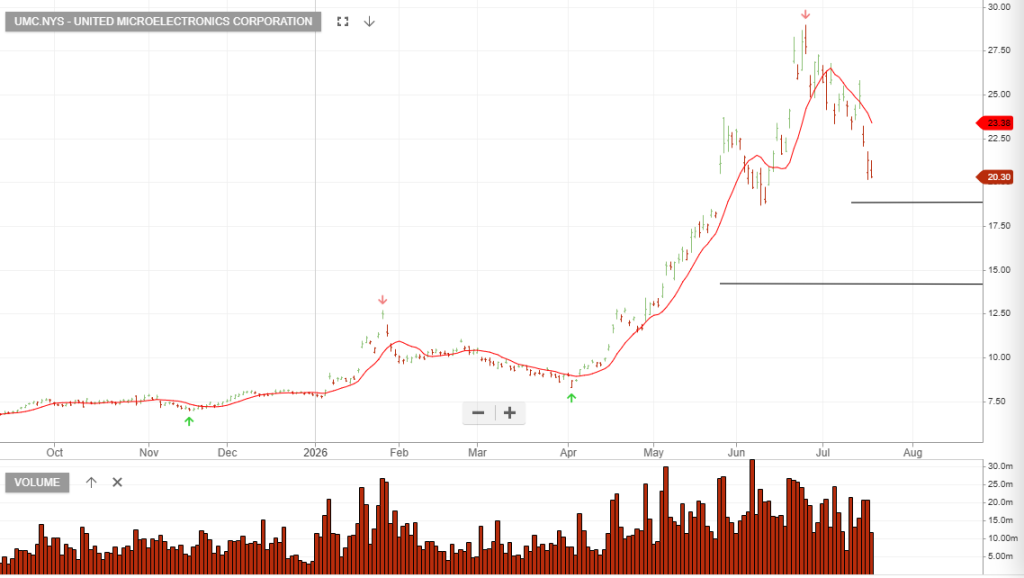
              NAS:UMC add to watchlist and look for interest to build near $18.50

              In early 2026, UMC announced a high-profile partnership with Intel to collaborate on a 12nm platform manufactured in the US. This partnership is slated for commercial production in late 2027 and vastly diversifies UMC’s geographic footprint.

              • Strong Balance Sheet: Fitch affirmed UMC’s BBB+ credit rating with a “Stable” outlook in June 2026. The company boasts a low debt-to-equity ratio of ~0.19 and a healthy current ratio of ~2.72.
              • Next Earnings Release: UMC is scheduled to report its Q2 2026 earnings on Wednesday, July 29, 2026. Analysts expect EPS of 15 cents on revenue of ~$2.06 billion, representing growth over the prior year.