Northern Star – Buy
Northern Star Resources is under Algo Engine buy conditions and at sub $10 the stock is now looking oversold.
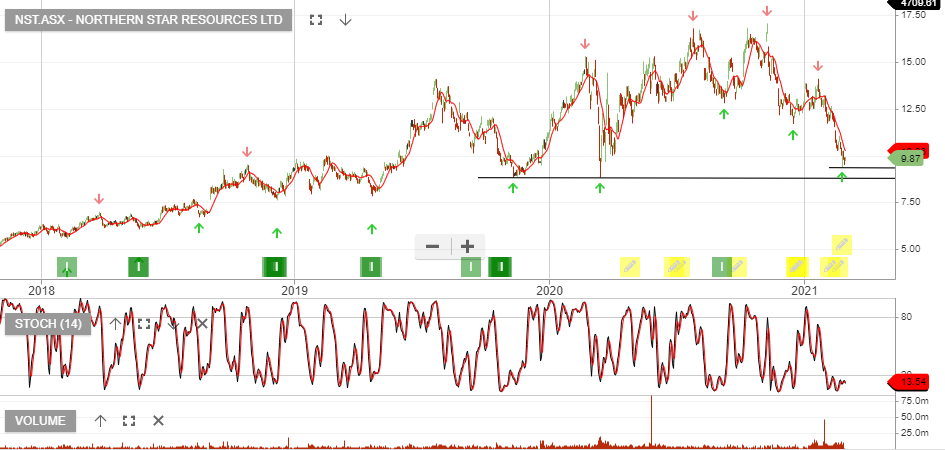
Northern Star Resources is under Algo Engine buy conditions and at sub $10 the stock is now looking oversold.
{ASX:CWY) is under Algo Engine buy conditions and is a current holding in our ASX 100 model portfolio.
We see price support building near the $2.20 level.

Sorry, but this content is restricted to our members.
Please login with your account or register for a free trial. If your trial has expired, then you may renew it here.
If you are having an issue with your account, then please get in touch with us.
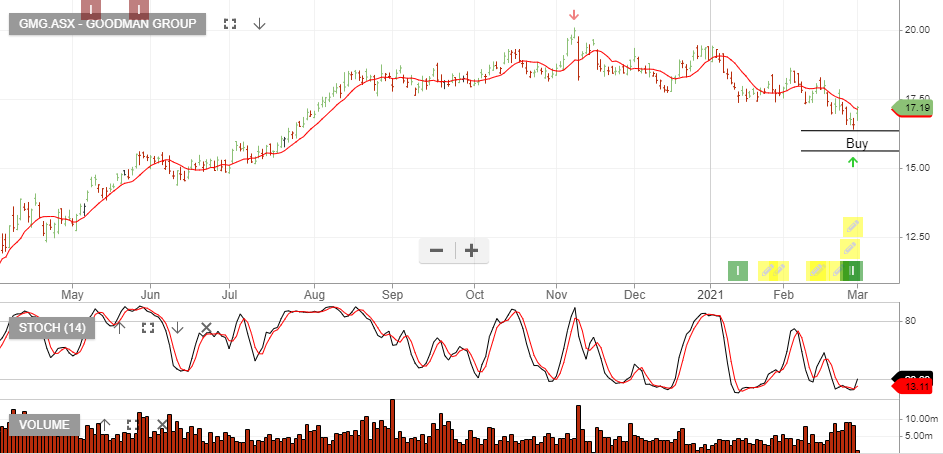
Goodman is under Algo Engine buy conditions and is a current holding in our ASX 100 model portfolio.
We expect 10% EPS growth into FY22 and the 2% plus dividend yield remains well supported.
The short-term momentum indicators are now turning higher and it looks like buying support is building above the recent $16.40 low.
{ASX:CWY) is under Algo Engine buy conditions and is a current holding in our ASX 100 model portfolio.
We see price support between $2.00 and $2.20. Watch the short-term indicators for a turn higher, within this support range.
CWY goes ex-div tomorrow $0.05 100% franked.
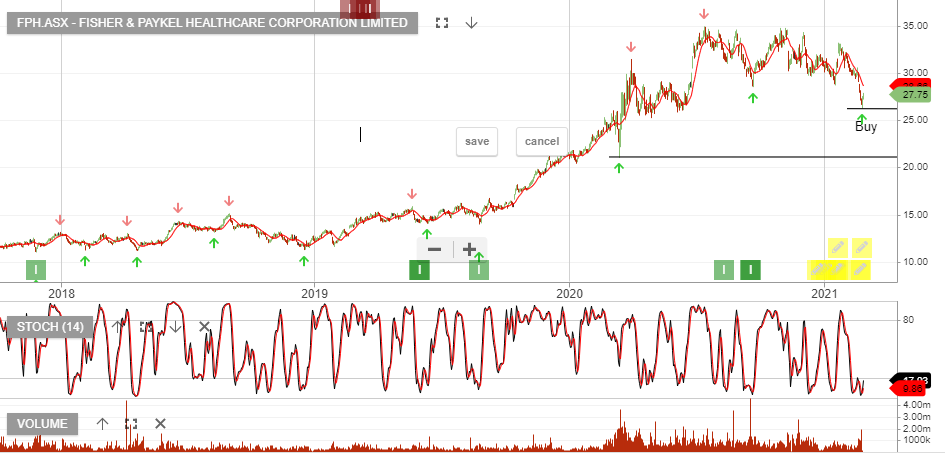
Fisher & Paykel Healthcare Corporation is under Algo Engine buy conditions and is now within our highlighted range.
The short-term momentum indicators are now turning higher and it looks like buying support is building above the recent $26 low.
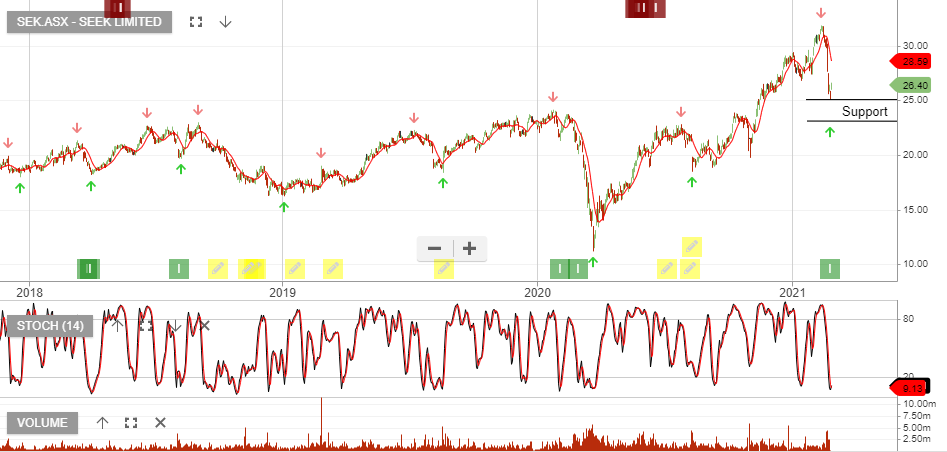
SEK:ASX is under Algo Engine buy conditions.
Seek announced a strategic refocus with ‘SEEK’ and Investments. Seek will focus on the existing business and Investments, being an investor and business builder, allowing Seek Investments to access third-party capital.
1H21 result with EBITDA of $246m.
Revenue will likely increase from $1.7bn, (in FY21), to $2bn in FY22, EBIT to increase from $270m to $400m. The forward div yield remains at less than 1% and 50x FY22 PE ratio.
Seek offers terrific growth prospects, but the valuation remains stretched.
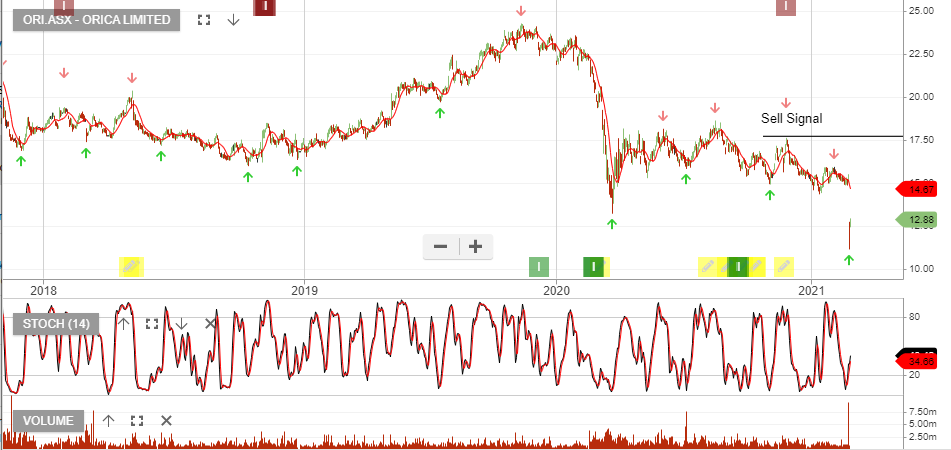
ORI:ASX flagged a weak 1H21 due to COVID, along with China’s ban on Australian thermal coal imports and FX headwinds impacting the 1H21 result.
The next update will be at its 1H21 result on 13 May.
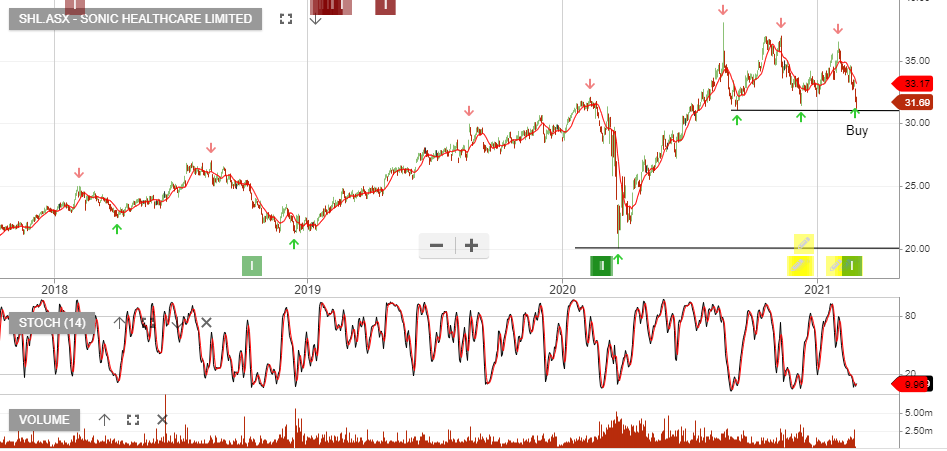
SHL:ASX is under Algo Engine buy conditions and is a current holding in our ASX model portfolio.
If we strip out the jump in FY21 profits from COVID testing and look at what FY22 and FY23 normalized business conditions look like, we still get to a valuation that supports the current share price.
FY22 revenue is likely to be around $7.6bn on EBITDA of $1.7bn. EPS will be 30 – 40% up on FY20, which will support a forward yield of 3.5%.

Level 17 Chifley Tower
2 Chifley Square
Sydney, NSW 2000
1300 614 002
Investor Signals Pty Ltd
ABN 44 143 555 453
