US Banks – Breakout

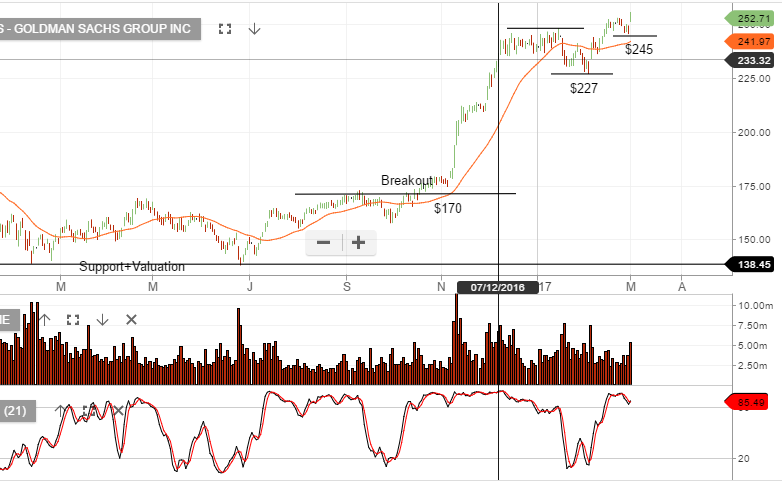
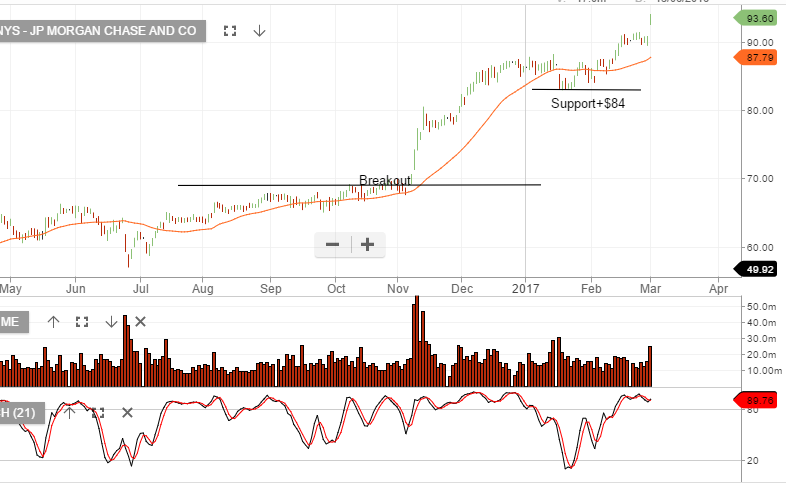
After consolidating from mid-December to mid-February, we’re now seeing US financials breakout again to the upside.

Using Goldman Sachs as a leading indicator to US financials, we form a view that it’s best to stay with the upside momentum until we see a downturn in price which takes-out the recent minor higher low at $245.

Whilst we struggle to see the EPS support for US equity valuations, momentum remains very strong. March quarter earnings to be announced in 4 weeks may provide a reason for investor’s buying enthusiasm to  pause.

Chart — Goldman Sachs
Chart – JP Morgan
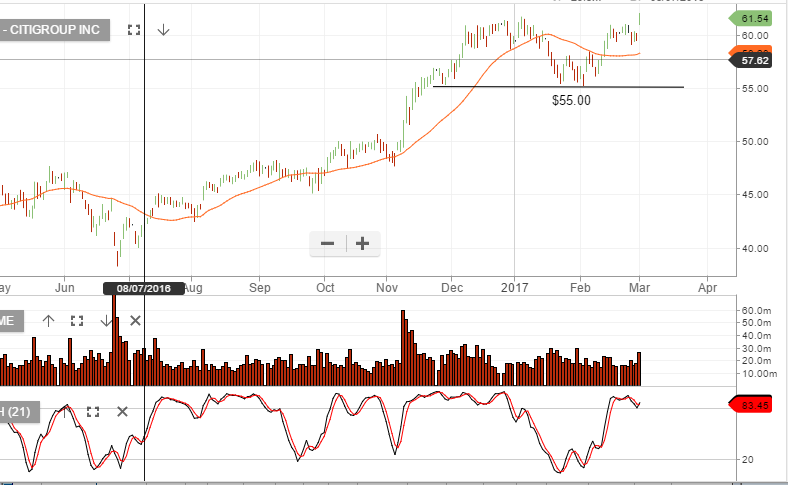
Chart – Citi Group


Mr Trump’s Speech

On February 9th, President Trump jarred the US stock market by saying he was going to make a “phenomenal” tax announcement in a few weeks.

A few weeks are up, and Mr Trump will be speaking to a joint session of Congress at around 1pm Sydney time today.

Since Mr Trump’s original announcement , the SP 500 has gained over 60 points , or close to 3.5%, largely on three key policy expectations:  tax reform, aggressive infrastructure spending and a more business-friendly approach to market regulation.

Considering the unprecedented nature of today’s speech, it’s difficult to precisely gauge the amount of time Mr Trump will spend on these economic policy initiatives and the level of detail he will provide.

It is very likely that the market will react sharply to any comments on the timing of tax reform. This includes comments about the Border Adjustment Tax (BAT); which has not been popular with retail and banking stocks.

In the lead up to today’s speech, administration officials have watered down some of the dynamics of these three  policy measures. Despite this lowering of expectations, the US stock market has still traded at elevated levels relative to earnings valuations.

On balance, we believe that Mr Trump’s speech will fall short of “phenomenal” with respect to the specific details of tax reform for US corporations and individuals. Technically, the DOW, SP 500 and the NASDAQ are all overdue for a correction.

Whether today’s speech marks the beginning of this correction depends on the degree of detail that Mr Trump provides about these three key policy measures.
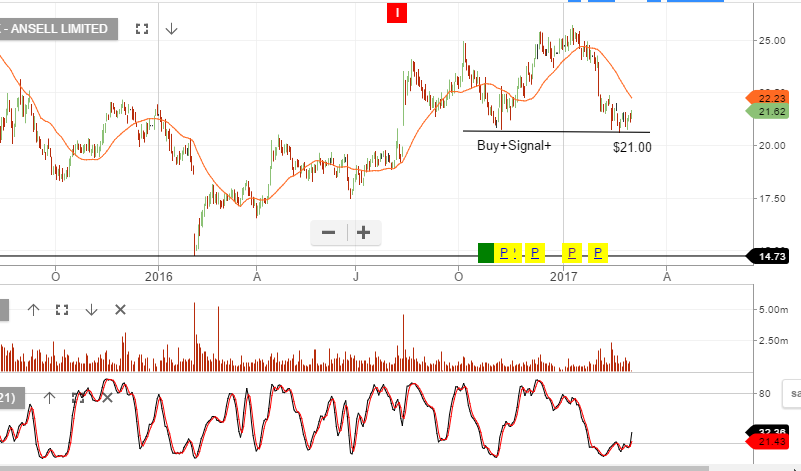
Value Emerging in AMC and BXB

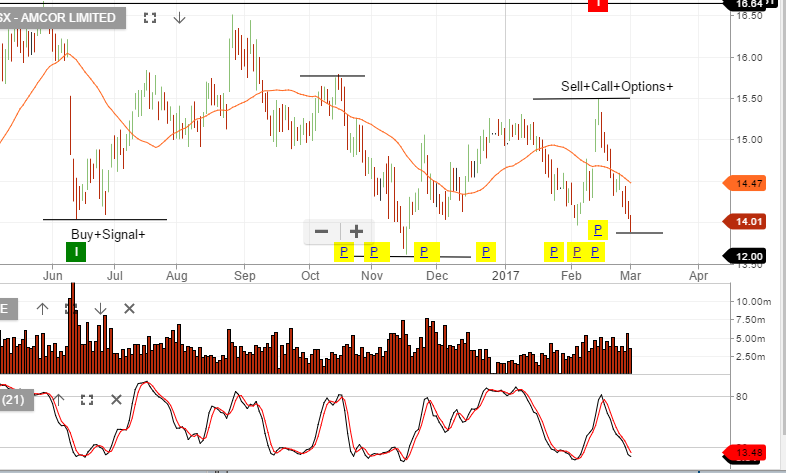
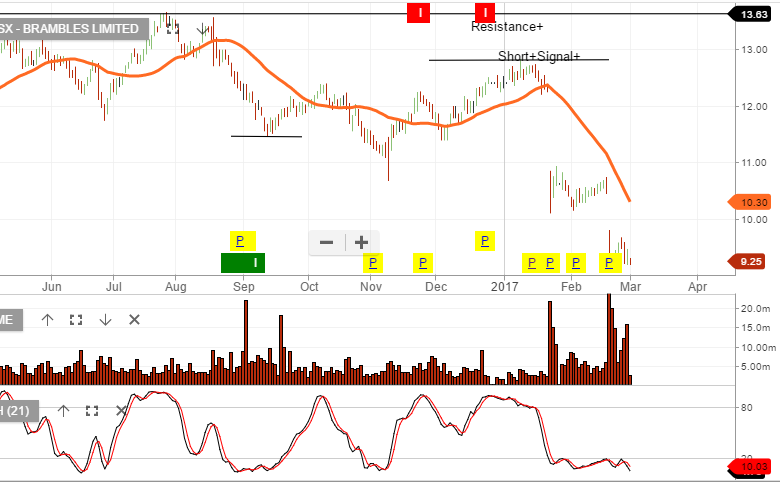
Following the sell-off in both AMC and BXB , we now are looking for buying support at or near the current levels. Our short-term momentum indicators have not yet turned positive but we’re likely getting close to valuation support, where increased buying will occur.

We see value in AMC at $14.00.

Chart – AMC

We see value in BXB at $9.25

Chart – BXB

Harvey Norman

Harvey Norman announced a record H1 result after property valuations and strong furniture and appliance sales lifted the company’s net profit by 39% to $257.3 million.

Underlying pre-tax profit rose 20.6% to 290.49 million, which is the highest first-half result in the retailer’s 30-year history.

The company declared an interim dividend of 14 cents (fully franked), which is up 1 cent on the same time last year.

Construction Arm Boosts Lendlease

Shares of property group Lendlease popped to an 18-month high of $15.84 in early trade as the company announced a sharp increase in after tax profit.

For the six months ending December 31st, Lendlease posted a 12% rise in net profit to $394.8 million.

The stronger result was largely based on the 40% increase in earnings for their construction division, with their investment and development divisions posting pretty much unchanged results from last year.

The company announced an interim dividend of 33 cents per share (fully franked), which was slightly higher than the street’s expectation of 30 cents per share.

The company’s return on equity for the last six months reached 13.7%, which is at the upper end of their 10 to 14% target guidance.