US Market – Leading Indicators

We’ve been watching the rollover pattern in GE and the recent break of price support in Goldman Sachs as potential leading indicators. We now add UPS and FedEx as two additional stocks of interest.

FedEx Corporation is expected to report earnings in March. The report will be for the fiscal quarter ending Feb 2017. The consensus EPS forecast for the quarter is $2.62 whereas, EPS for the same quarter last year was $2.51.

United Parcel Services, (UPS), reported quarterly earnings and revenue that missed Wall Street’s expectations. Fourth-quarter earnings of $1.63 per share on revenue $16.93 billion and weak 2017 guidance, ($5.80 to $6.10 per share), has resulted in heavy sell-side pressure in the stock.

A point of note: In 2016, UPS re-purchased 25.5 million shares for about $2.7 billion.

The graphs below show a concerning trend of downside risk.
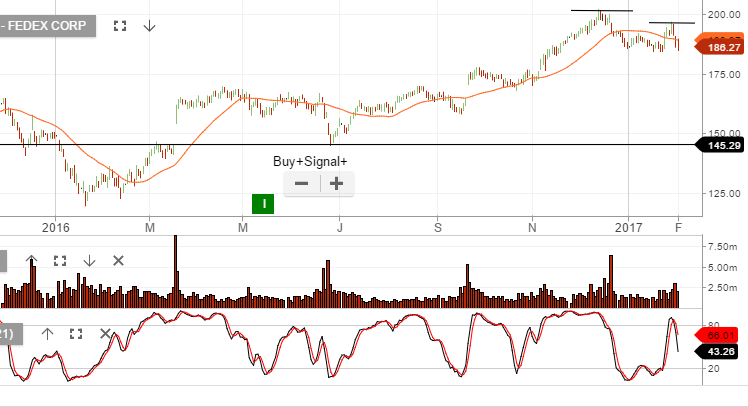
Chart – FedEx
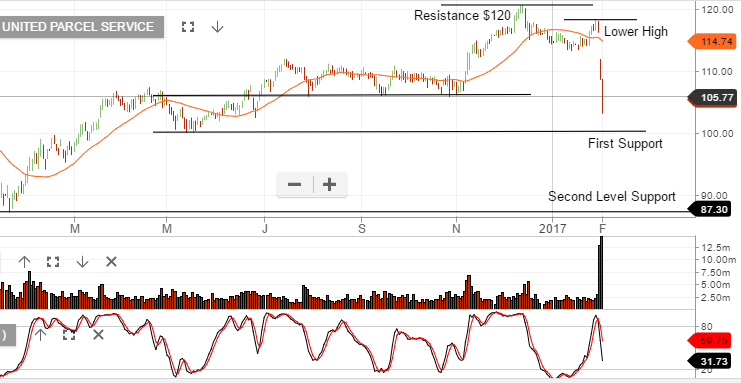
Chart – UPS


Facebook Q4 Earnings

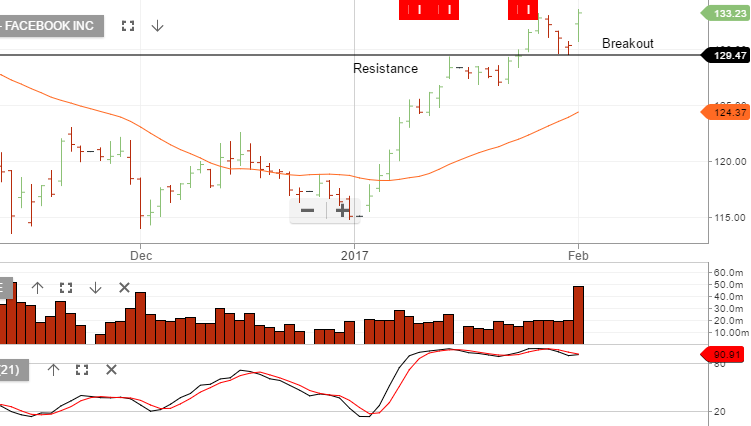
Shares of Facebook traded to an all-time high of $137.00 just after posting better-than-expected Q4 earnings and revenue results.

The social media giant announced adjusted EPS of $1.41 per share on quarterly revenue of $8.81 billion. These numbers exceeded the street’s estimates of $1.31 per share on revenue of $8.532 billion.

In addition, Facebook announced that Daily active users increased 18% year-on-year to 1.23 billion, while monthly active users grew 17% to 1.86 billion.

However, during the earnings call, CFO, David Wehner indicated that expenses will increase in 2017.

Chart – Facebook

Boral – FY18 Earnings Review

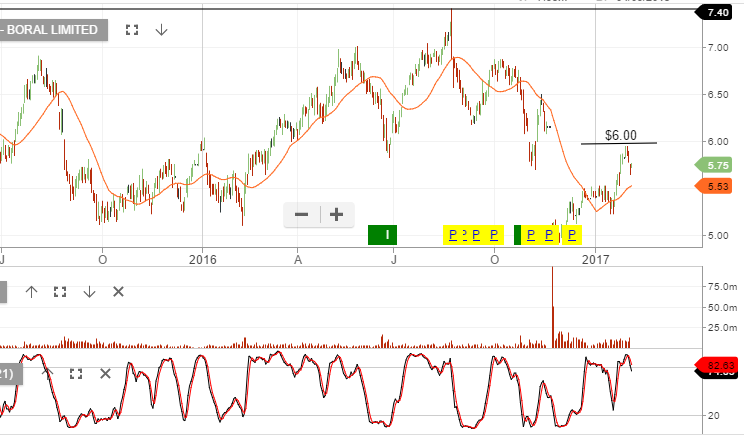
We thought it worthwhile to review the earnings outlook for Boral, post the acquisition of the Headwaters Group.

In FY18 revenue grows to $6.2b, EBITDA $1b, EPS $0.38 and DPS of $0.24 placing the stock on a 4% forward yield.

We’re cautious of the risks for Boral in achieving these targets and it appears the stock is relatively full value at the current price.

Chart – Boral


Exxon Q4 Results

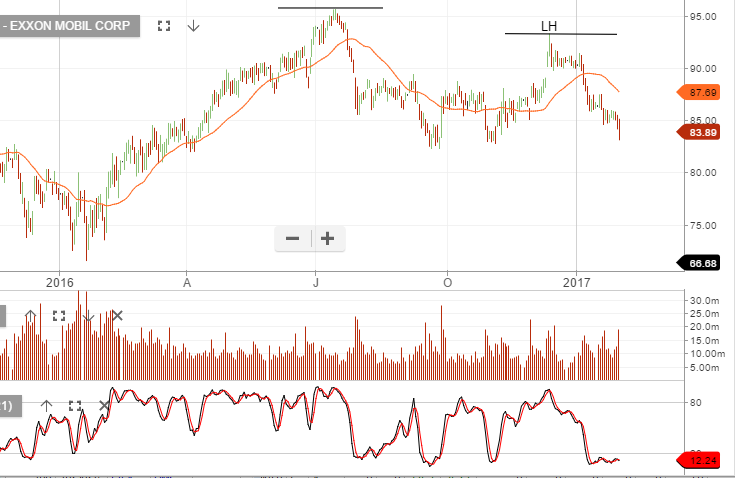
Shares of Exxon Mobil hit a 4-month low of $83.10 after the company missed Q4 earnings and revenue expectations.

The company announced earnings of 41 cents per share on revenue  of $61.1 billion. This compares to expectations of 70 cents per share on revenue of $61.4 billion.

The year-over-year data was mixed as Exxon earnings fell from 67 cents per share, but revenue rose from $59.8 billion against this time last year.

An upstream asset impairment charge of $2 billion, related to dry gas operations in the Rocky Mountain region, impacted Q4 as well as full-year earnings.

From a technical perspective we’re in a lower high structure with the next significant level of support near $80.00

Chart – Exxon

Apple Q1 Results

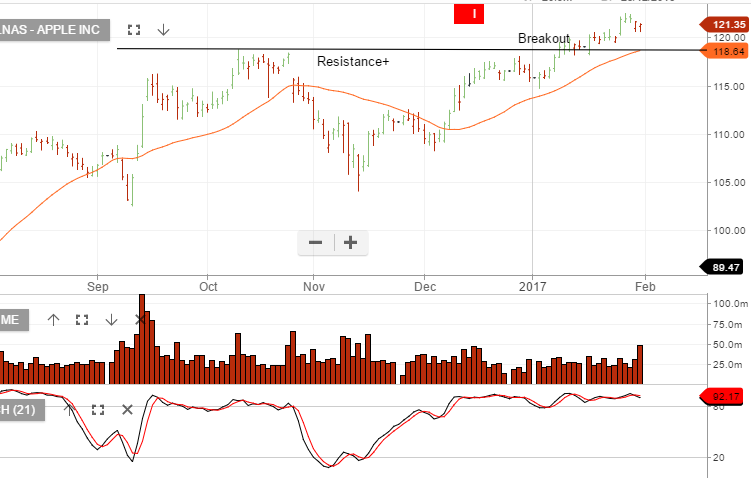
Shares of Apple are up 3% to $125.00 as Q1 earnings and revenue beat expectations. The firm also announce that they sold a record 78.4 million iPhones over the three month period.

Earnings were announced at $3.36 per share on revenue of $78.4 billion. The street was expecting earnings of $3.22 per share and revenue of $77.3 billion.

To put these sales and earnings numbers into perspective: Q1 2017  iPhone sales generated 69% of the company’s total revenue. This compares to 2.5% in Q1 2008.

One of the few negative aspects of the report was the forward guidance. The firm announced a modest cut to Q2 revenue to $51.5 billion from $53.8 billion expected.

As the market absorbs this report and lower forward guidance, we see price support back on the old resistance near $118. A break below $118 will validate our recent Algo Engine short signal. With price trading above our breakout range, we’re on the sideline for the time being with this trade.

Chart – Apple

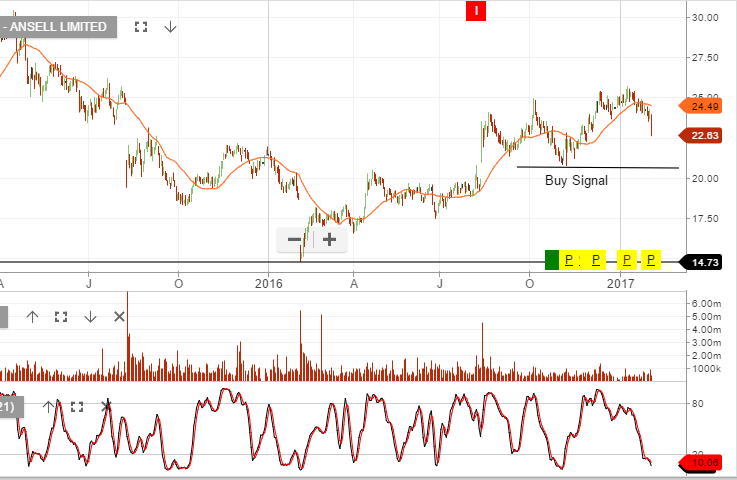
Ansell – Buy Signal

Ansell has purchased Nitritex, a UK-based manufacturer of premium clean-room and healthcare Life Sciences consumables. The deal is relatively small at US$60m and will be  near-term earnings accretive.

The transaction adds to income generated outside the US and extends to the Ansell’s expertise across the Life Sciences segment.

We’re buyers of Ansell on the current price pullback. Value exists in the $22.50 – $23.50 range.

FY17 revenue $1.65b, EBITDA of $285m, net profit $170m, EPS $1.10 and DPS $0.46 places the stock on 2.5% forward yield.

We expect underlying business growth into FY18 and FY19 of 6% – 9%.

Chart – ANN


European Economic Growth for 2016

European economic growth for 2016 rose to  1.7%. Inflation is running at  1.8%, which is nearing the ECB’s target of 2% and the jobless rate fell to 9.6%; the lowest figure since May 2009.

This is the first time since 2008 that we’ve seen EU growth prospects tracking near the rate of the US. By any comparison, the economic recovery in G7 countries is still at very low levels and fragile global conditions remain.

Equity market valuations are stretched, and subdued revenue growth will likely lead to analysts’ EPS targets being reduced by 50% for 2017 to reflect actual current growth rates.

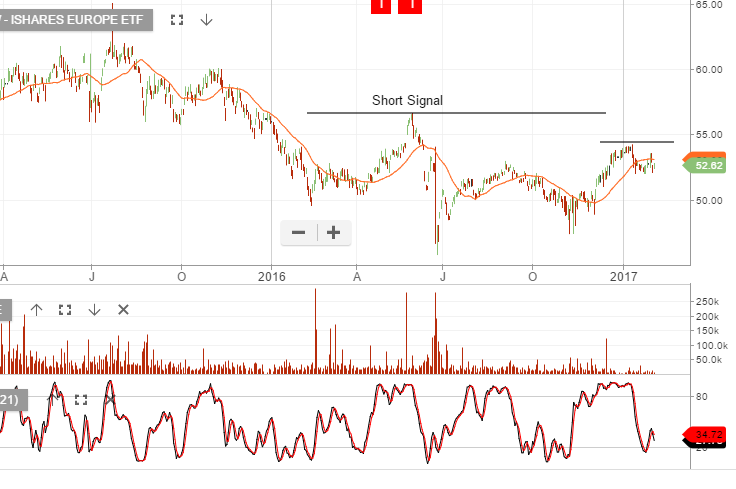
Our Algo Engine triggered a short signal in the iShares Europe ETF back in May at $55.75 and the index collapse by 18% within a few months following. Six months on and the index has recovered back to $52 and whilst we don’t have a new short signal present, we’re still cautious that another near term top is now in place.

Chart – iShare ETF (Europe)

Tabcorp – 2nd of February

Tabcorp reports earnings on the 2nd of February.

We assume Tatts merger is completed by middle of this year and generates cost savings post integration of $100m plus.

FY18 revenue $5.2b, EBIT $800m, DPS $0.25 places the stock on a forward yield of 5%.

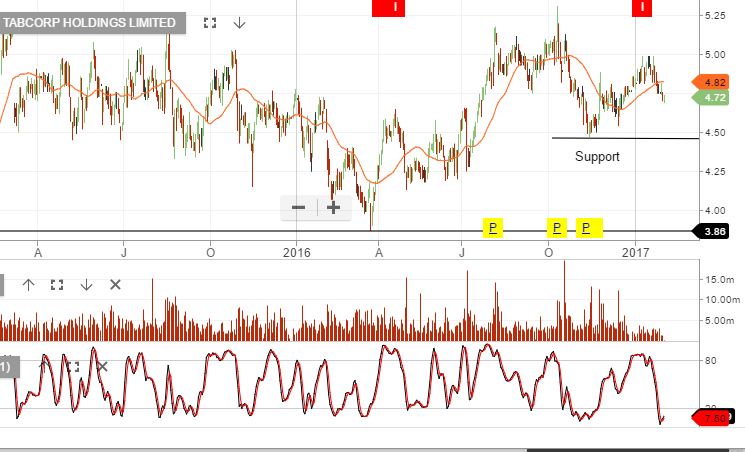
We’re buyers of TAH at $4.70 and selling call options post the earnings result.


Chart – TAH


Sonic Healthcare – Buy Signal

SHL has strengthened its German footprint with the purchase of two laboratories from Medical Laboratory Bremen for A$90 million.

The deal is EPS accretive in the first year with margin expansion & synergy gains achievable in the near term.  We expect Sonic to deliver 7 – 9% EPS growth in FY17 and FY18.

FY17 revenue $5.2b, on EBIT  of $920m, Net Profit $$480m, EPS of $1.20 & DPS $0.78, places the stock on a forward yield of 3.6%.

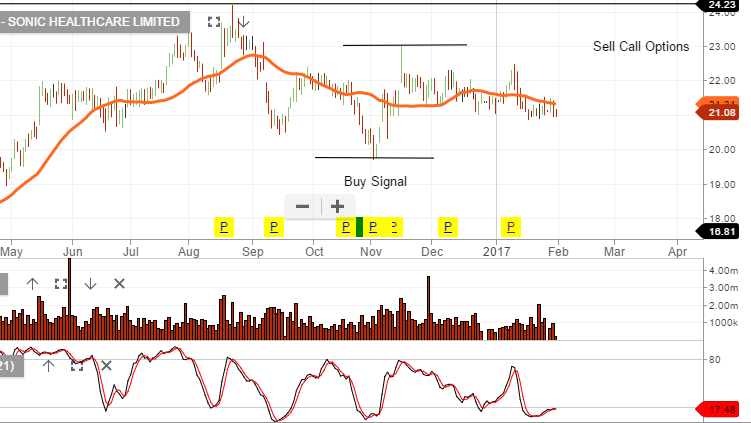
We like Sonic as a core portfolio position, however the low yield and moderate EPS growth encourages the use of a covered call to enhance the cash flow and boost the overall investment return.

Chart – Sonic Healthcare