Buy Healthscope 

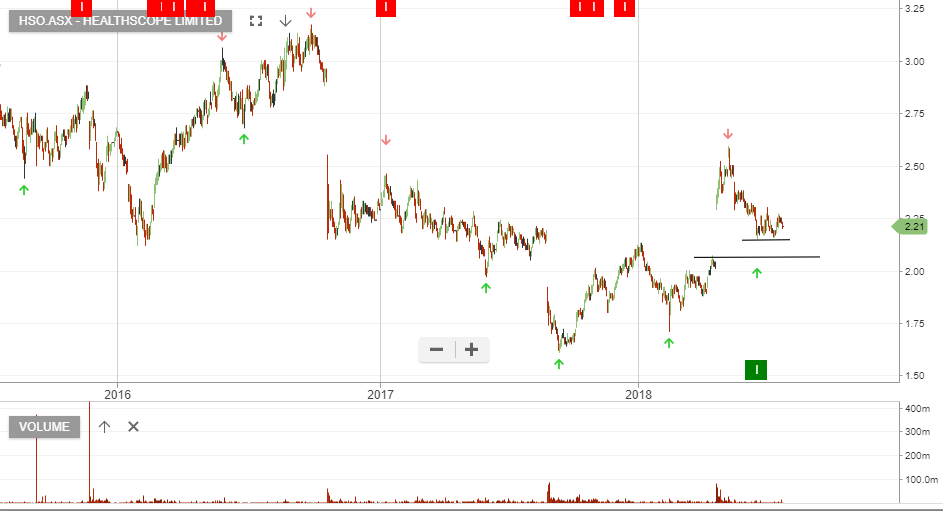
Our Algo Engine triggered a buy signal recently in Healthscope and we continue to see upside potential.

HSO has announced the sale of its Asian Pathology business to TPG Capital Asia for A$279 million. The transaction is expected to be completed by the end of August 2018.

Cash proceeds from the sale will be used to pay down debt and fund new domestic development plans.

The potential for M&A activity, along with the retracement in share price, makes HSO an attractive consideration supported by 3% dividend yield.
Healthscope
Stay Long Tabcorp In Front Of Next Week’s Earnings Report

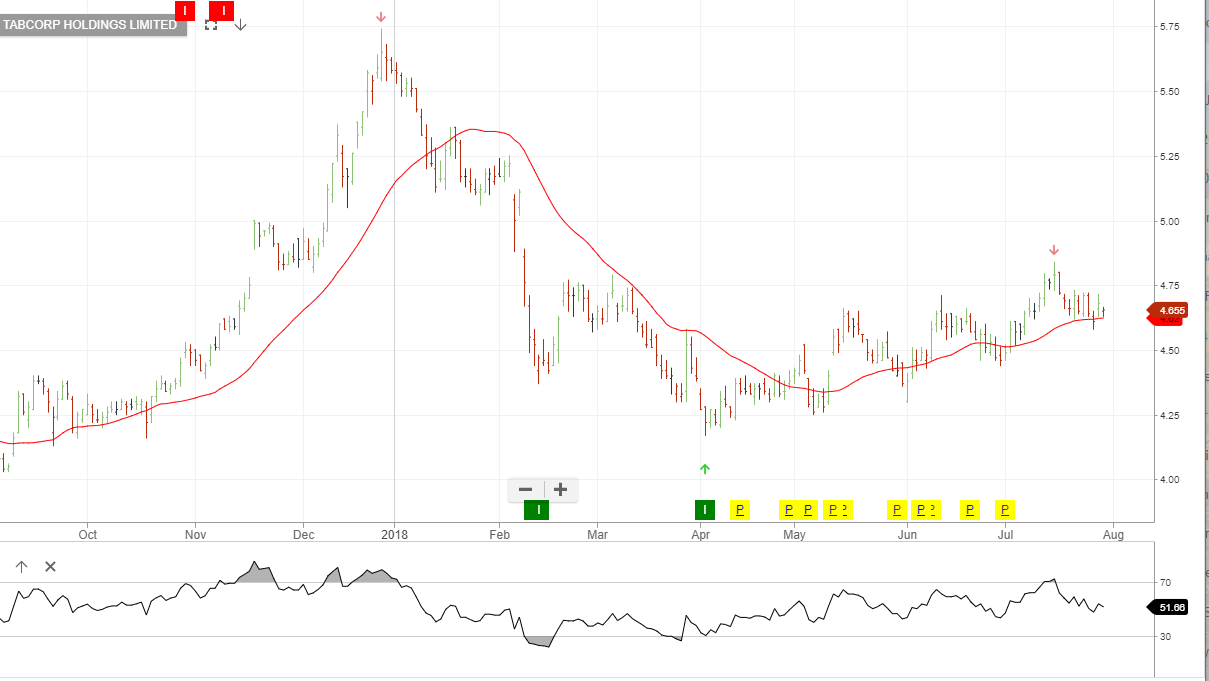
Over the last two weeks, shares of TAH have been trading in a narrow 15 cent range between $4.60 and $4.75.

It’s likely that this indecision pattern is due to the upcoming FY 2018 earnings report scheduled for August 8th.

This will be the first report which will include the combined Tatt’s and Tabcorp earnings data.

A recent broker note suggests that the the merged entities will have at least $130 million of synergy savings and has upgraded the stock to “overweight” with a target of $5.20.

Our ALGO engine triggered a buy signal on TAH on April 5th at $4.27 and the stock is included in our ASX Top 100 portfolio.

Tabcorp


AMP – 1H18 warning

AMP will need to address a wide range of issues including the Royal Commission responses, grandfathering and impact of Budget proposals in order for investors to understand AMP’s sustainable level of profitability. 

Investors are also looking for the CEO to outline  the longer-term group strategy. With many anticapiting some sort of restructure and the separation of the funds management business away from the advice model. 

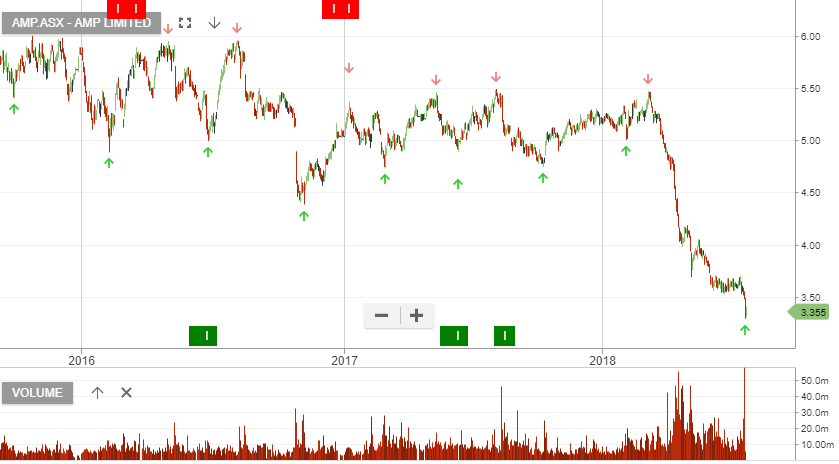
1H18E profit guidance came in lower than consensus expectations at  $490-$500 million.

AMP is the worst performing stock in the ASX 50 model.

We have two under performing stocks, AMP and FMG. Both businesses face unique structural issues that have weighed on their respective share prices.

We feel investors will be rewarded for slowly accumulating AMP shares at discounted levels but it is very difficult to see when the inflection point occurs.

AMP goes ex div $0.145 on 23rd August and we have the stock trading on a  forward yield of 7%.

AMP


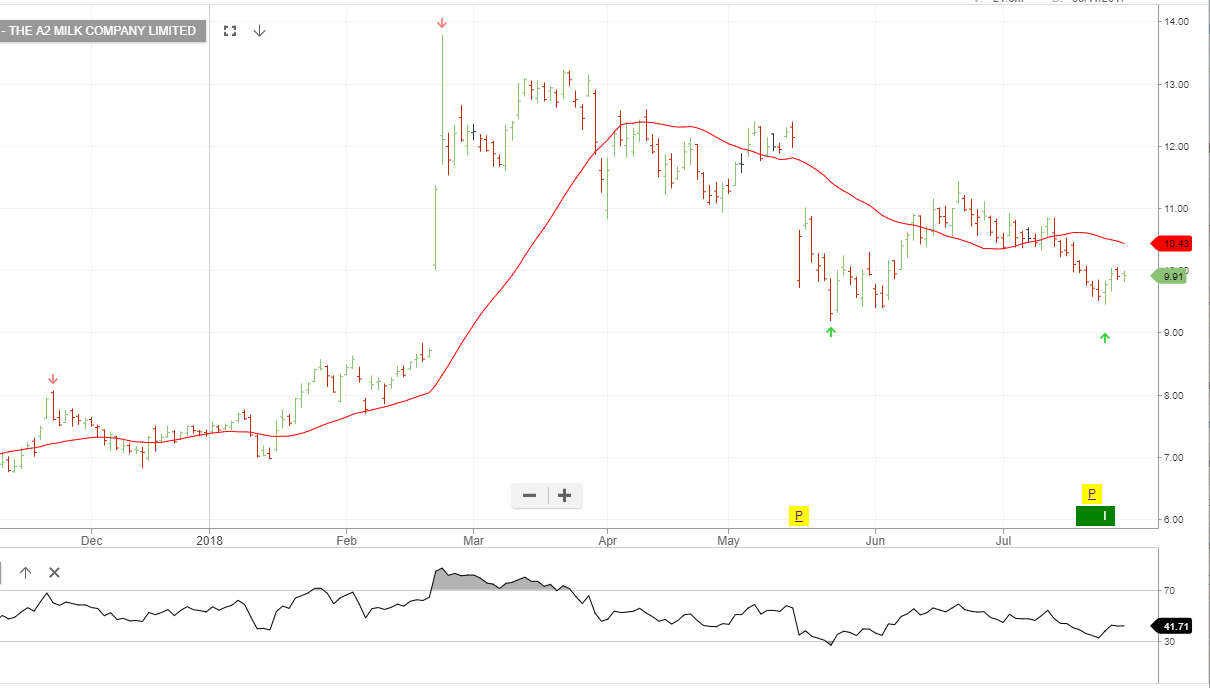
ALGO Update: Stay Long A2 Milk

Our ALGO engine triggered a buy signal in A2 Milk at $9.81 on July 20th.

Since then, a broker note has lifted the company to an “outperform” rating with a 12-month price target of $12.40.

The report focuses on the fresh milk delivery partnership between A2M and Fonterra in New Zealand, and the opportunity to replicate that model in other countries.

As a result, the broker note estimates growth in EBIT to rise from $274 million to $523 million over the next two years.

A2 Milk


Woolworths – Buying Opportunity Ahead

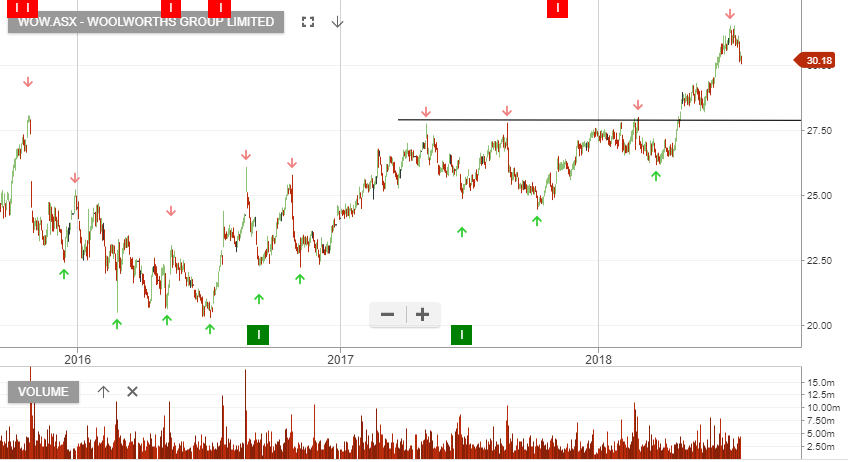
Consensus expectations for the upcoming Woolworths’ earnings result, is for underlying profit to grow by 8 – 10%. This is well above competitors, but hardly supports the current 24 x multiple.

If the sell-off in WOW extends to the downside, we would encourage investors to “load up” on Woolworths. Our target buy range is $28 to $29.

Based on forward earnings WOW trades on 3.2% dividend yield. We’d like to see that increase to 3.6% as the share price retraces. Keep this one on the radar and watch for the next ALGO buy signal.

Woolworths

Downer EDI – High Conviction Update

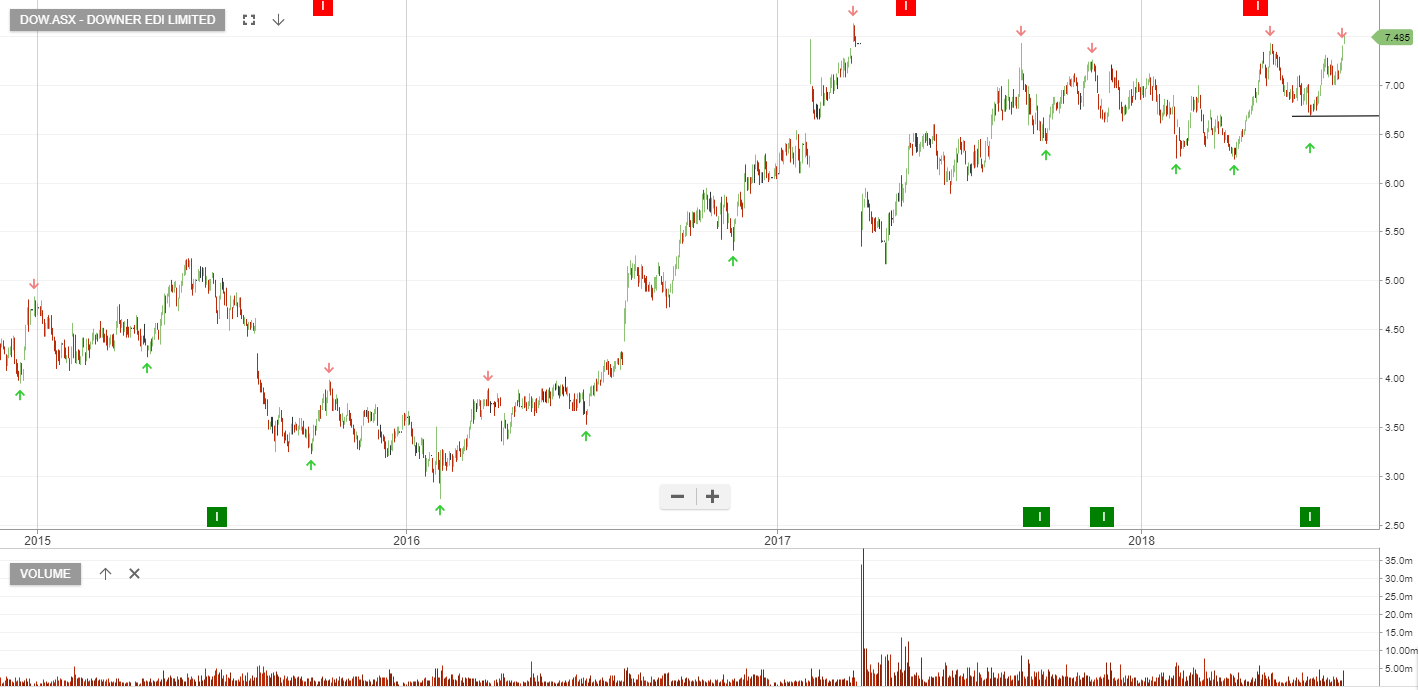
Our Algo Engine generated a buy signal in Downer EDI at $6.75.

With the stock now trading at $7.50 we recommend locking in gains, as the stock is now trading at our initial “sell” price target.

We continue to like the long-term fundamentals for Downer and CIM and will revisit these names on the next retracement & algo buy signal.

Downer EDI


BHP Firms On US Asset Sales

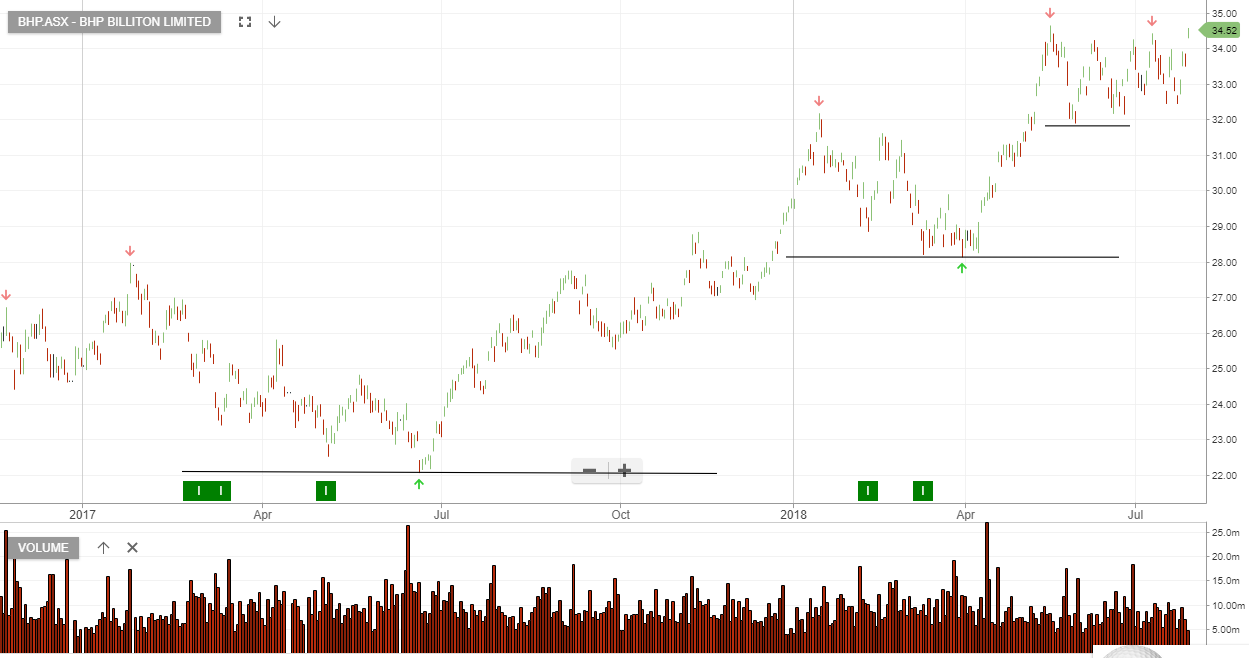
Shares of BHP have jumped over 2% to $34.50 in early trade following the announcement of the sale of their onshore shale assets in the USA.

British Oil giant BP will pay USD 10.5 billion for the bulk of the energy assets, while Texas-based Merit Energy will buy the other $300 million worth of assets.

The company has pledged that the USD 10.8 billion from the sales will be returned to shareholders, but hasn’t been clear about how and when.

BHP has rallied from the April “higher low” formation and is now trading at the upper range of our price target.

Our advice to blog readers in April was to buy BHP and se  ll the $35.00 strike call options to enhance the cash flow.

BHP

NCM’s Q4 Production Up 15%

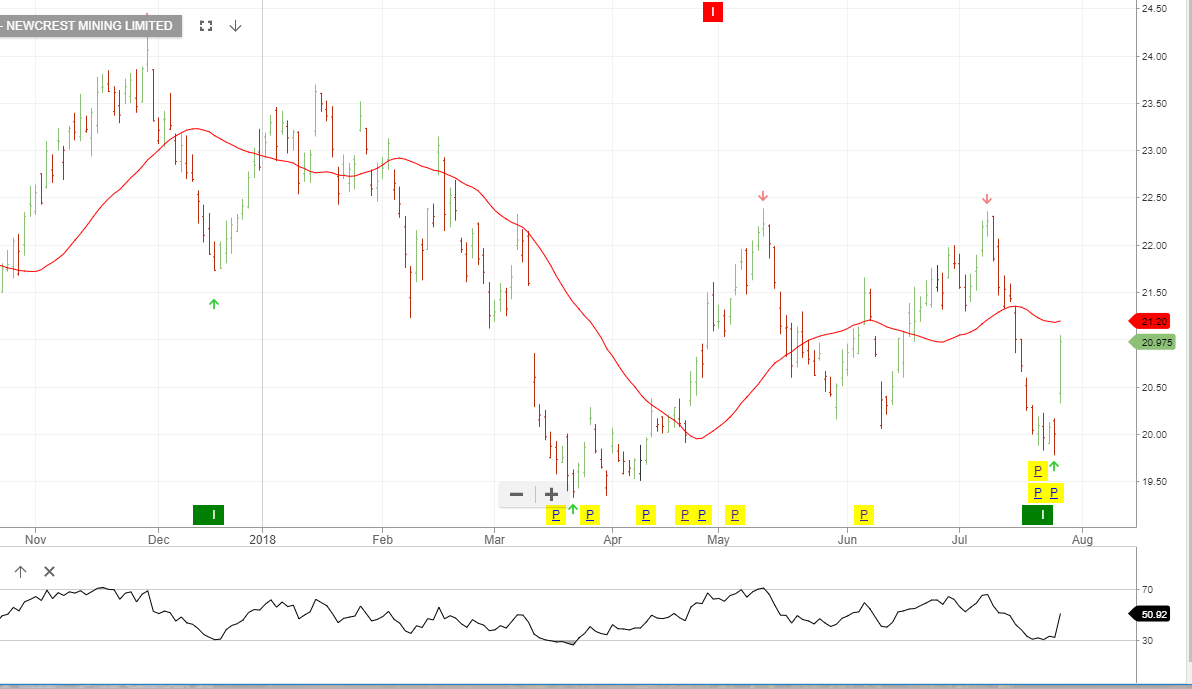
Shares of Newcrest mining have spiked over 4.5% higher to reach $21.00 in early trade.

The catalyst for the move was the release of their Q4 production numbers.

The Gold miner reported their overall production rose 15% for the 3 months to June 30th from 551,000 ounces to just under 635.000 ounces.

This improved result places their full year production in the upper end of their expected 2.25 to 2.35 million ounces. All-in sustained costs were unchanged at $795 per ounce.

We see the next area of chart resistance for NCM near $21.55, with a longer-term target in the $24.25 area.

Newcrest Mining


James Hardie : A Buy/Write Strategy

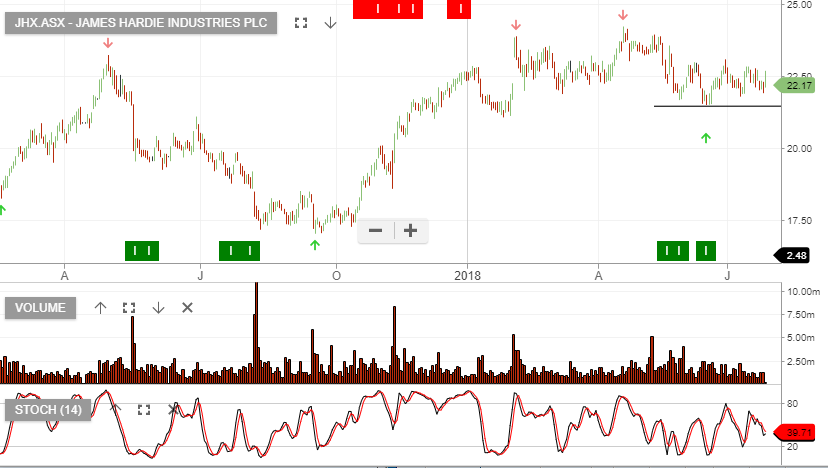
Our Algo Engine generated a buy signal for JHX recently at $21.50.

With the US housing cycle remaining strong, (although weak numbers in June are the reason for some caution), and James Hardie having a dominant market position in fiber cement, we think the long term trajectory for earnings & margins are strong.

FY19 revenues should increase 20% and underlying EBIT will jump from $380m to $480m.

With the stock trading on a low 2.2% forward yield, we recommend adding a covered call option to enhance the income.

Selling the $23.50 October strike adds $0.50 per share of additional cash flow.

JHX goes ex div $0.30 on the 12th of December.


NCM Firms In Front Of Tomorrow’s Quarterly Report

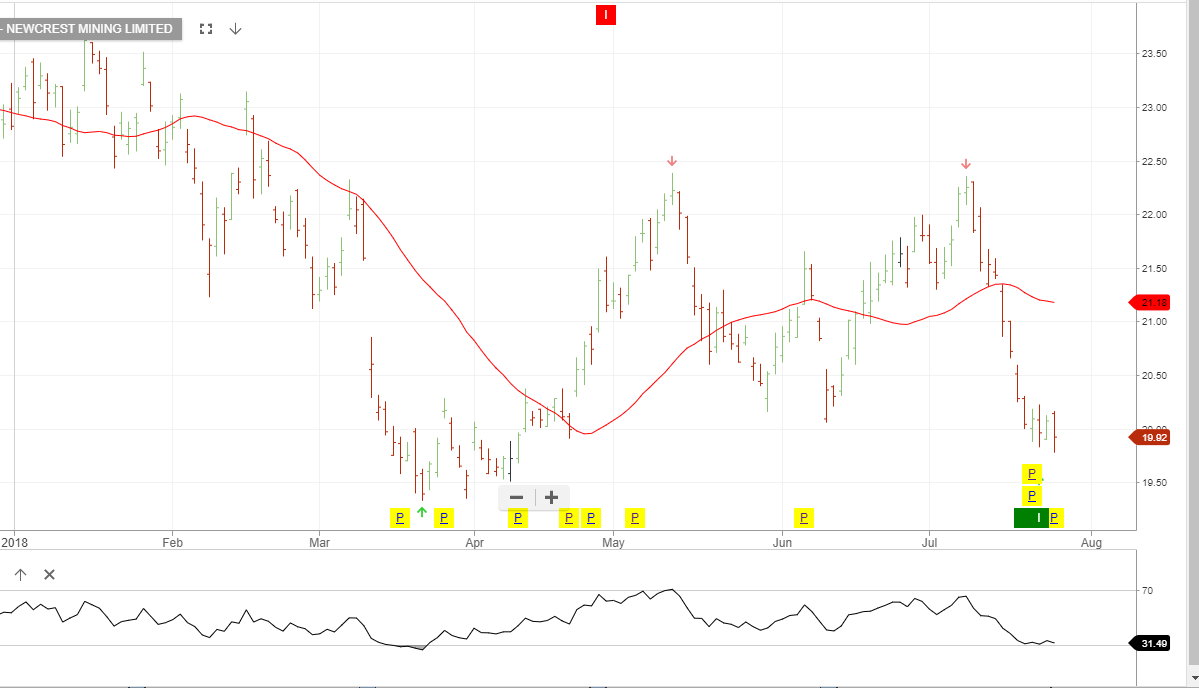
Shares of Newcrest mining are consolidating near three-month lows in front of the release of their Quarterly production report tomorrow.

Our ALGO engine triggered a buy signal on NCM on Monday at $20.04 and the stock has been added to our ASX Top 50 model portfolio.

The recent slide in Spot Gold appears to be finding support around the $1200.00 area, which is a net positive for the stock.

We have a medium-term upside target for NCM in the $24.25 area.

Newcrest Mining