Buy Star Entertainment

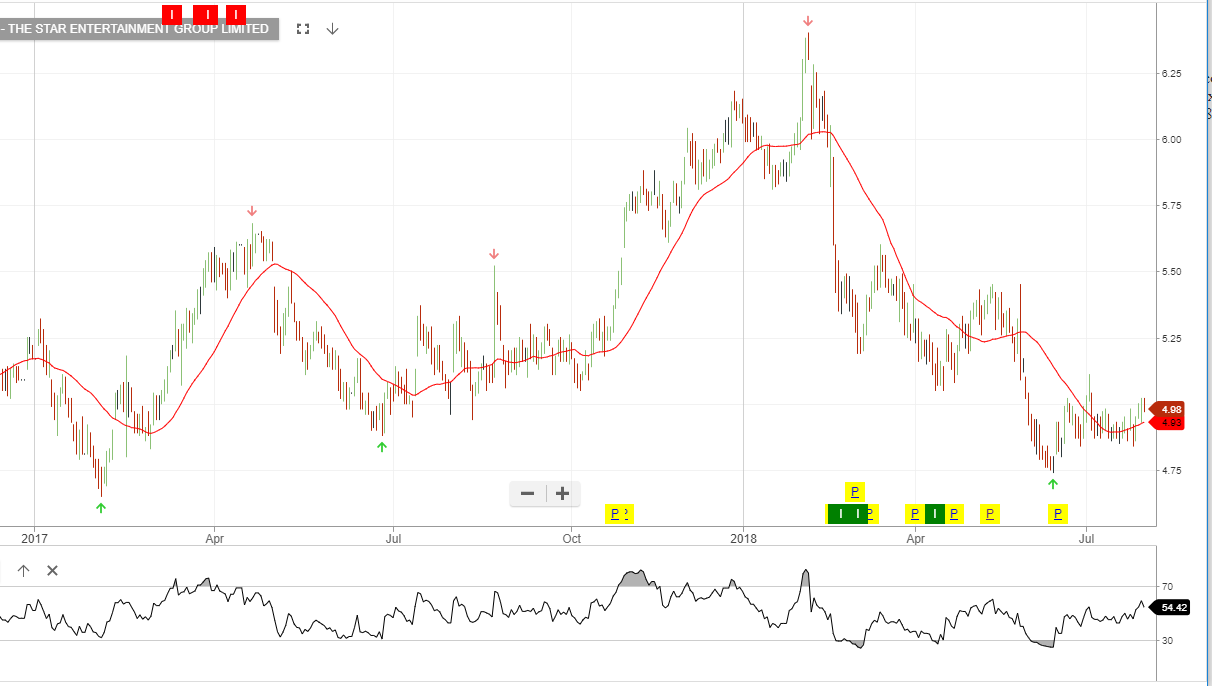
Star Entertainment reports FY18 earnings on the 24th of August and consensus forecasts are expecting underlying NPAT of $255 million, up 15% on the same time last year.

The  1 to 3 year outlook for SGR supports ongoing EPS growth of 10% +, placing the stock on a forward FY19 dividend yield of 4.5%.

SGR is a current holding within our ASX 100 Model portfolio.
Star Entertainment Group
 

ALGO Buy Signal For RIO Tinto

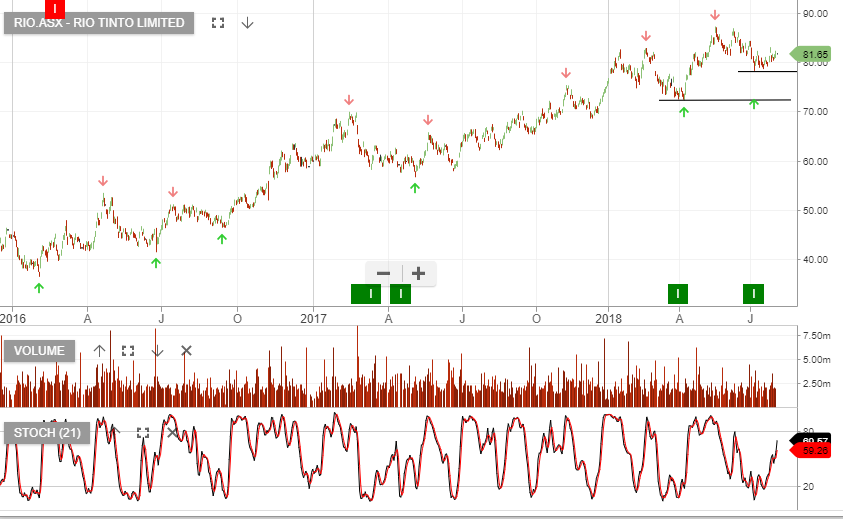
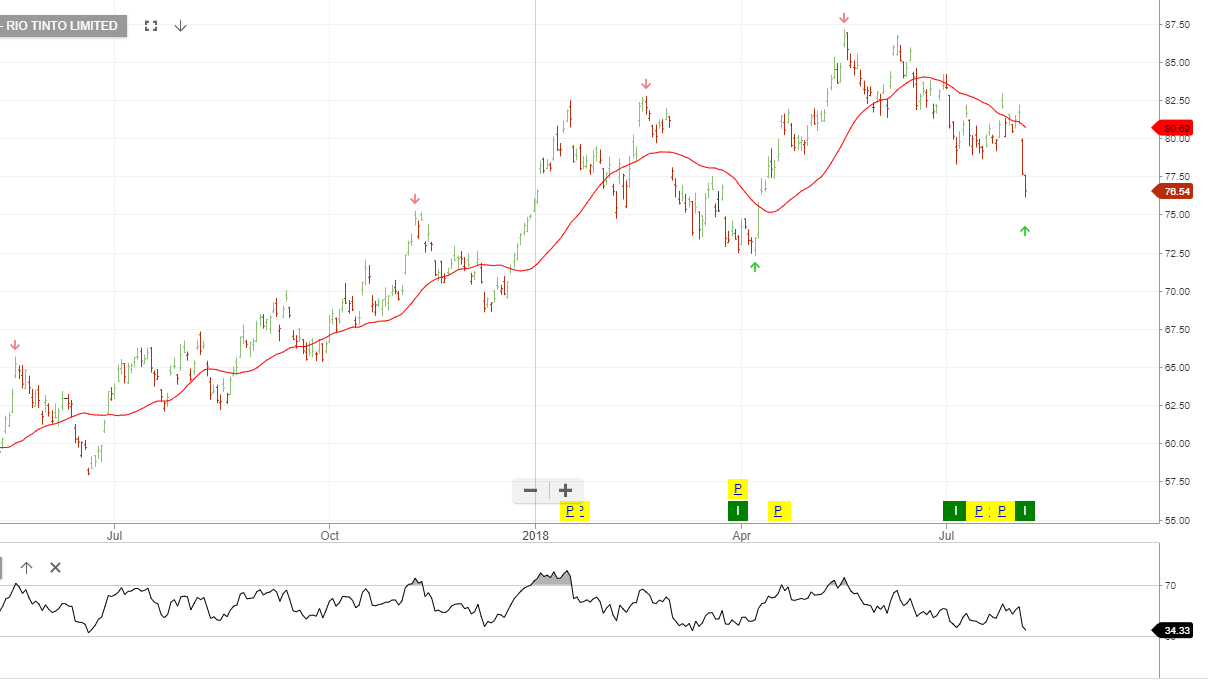
Our ALGO engine triggered a buy signal for RIO Tinto into the ASX close yesterday at $76.50.

This “higher low” chart pattern is referenced to the intra-day low of $72.30 posted on April 9th.

Despite the announced expansion of their share buyback program, RIO’s share price slid more than 5% last week to hit a 3-month low of $76.15.

We calculate that the stock is currently on a 4.5% yield and will go ex-dividend for US $1.70 on Thursday the 9th of August.

From a technical perspective, we see solid support in the $73.25 area.

Rio Tinto


Crown Firms In Front Of Next Week’s Earnings Report

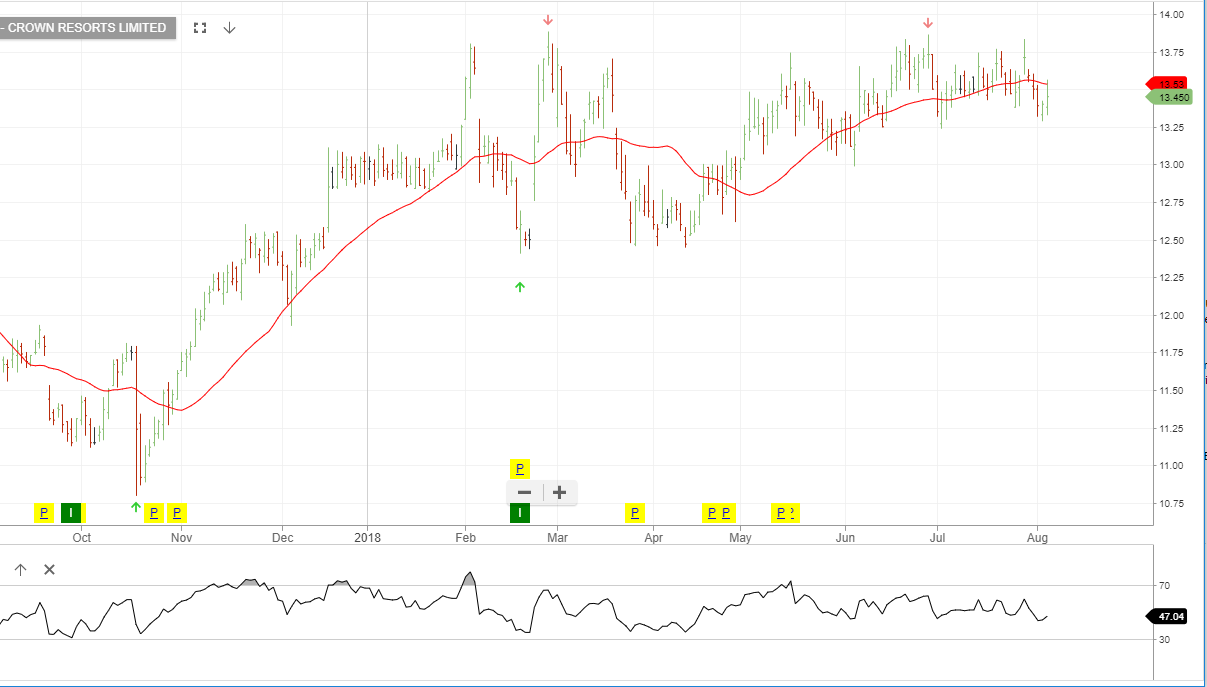
We followed an ALGO buy signal for CWN back in February at $12.60.

However, over the last few months, the stock has traded in a relatively narrow range between $13.80 and $13.25.

With the company reporting full year earnings next Thursday, we see the potential for the stock price to trade up through the top end of the range.

We expect CWN to beat the consensus NPAT forecast of $370 million as operations in both Victoria and Sydney could print higher numbers.

CWN goes ex-dividend for 30 cents on September 21st and we see the next upside target neat $14.25.

Crown Resorts

ALGO Update: Stay Long James Hardie

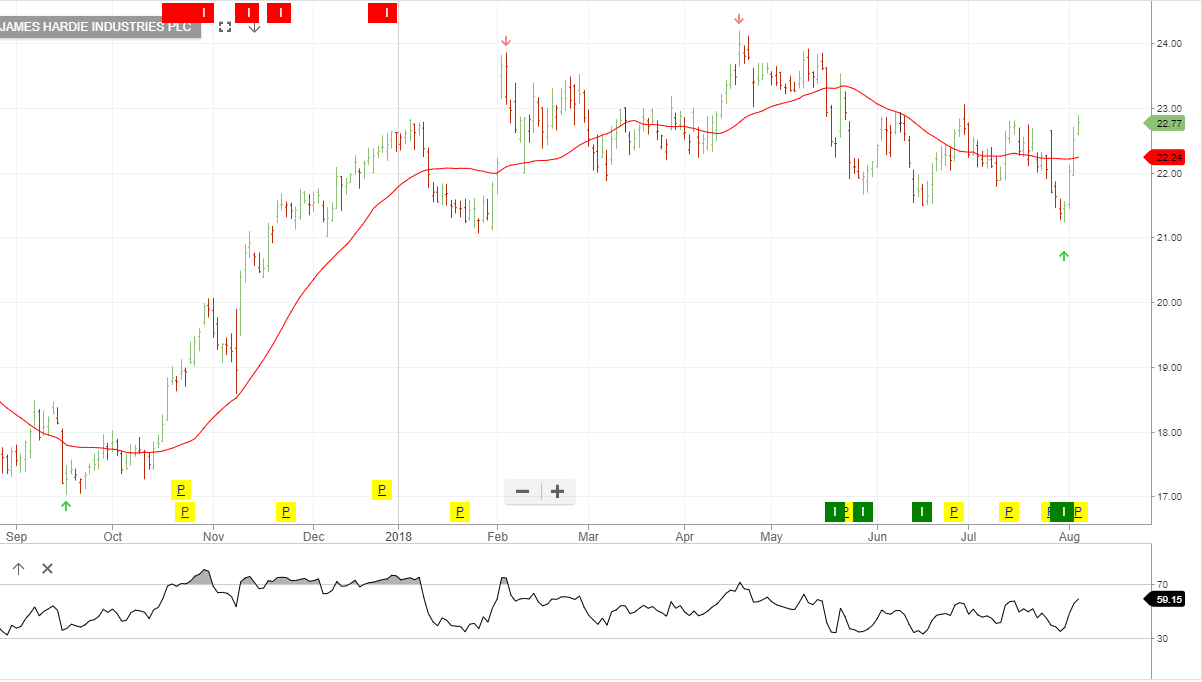
Our ALGO engine triggered a buy signal for JHX on July 31st at $21.50.

Since then the stock has picked up almost 6% and is over 1% higher at $22.75 in early trade today.

The company will release their Q1 FY19 results next Friday.

Expectations are that the EPS should rise to 67 cents per share on stronger earnings.

Our initial upside target is the May 16th high near $23.85.

James Hardie

CBA Continues To Slide In Front Of FY18 Earnings Report

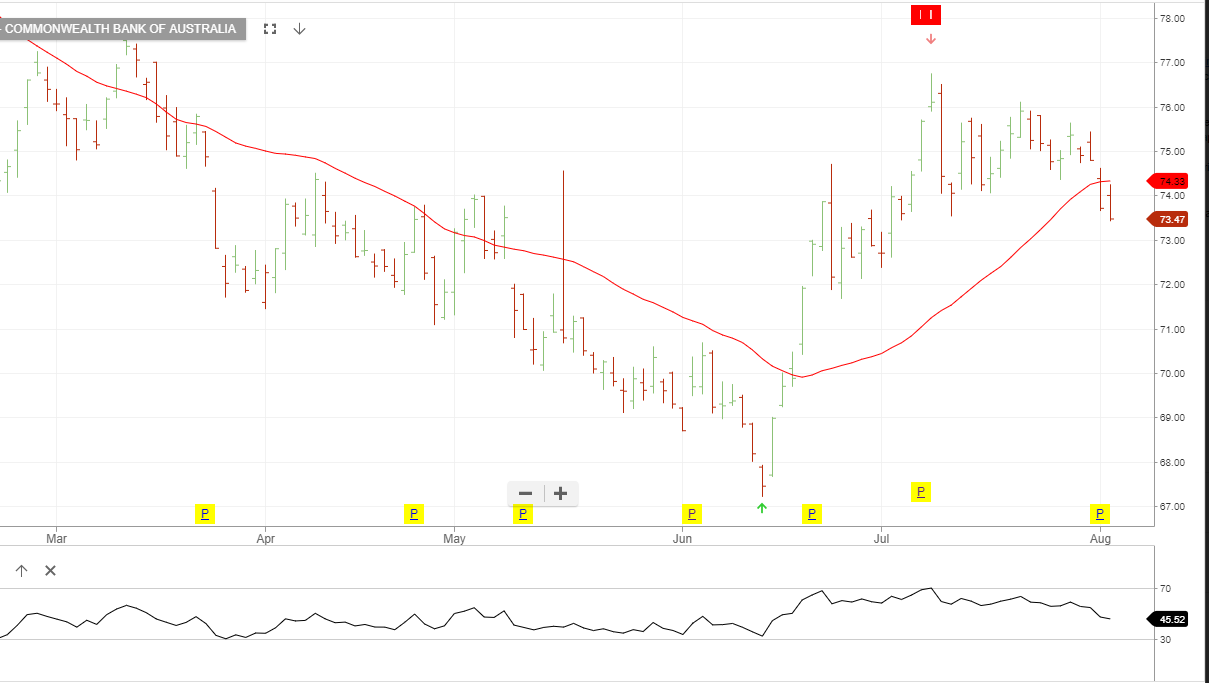
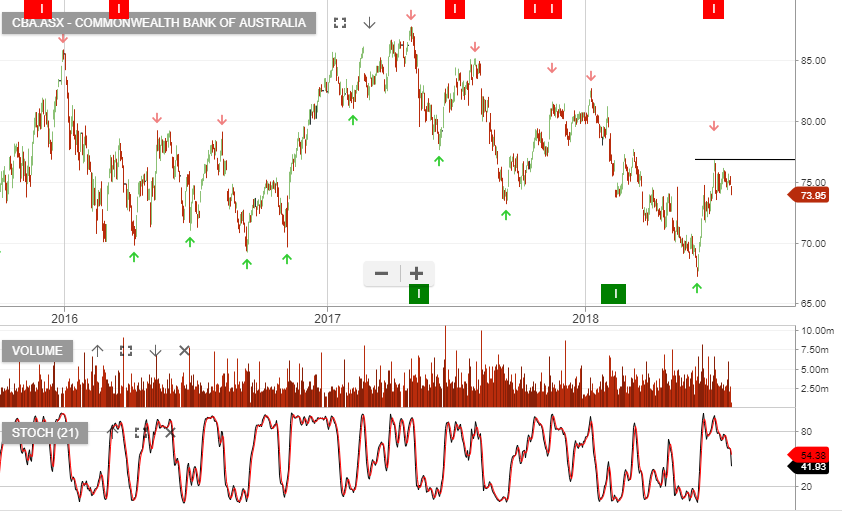
Our ALGO engine triggered a sell signal for Commonwealth Bank on July 9th at $76.10.

Since then the stock has lost over 3% and reached $73.50 in early trade today.

CBA is scheduled to report its FY18 result next Wednesday.  The early forecast is for NPAT to print at $9.5 billion and DPS to be flat near $2.30.

There are three key reasons why we believe the earnings risk is skewed to the downside in this report.

The AUSTRAC settlement of $327 million, margin pressure from short-term funding costs and a disappointing 4% loan growth in June.

Technically, the CBA chart has followed a “lower high” pattern since since mid-January and has dropped over 10% during that time.

We continue to hold a bearish bias toward the banks, in general, and expect CBA to test the June low trade of $67.50 over the medium-term.

CBA

RIO – Sell A Call Option To Deliver 10% Cash Flow

RIO’s 1H 2018 earnings result was slightly below the consensus forecast with underlying EBITDA of US$9.2 billion.

If we assume flat earnings and dividend growth over the next 12 months, it places RIO on forward yield of 4.5%.

Returning cash to share holders through an increased share buy back program, (largely proceeds from asset sales), will help to underpin RIO’s current share price.

We recommend investors add a covered call option to enhance the income returns.

RIO goes ex-dividend US$1.70 on the 9th August.

Rio Tinto


Sell Signal In Bank Shares

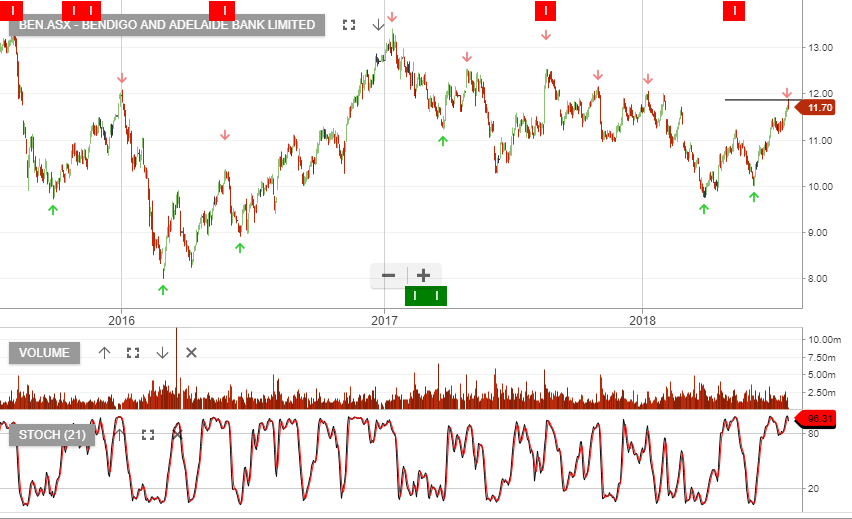
All four major banks, and the regional names, are now displaying Algo Engine sell signals. Currently we have no bank long holdings within our model portfolio.

Within the financial sector our preference remains for ASX and IAG. Both offer a fully franked dividend yield, and when combined with a covered call, we’re generating 10 – 12% annualized cash flow.

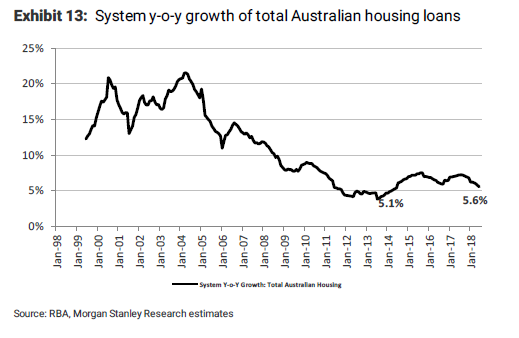
Our concern about the low ROE for the domestic banks is driven by weak housing loan growth and the rising cost of funds. These conditions keep us cautious on the banks, especially when combined with the present group of ALGO sell signals.


EVN – Moving Into Our Target Retracement Zone

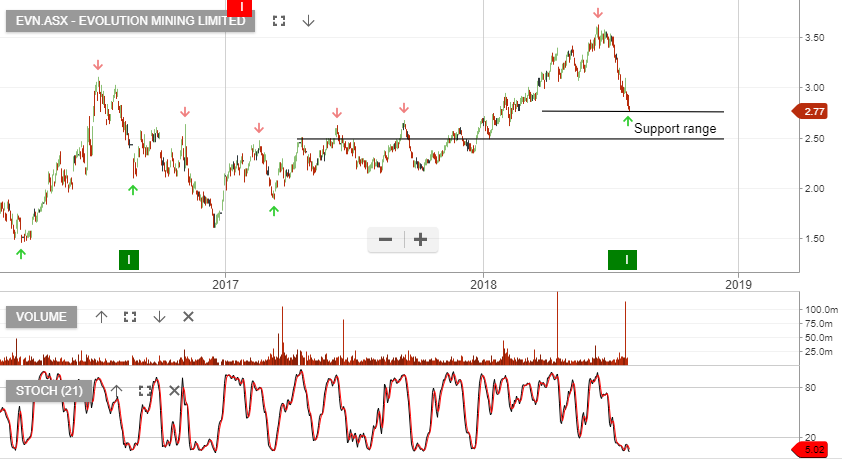
EVN has been on our watch list with a target retracement zone within the $2.50 – $2.75 range.

The share price has now traded at the upper band of our target and investors can now consider a partial allocation in EVN.

Should the stock trade down to the $2.50 – $2.60 area, it will then make it onto our high conviction list.

Evolution Mining


ORG – 4Q Production Beats Consenus

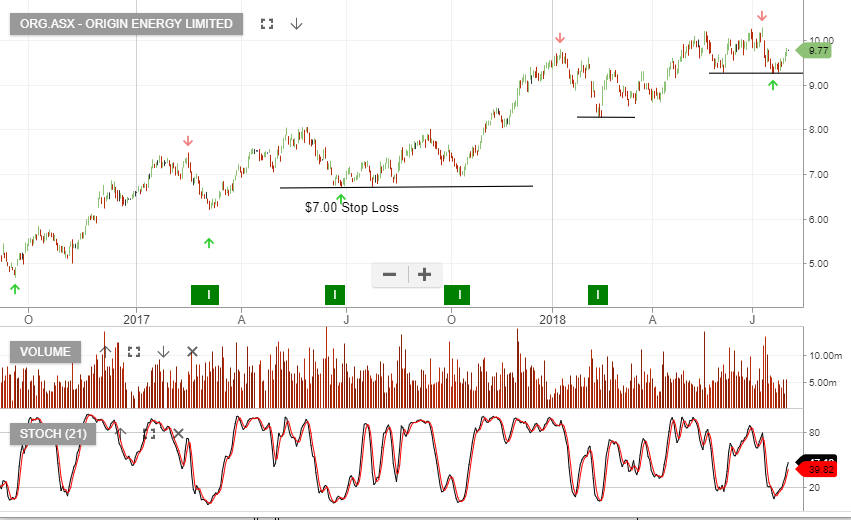
Origin continues to form “higher high and higher low” price structures and remains one of the best performing stocks in our model portfolio.

The recent 4Q production report helps support the earnings recovery and we feel the share price trades within the $9.50 – $10.50 range.

4Q18 revenue of A$570 million was ahead of consensus with higher volumes and higher realized domestic LNG prices.

FY18 revenue is forecast at $15 billion, EBITDA $3 billion, EBIT $1.5 billion generating EPS of $0.55 per share.

In FY19 we expect earnings to grow by 20% and the company to payout 50% in dividends, placing the stock on a 3% forward yield.

In FY20, both increasing profit and payout ratio will then lift the dividend to $0.60 per share placing ORG on a FY20 yield of 5.5%.

Origin Energy

Star Group Rising Into FY 18 Earnings Report

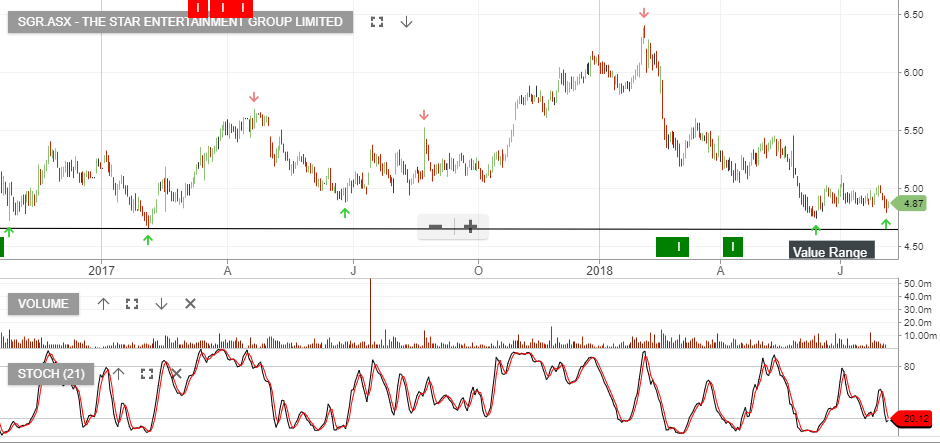
Shares of Star Entertainment have reclaimed the $5.00 handle for the first time in three weeks as investors get positioned for the FY 2018 earnings report due out on August 24th.

Over the last two weeks, SGR has had nine buy ratings and two hold ratings from local broker names.

The company operates casinos in Sydney, Brisbane, the Gold Coast and also manages the Gold Coast Convention Center on behalf of the Queensland Government.

SGR is one of the largest beneficiaries of tourism inflows into Australia, which means their hotels and developments could significantly raise future earnings.

The stock is currently trading at 8.7X FY19e EBITDA and we believe their FY 2018 earnings could surprise to the upside.

SGR was added to our ASX Top 100 portfolio and we see scope for a move back into the $5.70 range over the medium-term.

Star Entertainment Group