Chart Watch – Dow Jones
The Dow Jones continues to trade in a sideways consolidation pattern, which began in early March. With the index closing at 21080, the price is now pushing against resistance at the top end of the consolidation channel.
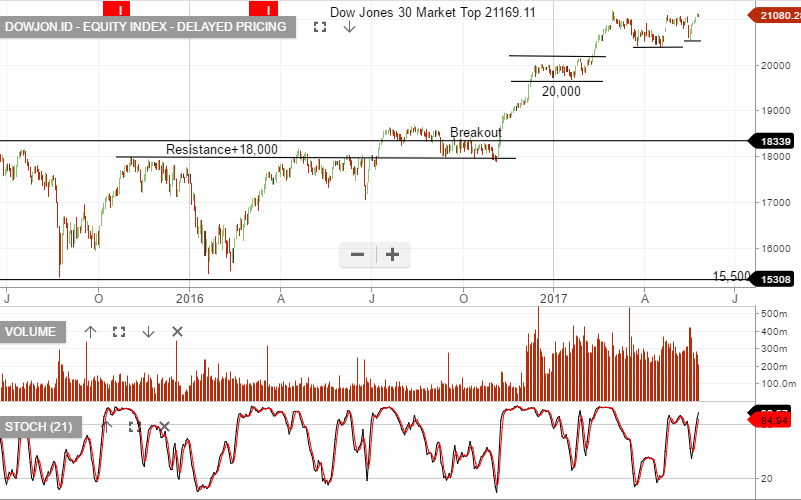
The Dow Jones continues to trade in a sideways consolidation pattern, which began in early March. With the index closing at 21080, the price is now pushing against resistance at the top end of the consolidation channel.
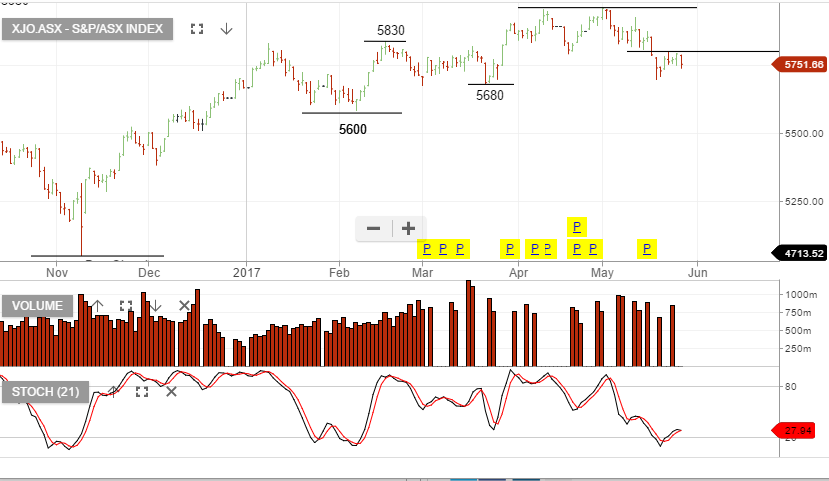
The XJO continues to find selling pressure below the 5795 high reached earlier in the week.
The AUD/USD ended the week with a softer tone at .7450, as S&P lowered the credit scores of 23 Australian financial institutions and Moody’s downgraded China’s sovereign credit rating.
This week’s retail sales and manufacturing data will have an impact on the next move in the Aussie.
Investors looking to profit from a lower AUD/USD can buy the BetaShare inverse ETF with the symbol: YANK.
The current price of YANK is $15.08. When the AUD/USD fell to .7330 on May 9th, the price was $15.55.
We estimate that when the AUD/USD trades down to the January low of .7160, the unit price for YANK will be approximately $16.50.
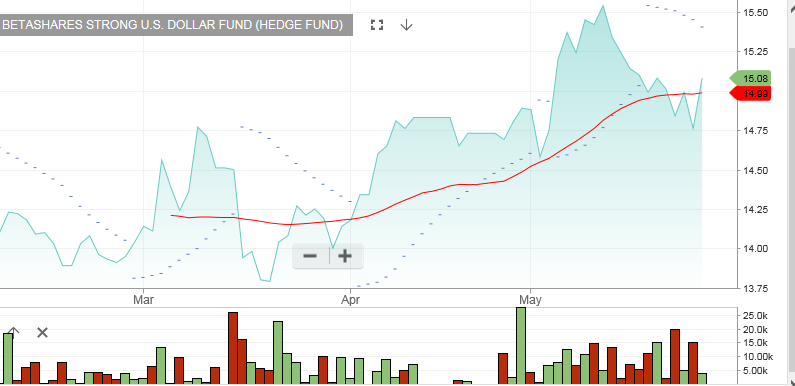 BetaShare YANK ETF
Since the beginning of May, shares of the “Big 5” banking stocks have dropped between 8 to 10%.
We expect to see a bounce of some degree in the near-term, but it’s difficult to predict which name will see the most significant rebound.
For investors looking to take a step back into the long side of the banking sector, we suggest the Vaneck banking EFT with the symbol: MVB
This Exchange traded fund has dropped from $30.00 on April 27th the current price of $27.30. We believe a small allocation at these levels, for a bounce back to $28.75 would represent a solid “tactical” trade.
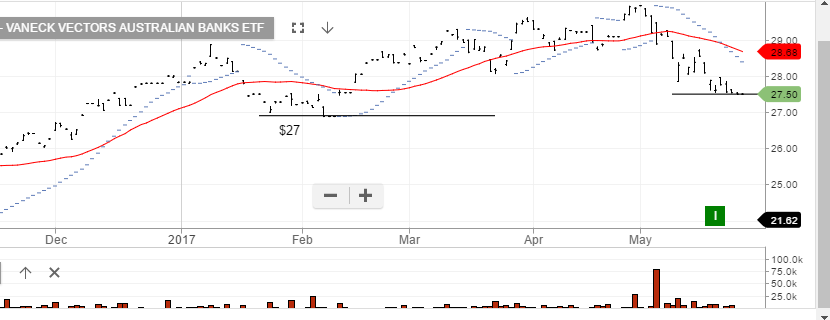
MVB Aussie Bank ETF
Shares of Ansell (ANN) reached a 5-month high of $25.30 yesterday as a Chinese consortium agreed to buy part of their non-core asset group for $800 million.
In announcement after the agreement, ANN officials outlined a plan to buyback up to 10% of the company’s common stock over the next 12 months.
We believe this development will underpin the share price to the downside. However, $26.00 could could be a difficult level to clear, even with the buyback.
With today’s sharp sell off into the $23.00 handle, ANN shares are a good candidate for a buy/write strategy. Selling the $26.50 calls into December will enhance the returns, and keep investors exposed to the August dividend of approximately 32 cents.
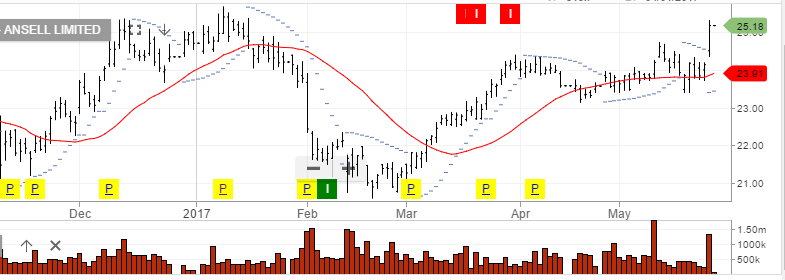
Ansell
Did you know, that as a subscriber, you can always take a sneak peak at Leon’s personal charts? It’s pretty easy…
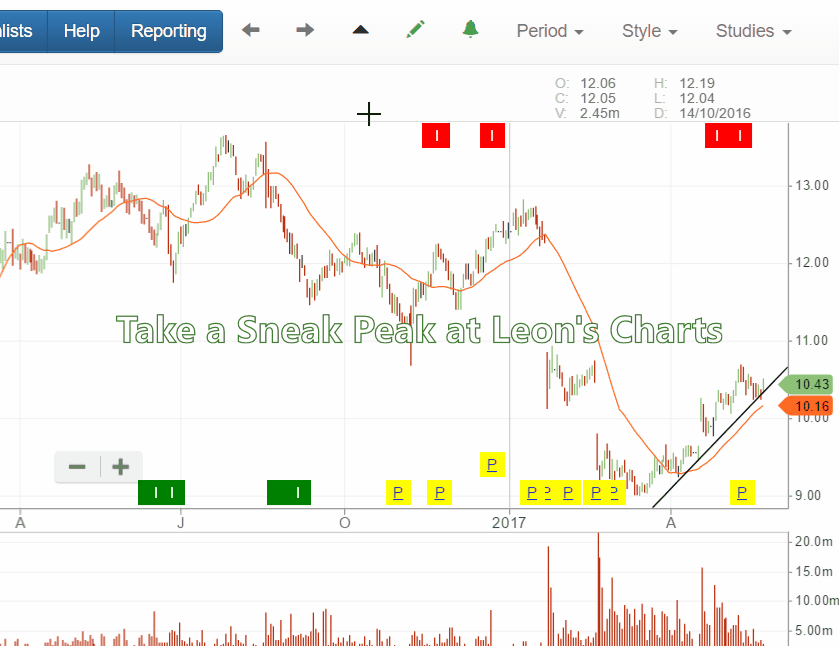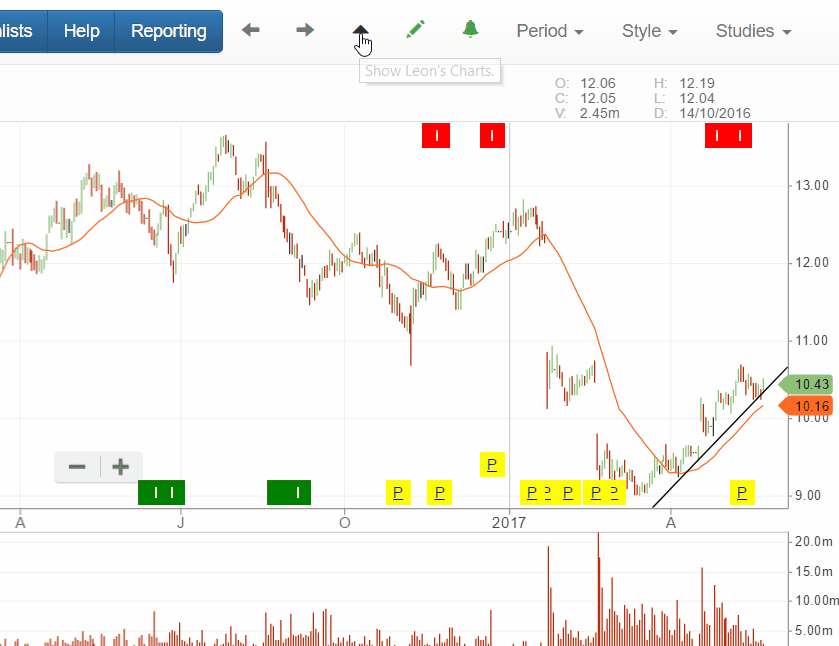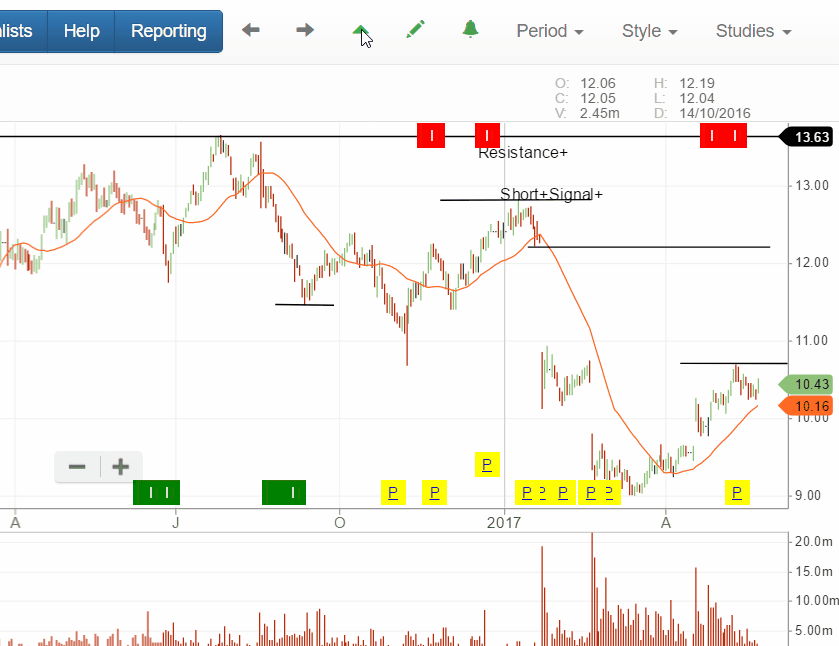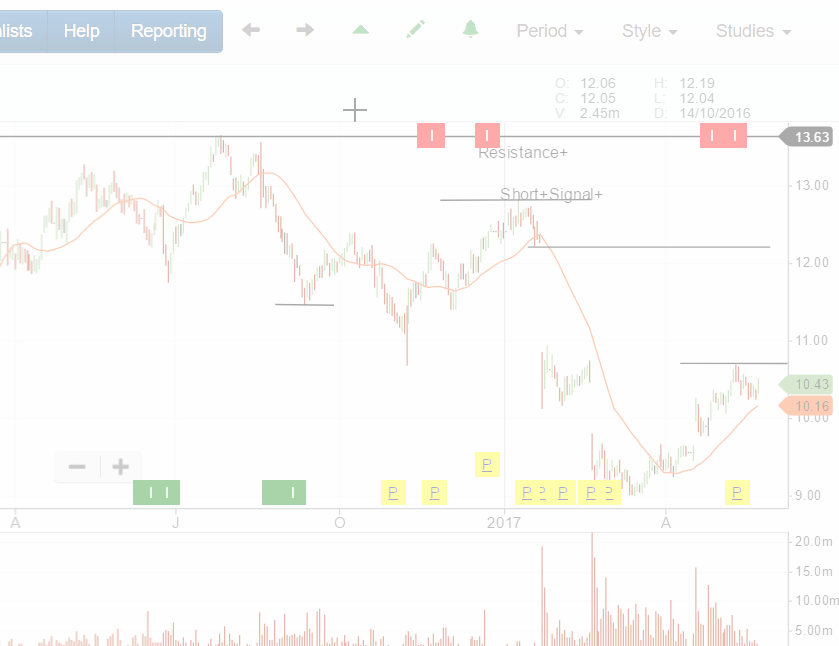
If you’re not a subscriber, then register for our Free Trial to try it out today or get in touch with us.
If you are already subscribed, then try it out now.
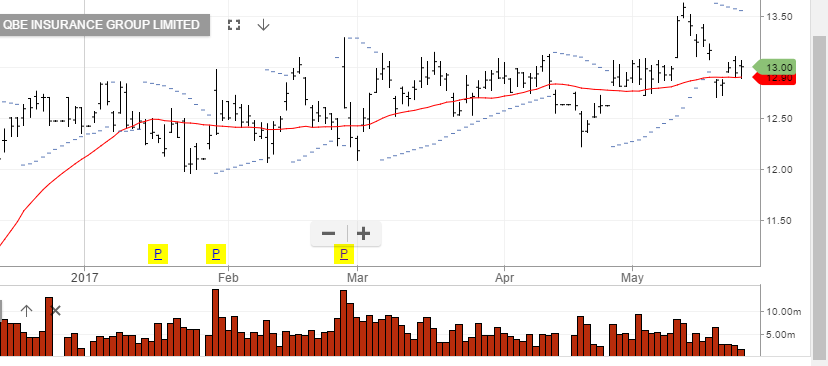
QBE Insurance posted an $844 million net profit on May 3rd, which was their best result since 2010.
By May 11th, the share price had raced to a new high for the year at $13.60.
With internal momentum indicators beginning to turn lower, we are suggesting to exit long positions or sell the $13.50 covered calls into September.
We expect to see good support in the $12.00 area as a medium term target.
QBE
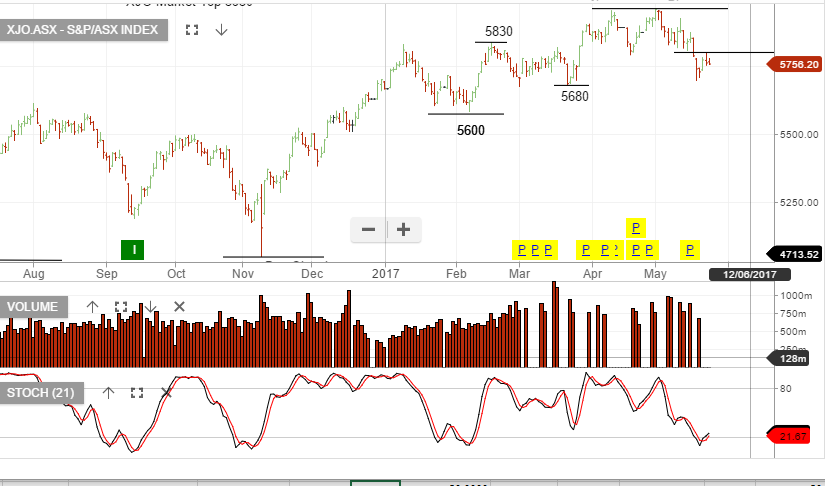
As an update to our recent Chart Watch on the XJO, we highlight again the lower high structure that has now formed. We were expecting a bounce into the 5790 – 5850 level before further selling pressure. Yesterday the price action hit resistance at 5796 and today’s open looks weak against a positive lead from the US.
.
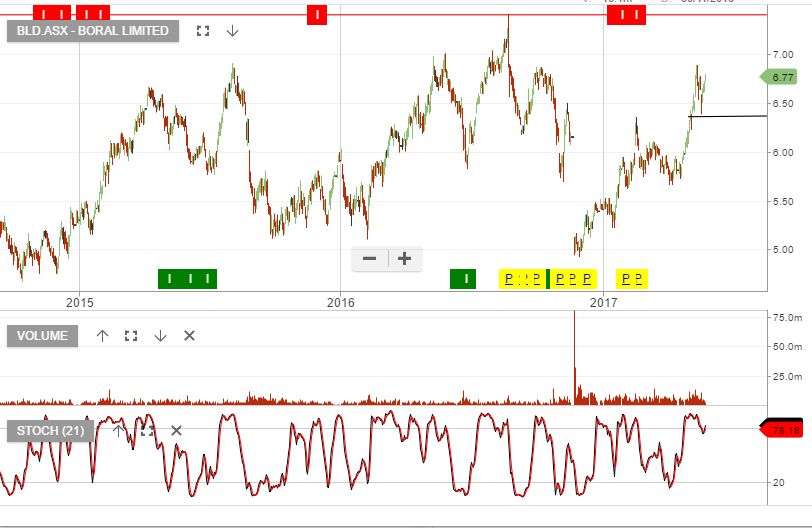
The market remains optimistic about future earnings growth for Boral. The recent Headwater acquisition in the US provides Boral with added exposure to the US housing market. Domestically, Boral is well placed to benefit from the an increase in large scale infrastructure projects.
We feel some caution is warranted though, given the weaker trends emerging is both US and domestic housing construction data. The stock trades on 19x forward earnings and less than a 4% yield.
FY18 revenue is likely to be $5.8b, EBITDA $1.15b, Net Profit $490m and DPS of $0.29.
Since trading as high as $23.20 on May 2nd, shares of JHX have dropped over 14% and are now trading below $19.80.
We posted a report on the blog on May 19th pointing out that JHX reported FY17 results which were below market expectations.
Overnight, US New Home Sales fell to 569,000, well short of the consensus expectation of 610,000. As new home construction continues to slide, we sell further downside range extension for JHX.
The new key support level comes in near the February low of $18.20.
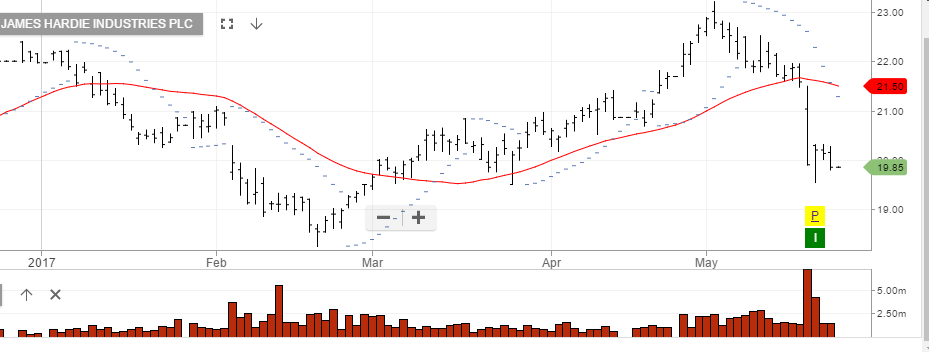 James Hardie

Level 17 Chifley Tower
2 Chifley Square
Sydney, NSW 2000
1300 614 002
Investor Signals Pty Ltd
ABN 44 143 555 453