Woodside Petroleum – Valuation Review

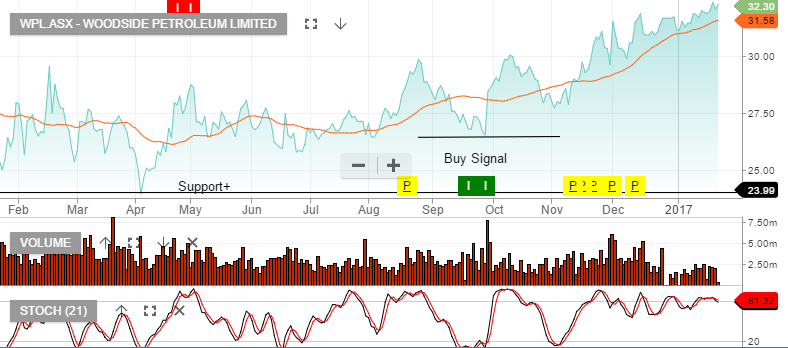
Woodside reported DecQ16 Production above market estimates on stronger LNG production. The result was driven by a stronger-than-expected performance from North-West Shelf & Pluto LNG.

The production beat helped DecQ16 revenue which increased to US$1 billion

CY17 production guidance will see volumes down 5- 10%. This is mainly due to the reduction in Woodside’s share of the NWS Joint venture.

2017 forecast revenue US$3.9b (flat on previous year), EBIT of US$1.5b, net profit of US$1b, EPS of US$1.30 places the stock on a forward yield of 4%.

Chart – Woodside


Wesfarmers: Coal versus Coles

Given the number of diversified business units which make up Wesfarmers, we believe the most accurate method of share valuation is to look at performance of the sum of the businesses.

At this point, the valuation equation can be reduced to a simple question: Will the increased revenue from higher coal prices offset the loss of market share that Coles has given up to Woolworth’s?

We expect the resource division to generate first-half EBIT of $135 million, which is in the lower part of the $135-$140 million guidance band. Conversely, we have downgraded Coles’ sales growth which reflects industry checks suggesting Woolworth’s won the the Christmas-period grocery trade.

2017 forecast $69 billion, EBITDA $5.5 billion, net profit $2.8 billion, which will produce EPS of around $2.40 reflecting underlying growth of 5%. This places the stock on a forward P/E of 16X and a dividend yield of 5.5%.

ETF Watch – Inverse Index ETF’s

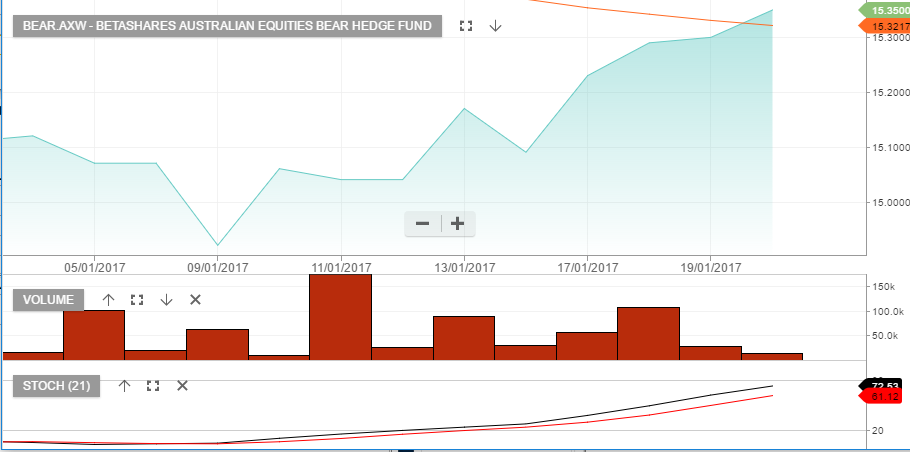
An inverse index ETF is an Exchanged Traded Fund which increases in value when the index trades lower. For portfolio hedging purposes, we use the ASX200 inverse ETF which is listed under the code BEAR. To hedge US stock exposure, we use an inverse ETF based on the S&P500.

Because of our concerns about inflated valuations in certain pockets of the global markets, we feel now is the time to draw our clients attention to these increasingly popular financial products.

Inverse ETFs  are way of cost effectively hedging a portfolio and/or profiting from a move lower in Stock indexes

Chart – BEAR ETF (ASX200 Inverse)
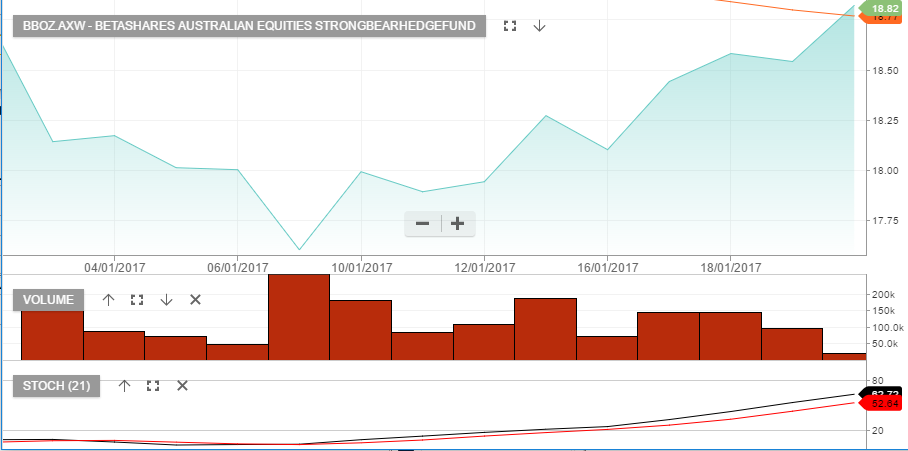
Chart – BBOZ ETF (ASX200 x2 Inverse)
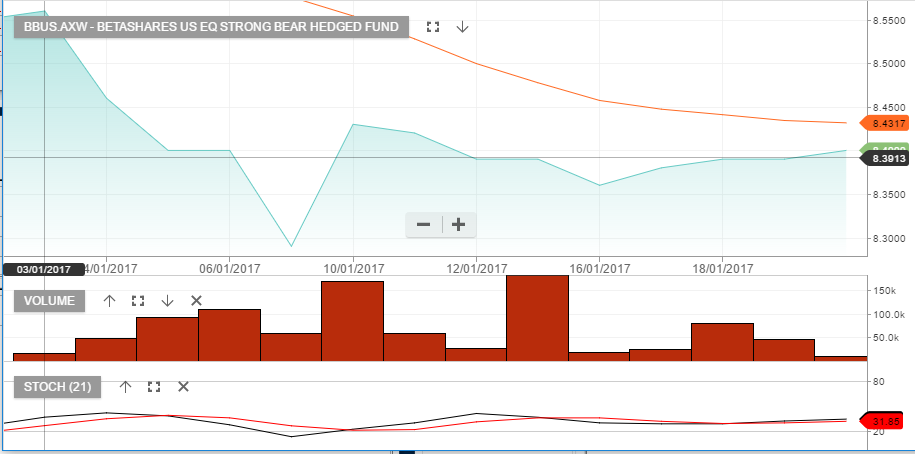
Chart - BBUS ETF (S&P500 x2 Inverse
Chart – BBUS ETF (S&P500 x2 Inverse)


US Earnings Update: AMEX and IBM

Computer giant IBM announced Q4 earnings well above street estimates but lower revenue numbers pressured the stock price lower.

Big Blue reported non-GAAP earnings per share of $5.01 compared to the consensus figure of $4.88. Revenue for Q4 came in at $21.77 billion versus expectations of $21.66 billion. Cloud platform revenue continued to increase which allowed the firm to beat full-year estimates and reach $13.59 in annual earnings per share.

However, despite beating the the Q4 estimates for revenue, overall revenue growth has now dropped for the 19th consecutive quarter. This negative trajectory for overall earnings growth contributed to the sharp intra-day price reversal in IBM shares.

After trading as high as $171.15 after the headline announcement, shares closed lower on the day at $163.50. The next key technical level is found at the December low near $158.00.

American Express reported Q4 earnings which fell short of analysts’ expectations.

The credit card issuer posted adjusted earnings of 91 cents per share on quarterly revenue of $8.02 billion. The street expected earnings of 98 cents per share on revenue of $7.95 billion. In addition, net income fell 8% on a year-on-year basis to $825 million.

AMEX shares have rallied over 20% since hitting the October low of $60.00. We see the business environment improving for for the firm going into 2017. As such, we would expect to see good technical support in the $67.00 area.


Key US Earnings Reports

Goldman Sachs surprised to the upside with Q4 EPS announced at $5.08, which was well above the market estimate of $4.73 and nearly 4 times the EPS of $1.27 reported a year ago. This was based on quarterly earnings of $8.17 billion versus forecasts of $7.76 billion.

Like other banks in the sector, Goldman benefited from a sharp uptick in trading activity. Net revenues from the institutional client services division were up 25% from a year ago, led by a 78% increase from the fixed-income, foreign exchange and commodities unit. Goldman shares closed down $1.45 at $234.

Citigroup had a mixed report with Q4 earnings beating expectations, but missing on their revenue figures. The banking giant announced EPS of $1.14 on revenue of $17.01 billion. Analysts were expecting EPS of $1.12 on revenue of $17.26 billion.

Trading revenue was higher at $3.20 billion, but considerably below the expectations of $3.45 billion. Fixed-income revenue also missed to the downside with Q4 reported at $2.21 billion verses an expected $2.83 billion number. Shares of Citigroup closed down 1.7% at $57.40, well below the one-year high of $61.50 posted January 4th.

Shares of NETFLIX posted an all-time high of $135.15 as earnings were marginally better than expectations, but the number of new subscribers increased sharply. The on-line entertainment company announced Q4 earnings of 15 cents per share on revenue of $2.48 billion.

These numbers were slightly better than the street’s forecast of 13 cents per share on revenue of of $2.47 billion.

More importantly, NETFLIX exceeded its own subscriber growth estimates by gaining 7.05 million new subscribers versus estimates of 5.2 million. This represents the biggest quarterly gain in the company’s history and triggered the initial rally in their shares. By the close, the share price had settle back to $133.25
Banks to Deliver Low Growth

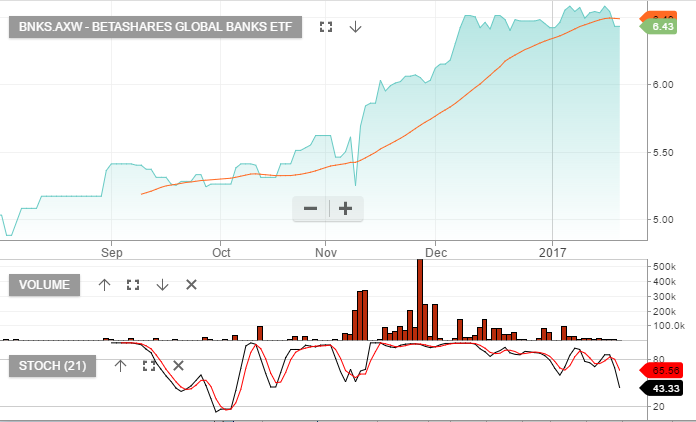
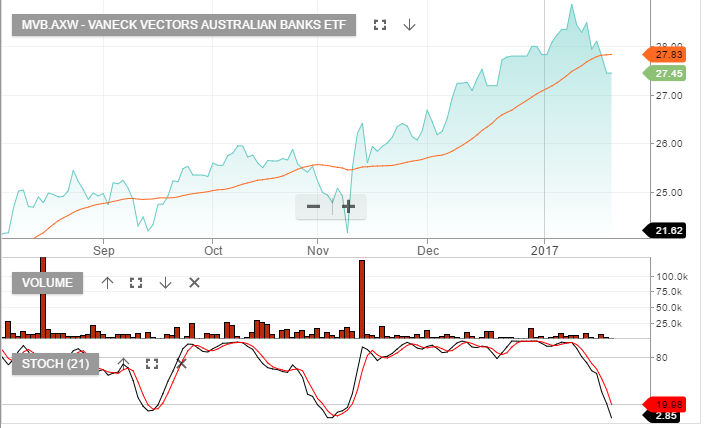
The market has priced in a better and brighter outlook for the Australian  banks during the past 6 months.

During the middle of last year, we had off-shore hedge funds shorting our banks. Concerns about capital requirements, bad debts ticking up from one-off corporate failures and concerns about the Australian property market nearing peak prices.

Six months later and the market is thinking about better underlying conditions, reduced risk of capital raising, improving credit quality from the recovery in commodity prices and better operating margins. As a result, the valuation discount has now diminished following the 20% rally in bank names.

Our base case is that the environment has not actually changed materially from where we were 6 months ago. The news flow has turned more positive but that’s about it.  The underlying issues remain the same or are intensifying, in our view.

We watch with interest the Chinese markets and in particular the risk of weaker property prices in China and the sentiment impact it will have on Australia. This is one of our key risks to Australian bank prices in 2017.

We expect low levels of credit growth due to over-leveraged household balance sheets and pressure from  regulators to improve the quality of housing lending.

At best we see the banks at full value; and our most likely investment case is for further weakness driven by a pickup in global macro risk-off sentiment.

Our bank hedge into February/March remains in place and we’re expecting share prices to remain at or slightly below current prices over the coming months. The risk for further share price weakness will likely pickup towards the middle of the year.

Chart – Global Bank ETF

Chart – Australian Bank ETF


RIO Tinto: Better Production Numbers

Following on from our earlier report, mining giant Rio Tinto posted solid Q4 production results with several divisions slightly beating calendar year 2016 guidance and their flagship Iron Ore operations meeting expectations.

More important than the actual production results themselves has been the continued strength of the global commodity price environment, which is driving earnings expectations into a higher range.

As such, it’s reasonable to expect the increase  in cash flow from higher metal prices could see RIO surprise the market with a higher dividend or a share buyback in its upcoming annual result in February.

We expect the exceptional second half strength in Iron Ore, Coal and to a lesser degree base metals, will help to significantly boost the immediate earnings for RIO.

This increase in revenue has boosted our short-term earnings forecast, which has resulted in an increase in our near-term price target to $65.00.


US Banks – Technical Update

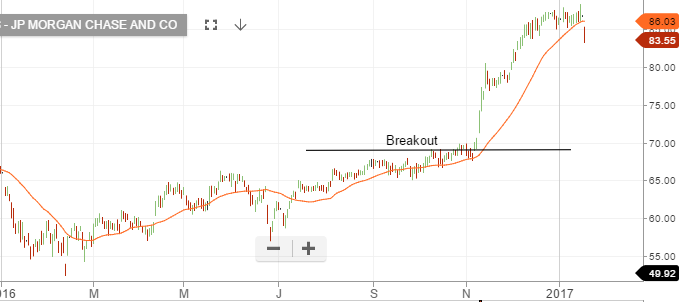
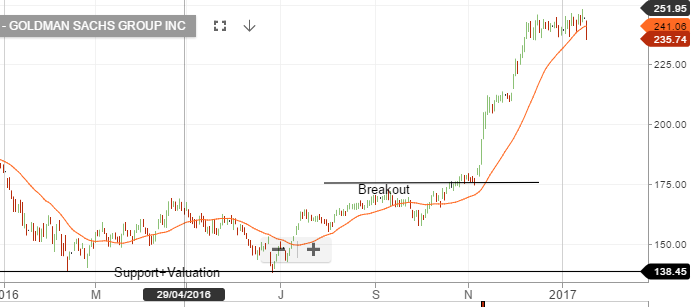
Dow Jones large cap financials JP Morgan & Goldman Sachs were down 3.63% and 3.5% respectively in overnight trade.

The charts below show the price action rolling-over in the past few trading sessions, following the earnings results on Friday that failed to meet market expectations on the revenue front.

This will have ongoing implications for ASX banking stocks. The rally in domestic bank shares were mainly a by-product of the US banking share rally, rather than factors directly related to an earnings pickup within the Australian market.

Chart – JP Morgan


Chart – Goldman Sachs

Crown – Jamie Packer re-joins the board

The share price in Crown Resorts (CWN) has staged a solid rebound since hitting a low of $10.30 in early November. With Jamie Packer re-joining the board and some new capital management initiatives,  there could be further upside from the current price of $11.70.

An analyst report yesterday noted that Melco Crown, in which CWN owns a 11.2% stake, has declared a USD 650 million special dividend to be paid in early February.

Aside from this dividend payment, the gaming giant has lowered its VIP revenue projections, adjusted revenues for CWN’s lower equity stake in Melco, resulting in a lowering of its EPS estimates out to 2019 by close to 2%.

The company’s board reshuffle highlights that CWN has yield and near-term capital management appeal with the prospect of further de-leveraging from offshore strategic initiatives.

Taking into account the trimming of its earnings forecast, the group is trading on 9.3 times fiscal EBITDA projections.