AZJ – Stay on the Short Side
We continue to believe AZJ will come under selling pressure as the company moves to lower the future dividend payout ratio.
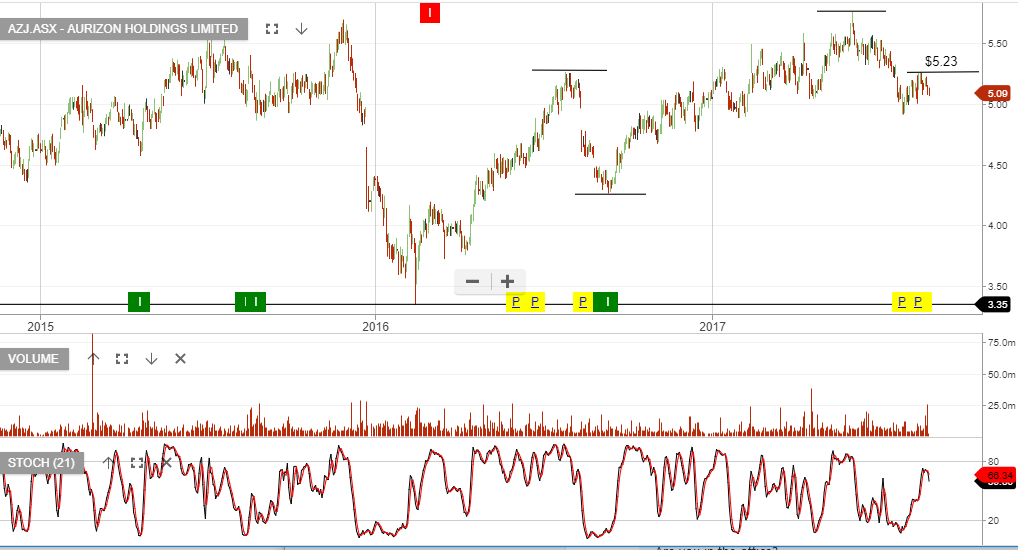
We continue to believe AZJ will come under selling pressure as the company moves to lower the future dividend payout ratio.
Medibank’s FY17 group NPAT of A$450 million was slightly ahead of consensus, largely on higher investment income with a 2H16 dividend of $0.0675 cents per share.
Based on FY18 EPS growth of 1 – 3%, we have MPL on a forward yield of 4.4%.

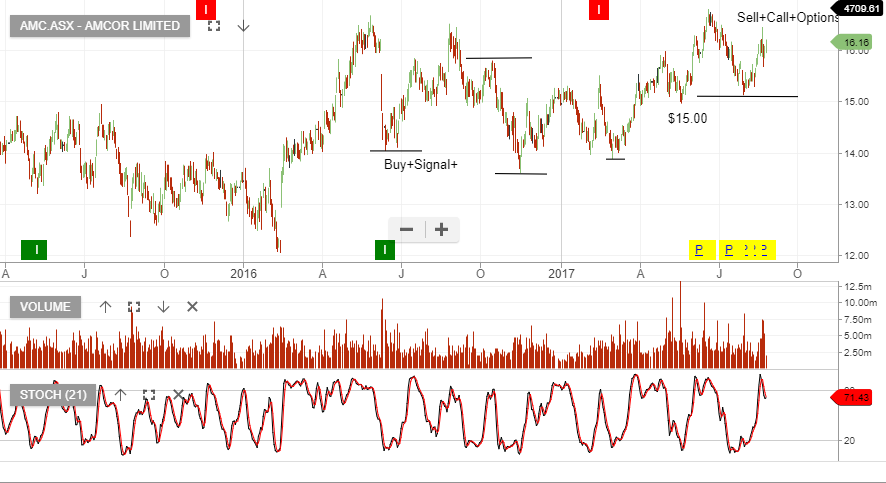
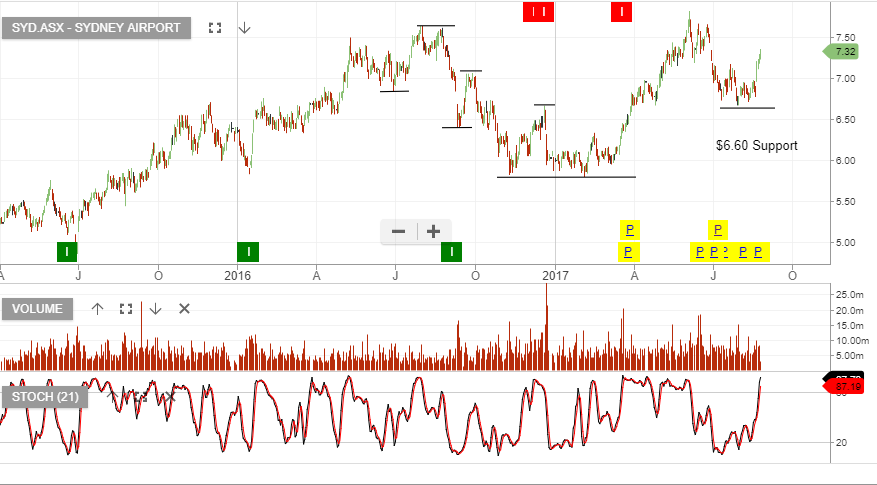
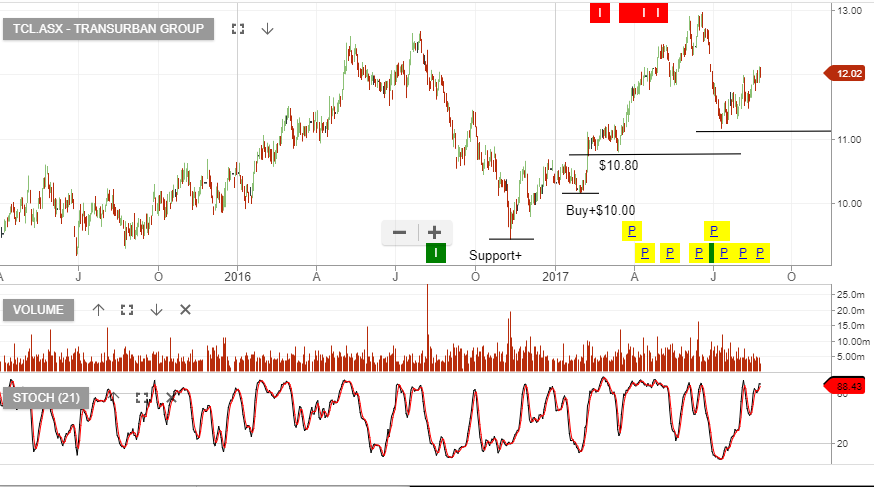
Following recent Algo Engine buy signals, we’ve seen solid price performance in TCL, SYD & AMC.
At the time of the algo buy signal, we highlighted these stocks to members as preferred buying opportunities.
However, we now see the stocks as near full value. Yields have compressed relative to 12 month EPS growth and investors should look to take profit, or sell at the money covered call options.
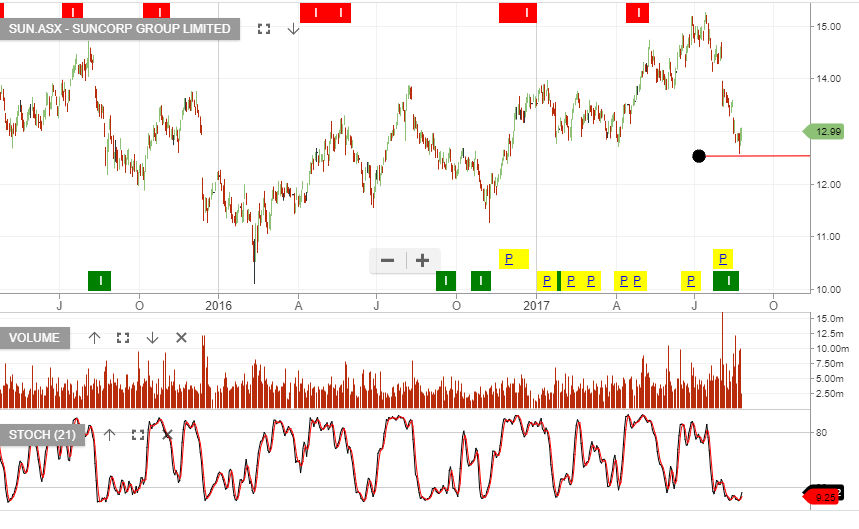
Our Algo Engine flagged a buy signal in Suncorp following the recent sell-off, which has resulted in a 15% price correction.
At $13.00, Suncorp is now forming a “higher low” formation and a technical bounce is likely to occur.
We recommend a stop loss below the $12.58 low.
 SUN
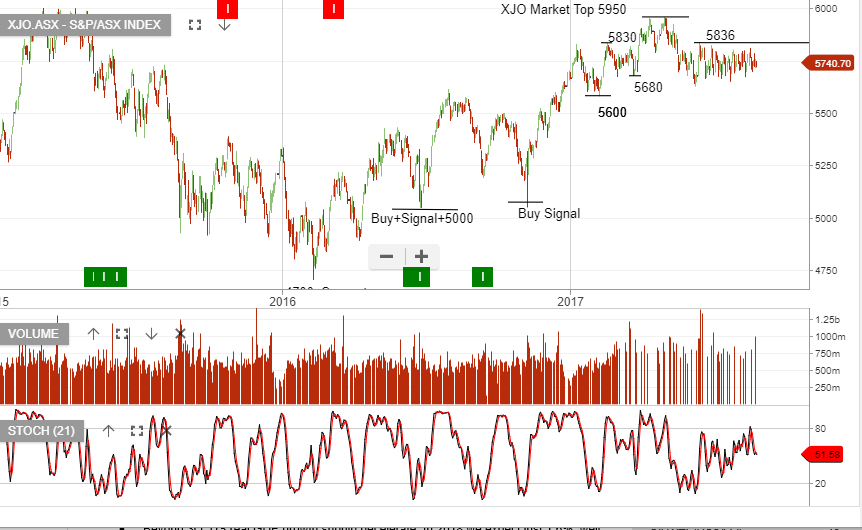
The S&P/ASX 200 Index finished the week down 0.06%.
The best performer was the Energy sector, up 3.8%, and the worst performer was the Property Trusts sector, down 2.4%.
The XJO remains in a “lower high” pattern, following the sell-off from the recent 5836 level.
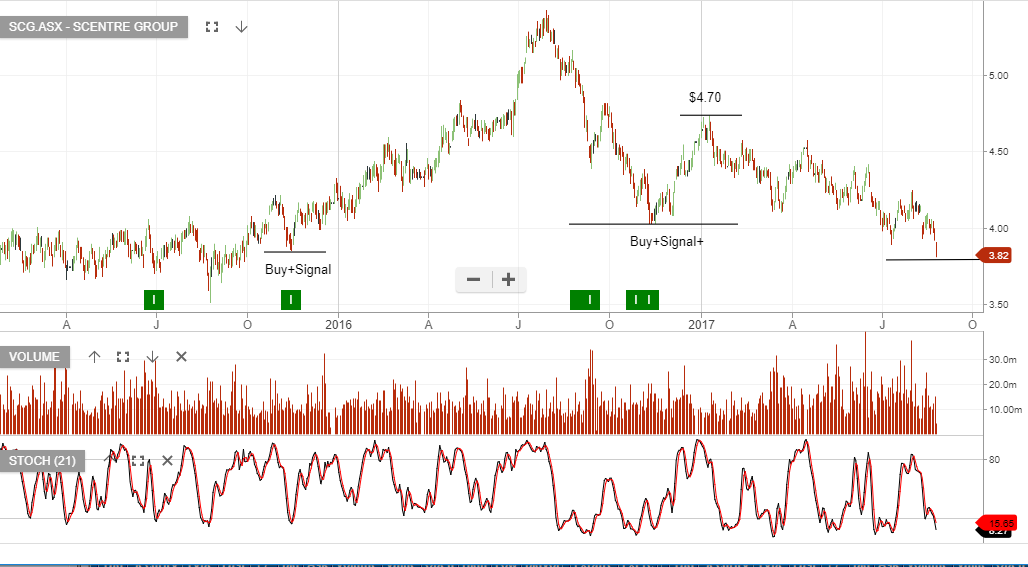
Scentre Group reported 1H17 profit growth of 3.5% compared to the same time last year.
We have the stock trading on a 5.5% yield, based on FY18 distribution of 22 cents per share.
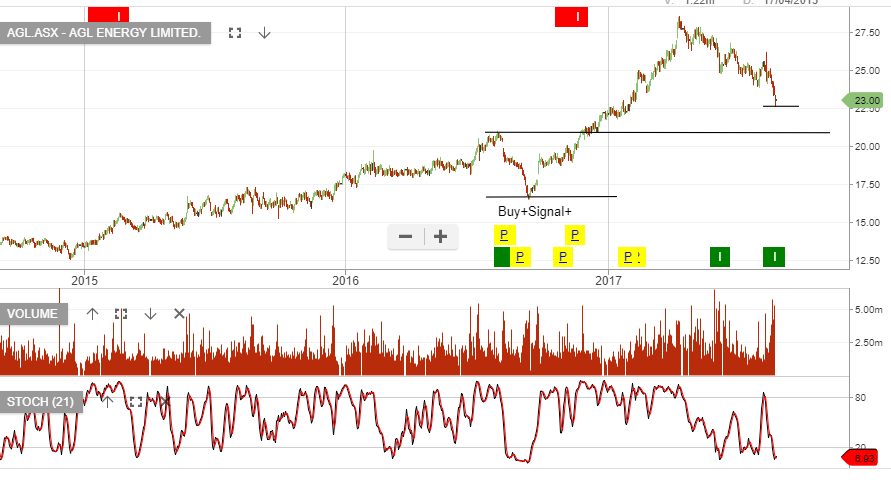
When AGL was trading at $27 back in April, we were warning that the stock was overvalued and suggested that fair value was back at $22.
AGL is now trading $23 and members should be watching for a buy range to develop.
AGL
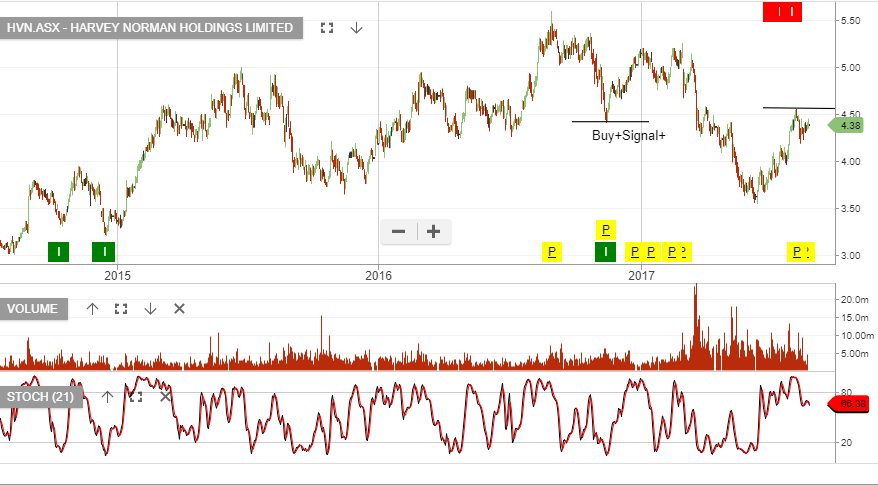
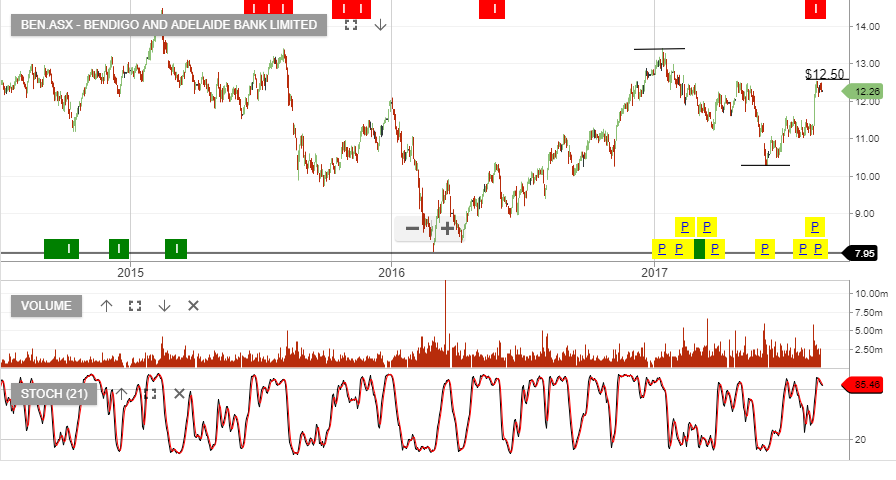
We like the short side of the banks and retailers coming into what will likely be a volatile period for equity markets in September & October.
The regional banks, BOQ & BEN look expensive.
Following their profit announcement on the 31st August, HVN should be on your wishlist as a potential short, with a stop losses above recent highs.
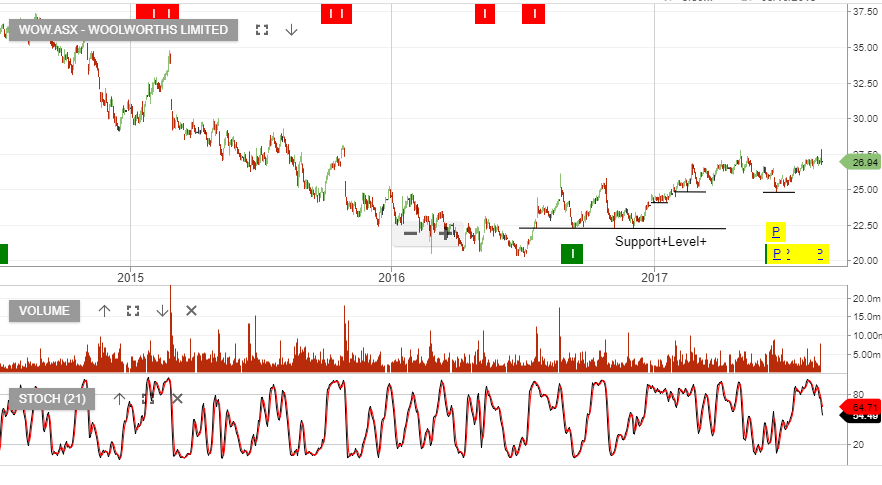
Woolworths announced FY17 underlying NPAT of $1.42 billion, down 3.6% and the company declared a final dividend of 50 cents, which includes the one-off item from the sale of Masters. The higher dividend is not likely to recur in FY18.
The market is now looking for WOW to grow NPAT in the range of 5 – 8% and payout approximately $0.90 in full year distributions, placing the stock on 22x forward earnings and 3.1% dividend yield.
We feel WOW is now fully valued and holding the stock can only be justified when an at-the-money covered call is overlaid to boost the annualised cash flow to 10 – 12%.
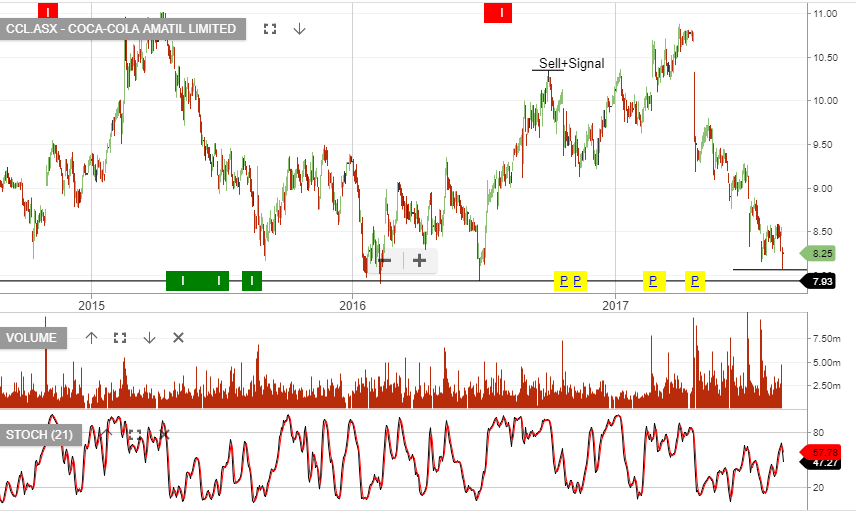
Coca Cola announced 1H17 underlying NPAT fell 4.3%, to $190 million. The company declared an interim dividend of 21 cents, which is 75%
franked.
Forward guidance suggest relatively flat EPS will continue with full year NPAT expected to be $420 million.
Indonesia and PNG are delivering improved earnings metrics and we have the company on a forward dividend yield of 5.4%, assuming 44 cents in annualised DPS.

Level 17 Chifley Tower
2 Chifley Square
Sydney, NSW 2000
1300 614 002
Investor Signals Pty Ltd
ABN 44 143 555 453