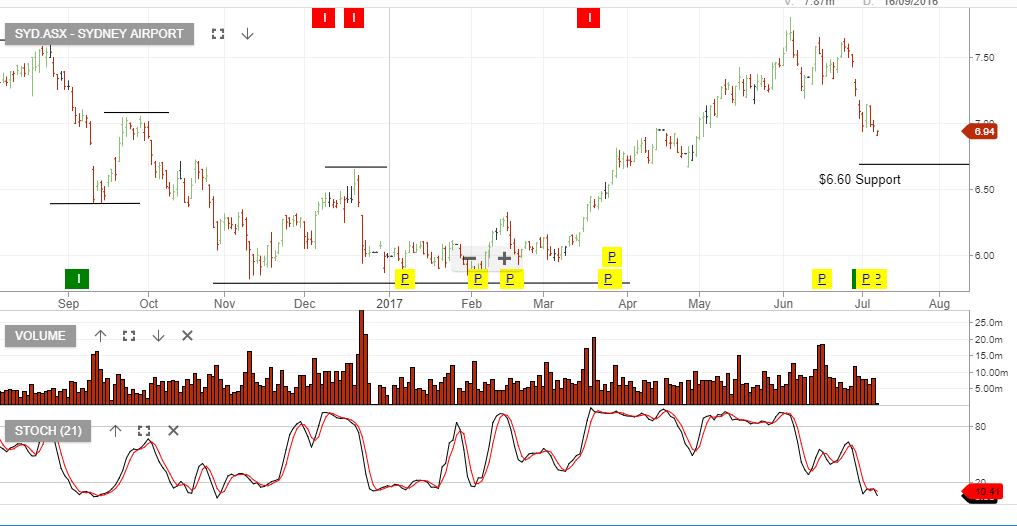
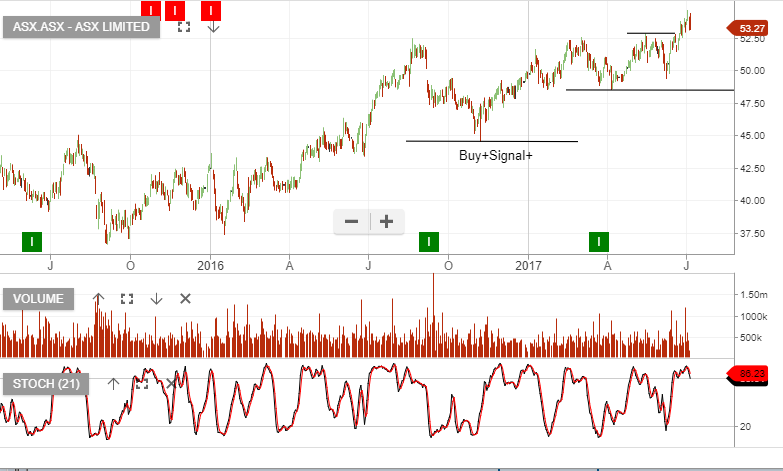
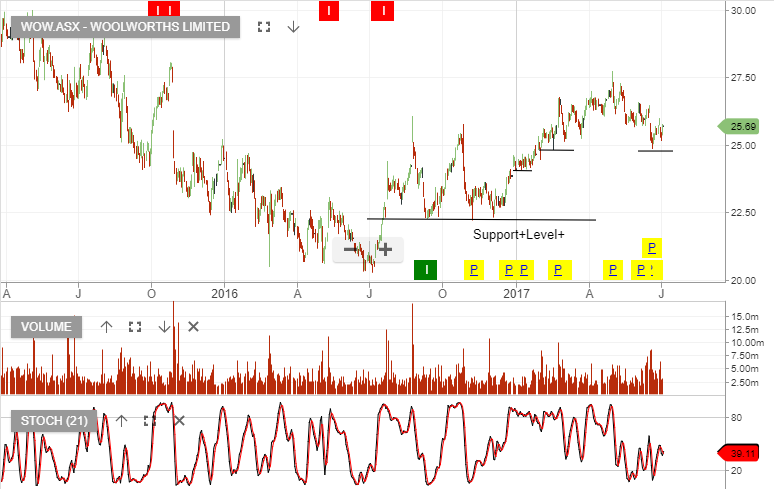
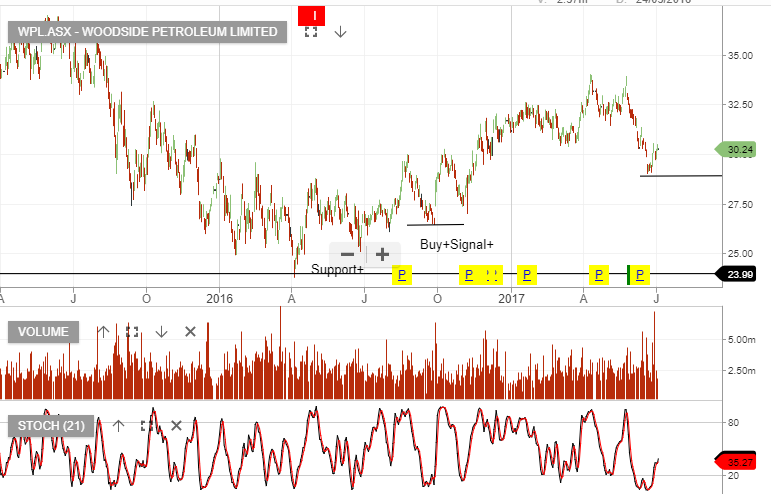
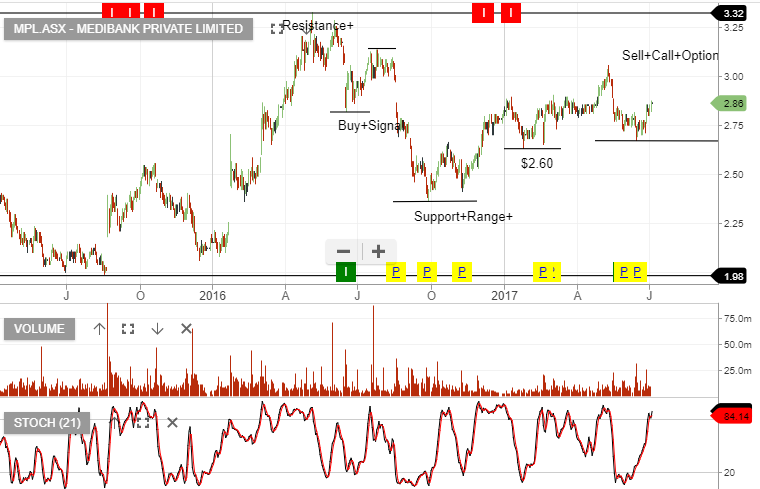
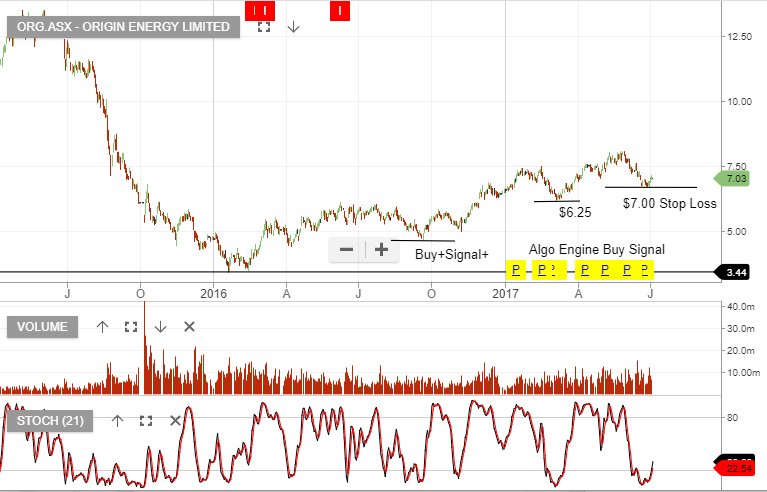
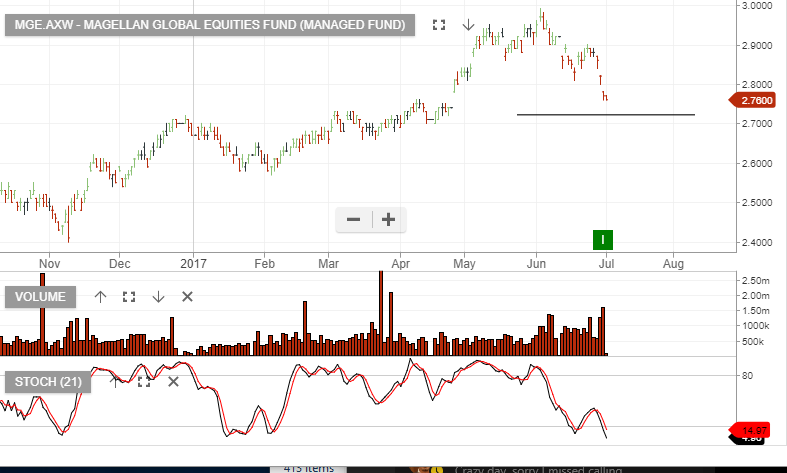
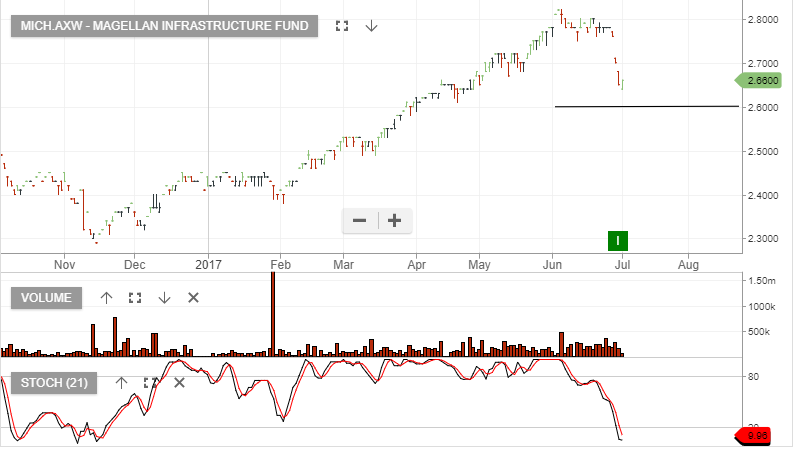
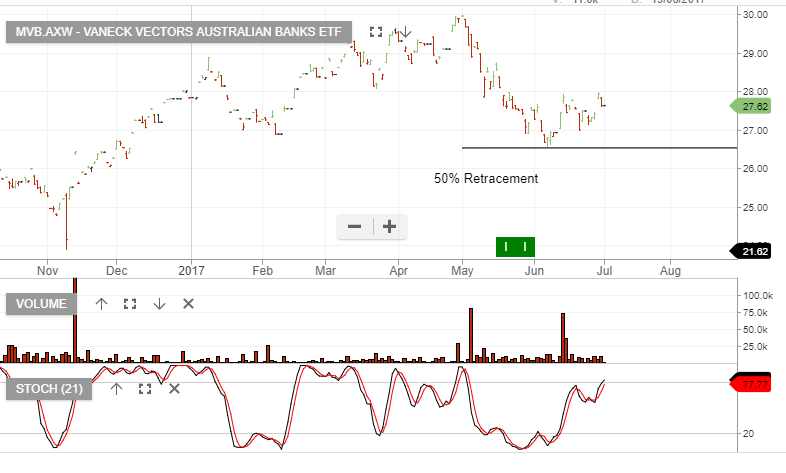
As bond yields have pushed higher in recent weeks, following global central banks hawkish tone, we’ve seen capital rotate out of yield sensitive names such as infrastructure and property and into financials & resources.
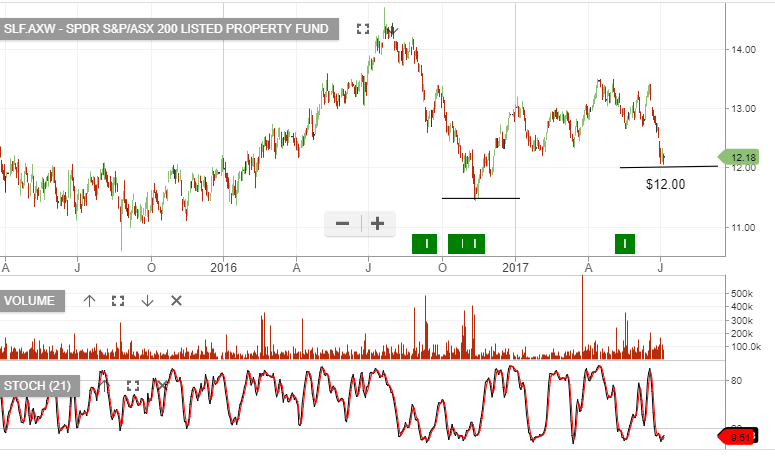
The rotation now leaves property stocks approaching an oversold price zone.
The chart below provides a broad-based picture of the listed property stocks within the ASX 200, via the SLF.AXW (SPDR ASX200 Listed Property ETF).
Our Algo Engine has triggered a buy signal at or near $12.00.
The Reserve Bank of Australia has released its financial aggregate data. Over the 12 months to May 2017, total credit provided to the private sector increased by 5.0%.
However, for the first time since 2011, the annual growth in dwelling loan approvals turned negative. This has also coincided with a slowdown in loan size growth.
We’re likely to see softer housing credit growth over the next 6 to 18 months.
The major banks have responded to the lower housing loan growth by announcing mortgage re-pricing starting with investor & interest only loans.
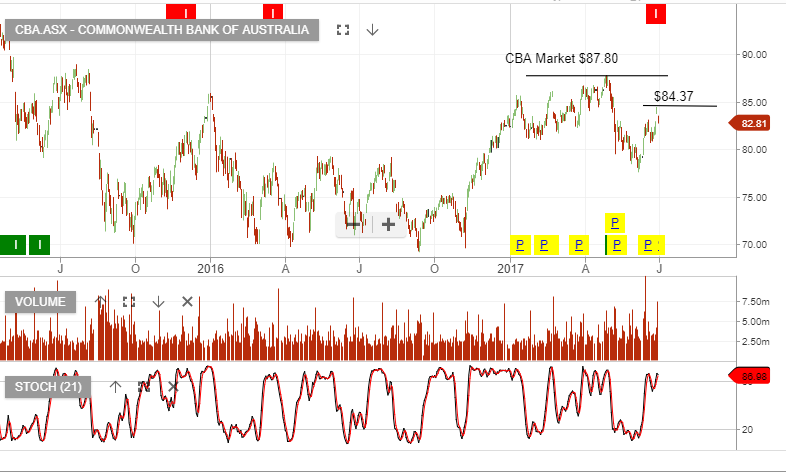
We believe the net-net impact on bank earnings will result in flat EPS growth over the next 12 – 24 months with the unknown risk being the potential pick-up in bad-debt provisioning.
The ASX200 finished the week up 0.1%. The materials sector was up 2.7% and the the worst performer was the Property Trusts sector, down 4.9% with Stockland down 5%.
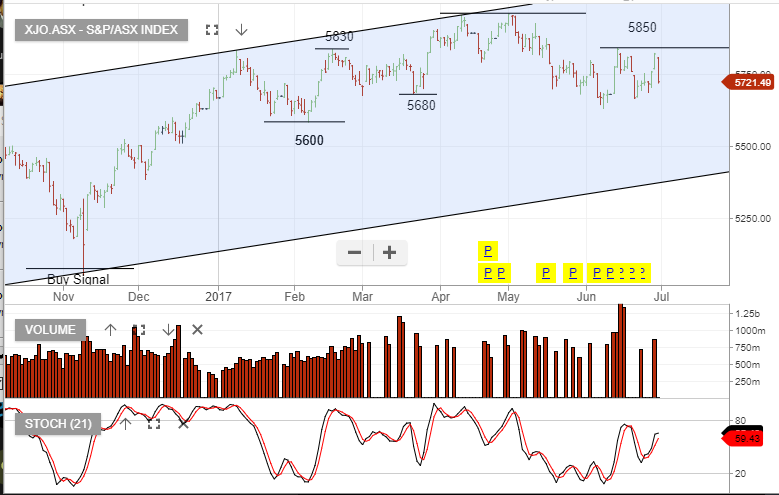
The chart below shows a further “lower high” pattern in the index. Thursday’s top at 5820 is now the third counter trend rally that has failed, since the minor downtrend started on the 1st of May, after topping at 5956.
We view 5850 as a key market level and as long as the index trades below this level, caution for downside range extension is advised.